In this article
Show where the work will come from
A signed long-term contract is useful, but it is not the only way to demonstrate genuine demand. A credible work letter can set out who will provide the work, the expected start, hours or utilisation, rates and likely duration. Be clear about whether those hours are guaranteed or only anticipated.
Build a simple cash-flow view around the work: revenue excluding or including GST as appropriate, fuel, operator wages, float or transport, insurance, servicing and payment terms. A machine can be profitable on paper yet leave the owner short of cash before the first customer invoice is paid.
Narrow the asset before approaching lenders
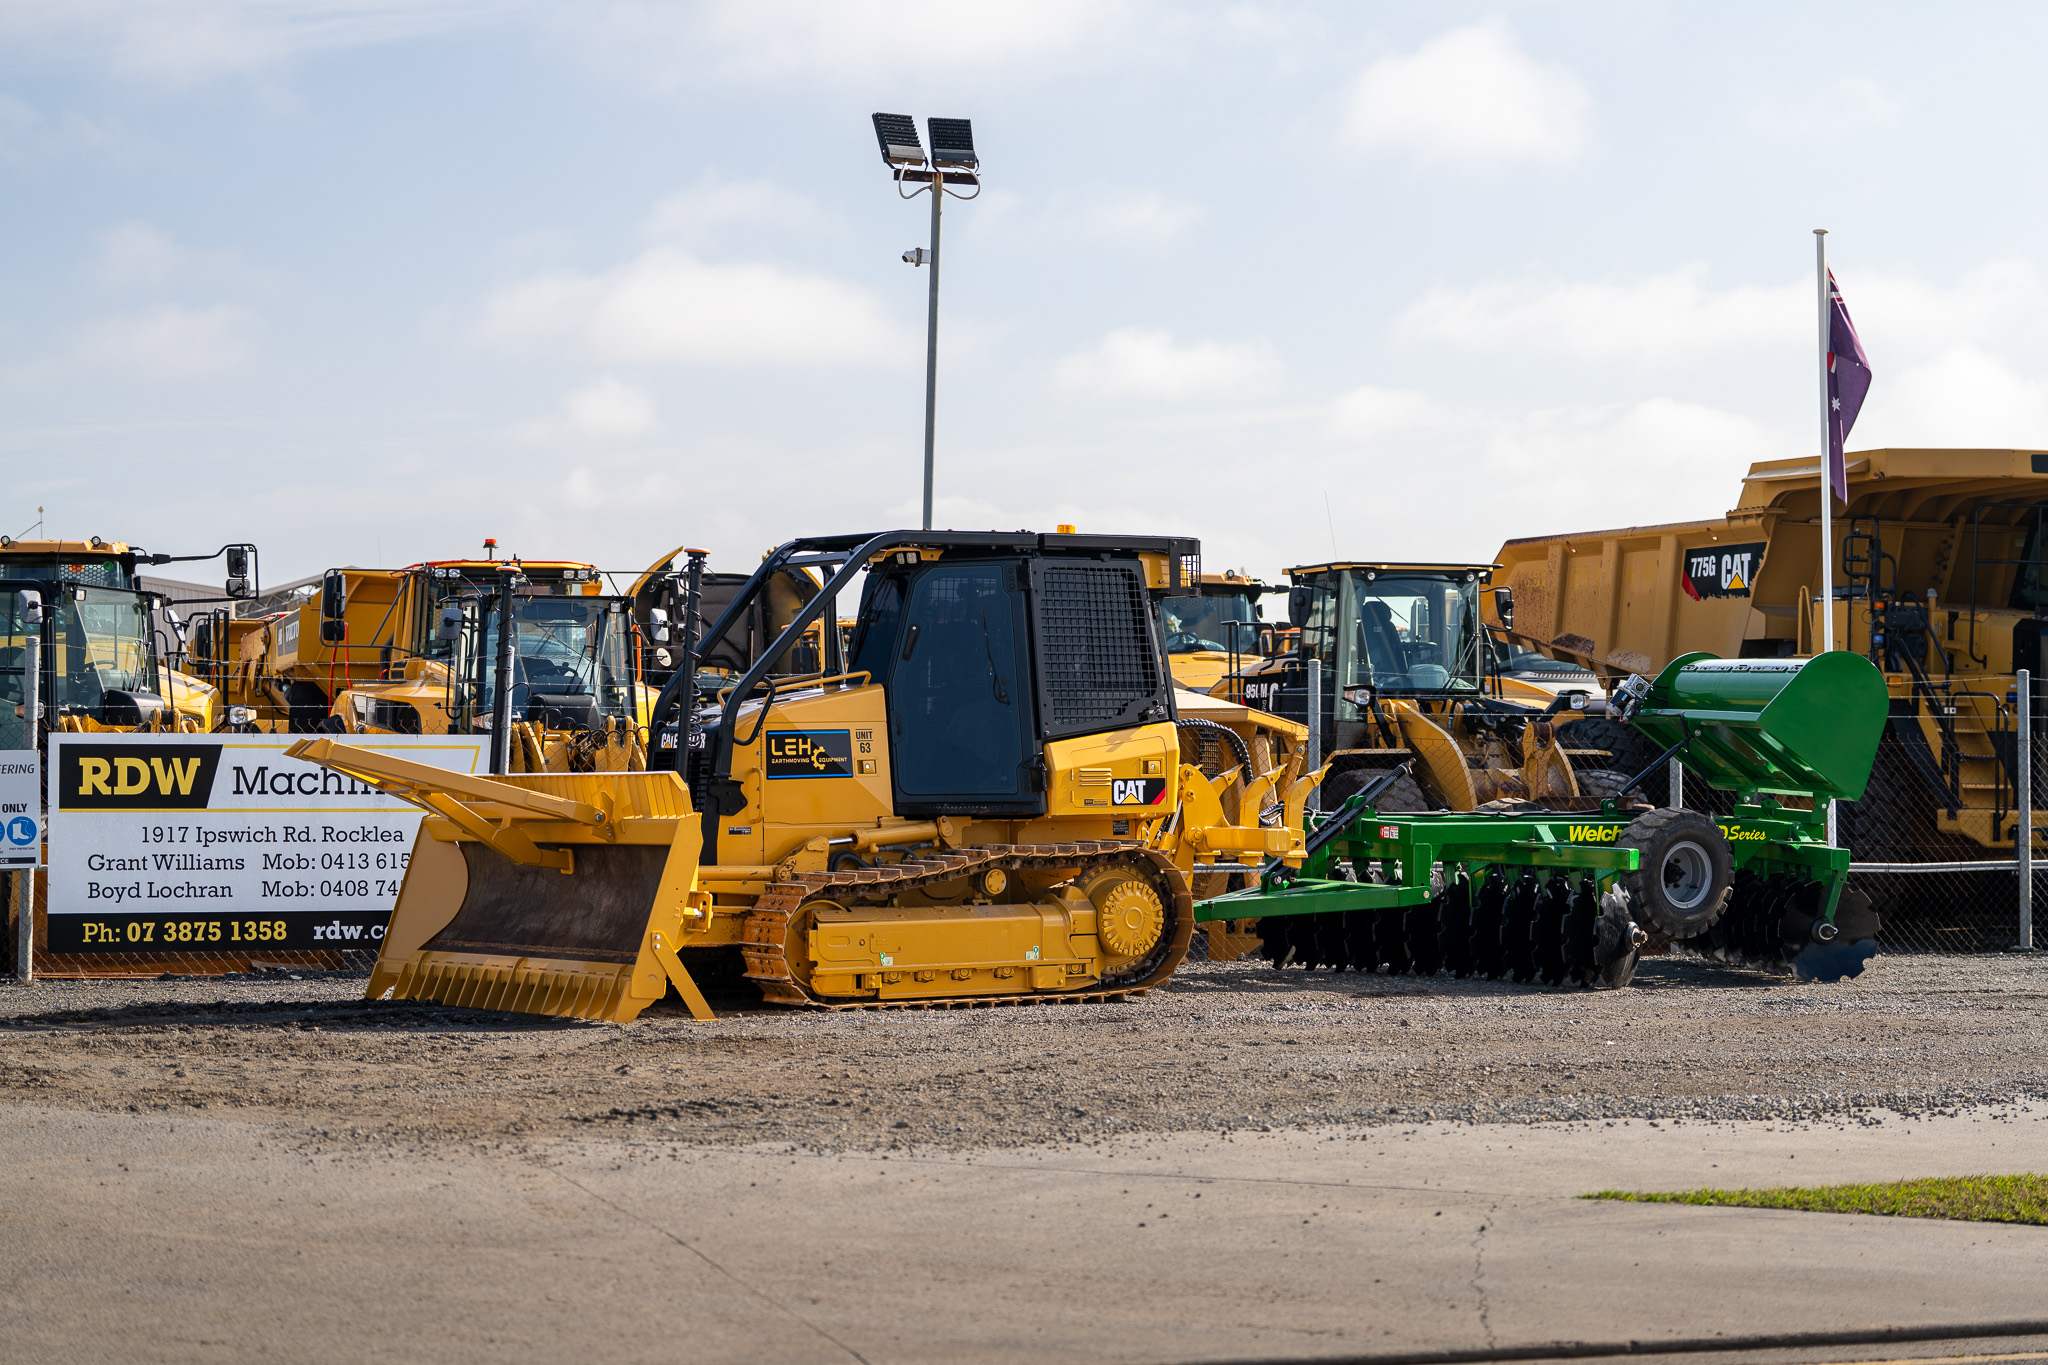
Bring two or three realistic equipment examples with model, age, hours, condition, price, seller and delivery timing. A dealer purchase and a private sale may require different checks. The lender may assess a new machine very differently from a ten- or twenty-year-old one.
Approval for one asset is not a blank cheque for anything in the marketplace. A late change in age, condition or price can trigger a new valuation, credit condition or lender search. Tell us early if the likely purchase changes.
Get your financial position in order
Have recent business and personal bank statements ready, with clean conduct where possible. If you are starting out, show the savings and working capital left after settlement. Organise tax returns and financial statements where available, a current list of assets and liabilities, your entity and ABN details, and the contact details for your accountant.
Explain the business structure accurately, including any company or trust. If financials are still being prepared, say so. A strong application presents the real position clearly; it does not dress up a forecast as contracted income.
The short checklist
Work source and start date; expected hours, rates and customer payment terms; operating costs and insurance; two or three suitable assets and seller details; savings and cash left after purchase; bank conduct; financials, tax returns and liabilities; correct borrower entity and accountant contact. These are the ingredients for a proper lender discussion.
Preparation is about more than getting a yes. It may change which lender will consider the deal, the required deposit, pricing, repayment timing and the headroom the business keeps after its first purchase.
Want to know more or talk through your options? Reach out to James and Dan anytime.