The next requirement.
A clear funding purpose, a realistic repayment plan and the right information to approach suitable lenders.
 Get started

Overdrafts, term loans, debtor finance and trade facilities considered alongside your equipment debt and cash flow. Work directly with James and Dan, credit analysts turned brokers who prepare the business case and manage the lender conversations.
Speak with James and Dan ↗Tell us about the business funding you have in mind.
"*" indicates required fields
We work with established business owners managing growth, cash flow and changing funding needs. Whether it is a new contract, stock purchase or a broader debt restructure, we look at how the business earns, spends and collects cash.
These are typical clients, not a fixed rule. Tell us what the funding needs to achieve, the amount and the timing. The right facility depends on trading performance, existing debt, available security and lender criteria.
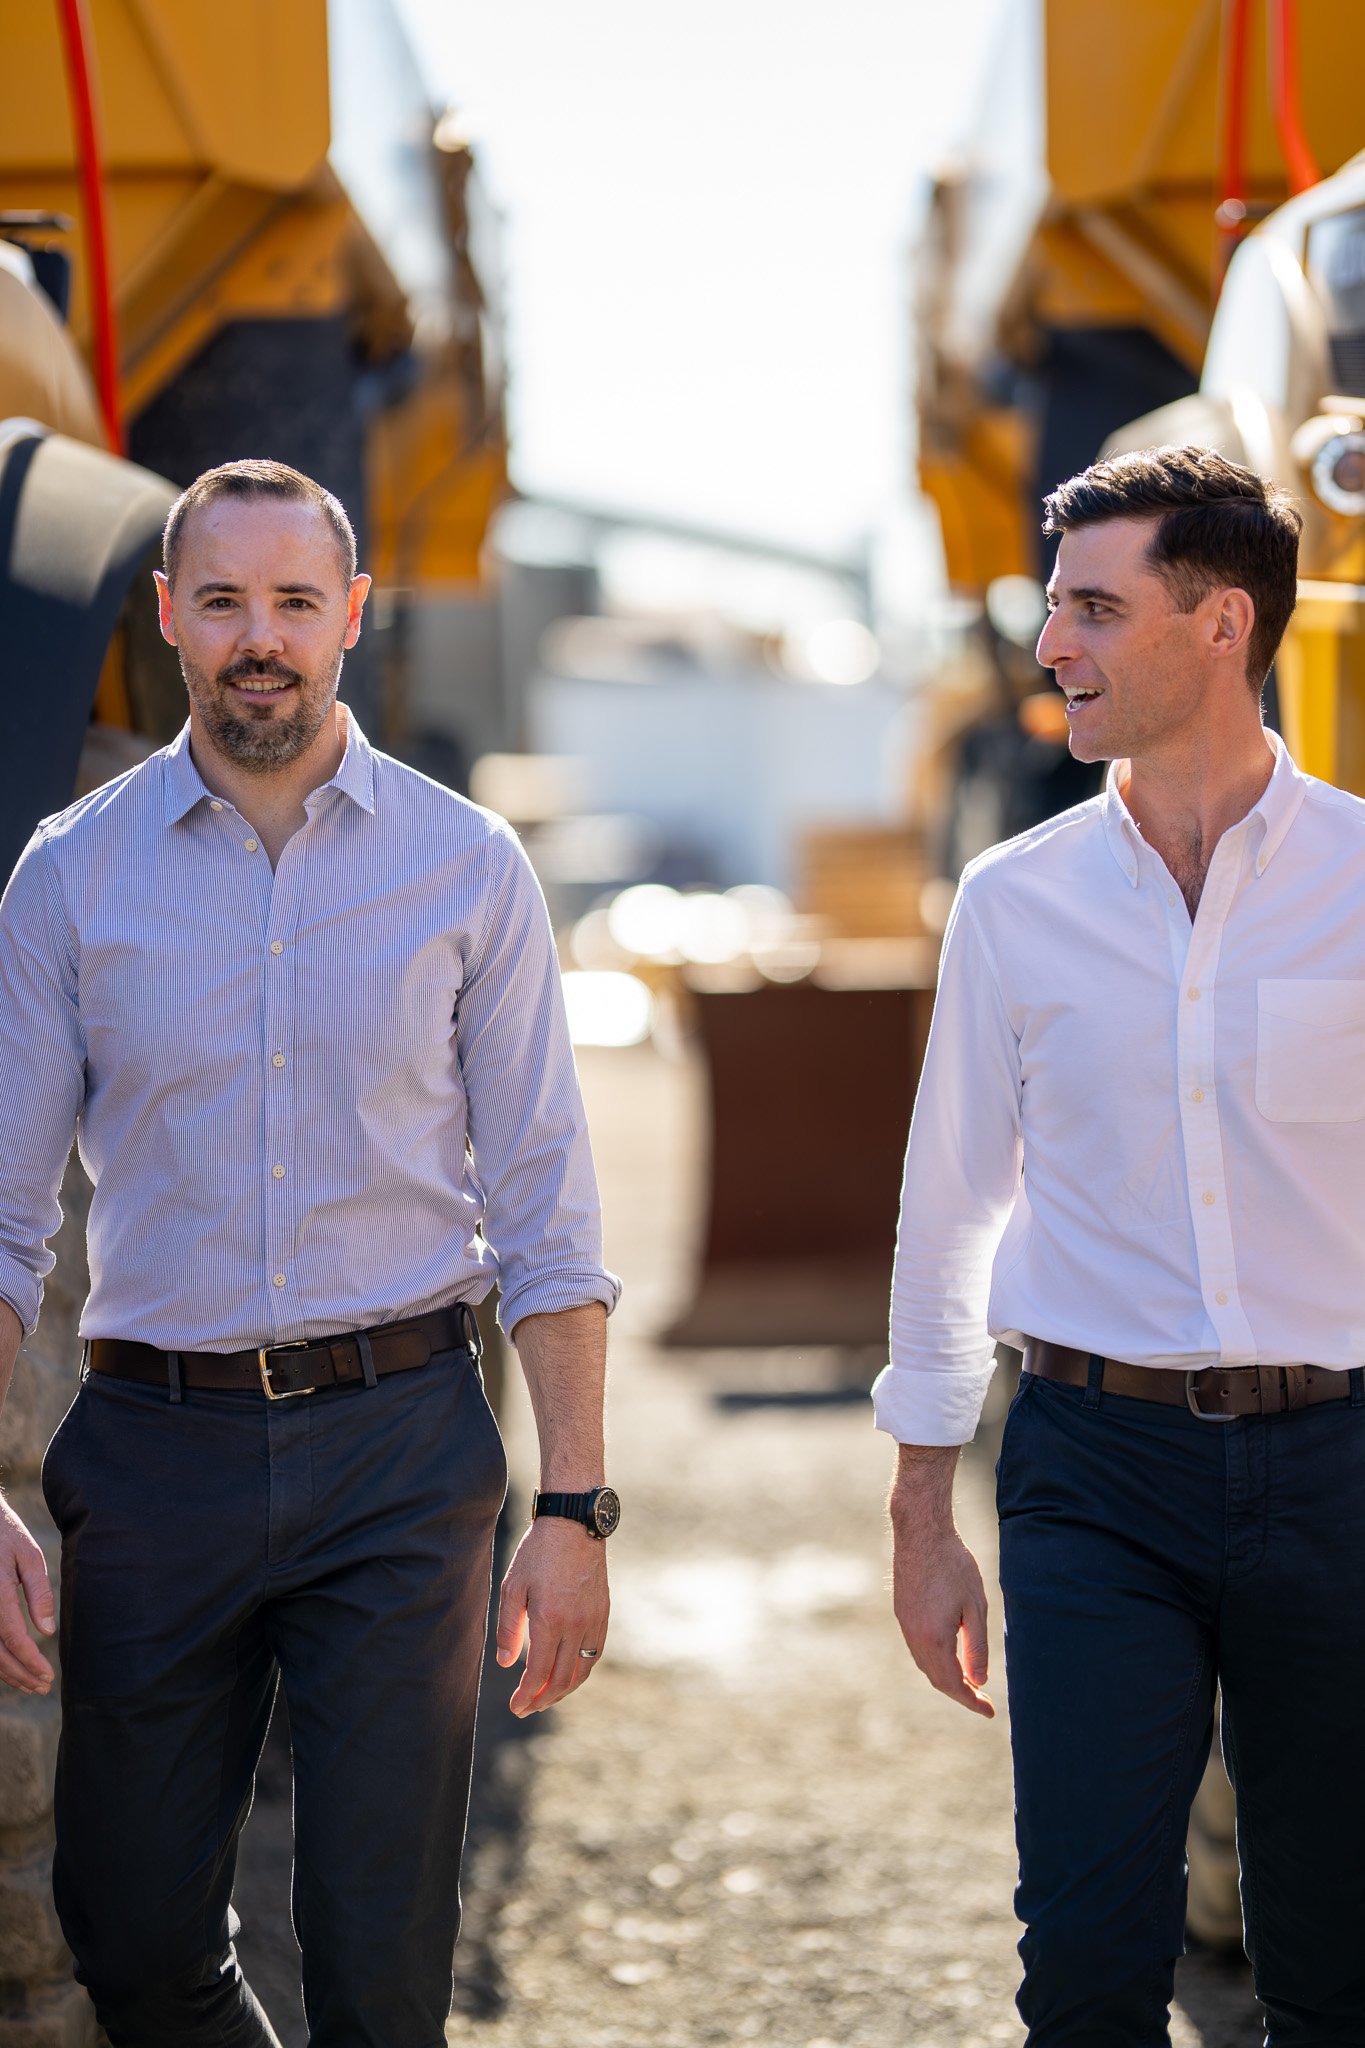
Deal directly with James Allan and Daniel Salajan, with 35 years of combined experience across bank credit and broking.
An owner-led brokerage with no sales team, KPIs or sales targets. We don’t sell, we consult. Deal directly with us, with the time and ongoing attention your business deserves.
We look deeper into your financials and reporting, working with you and your accountant to explain the numbers, identify opportunities and strengthen your position before approaching lenders.
Years in bank and brokerage credit roles give you the luxury of hindsight. We know how lenders assess a business and sharpen the application before it lands, bringing expertise and guidance beyond simply facilitating a low doc loan.
When experience matters, see how we have worked with the people behind the equipment.
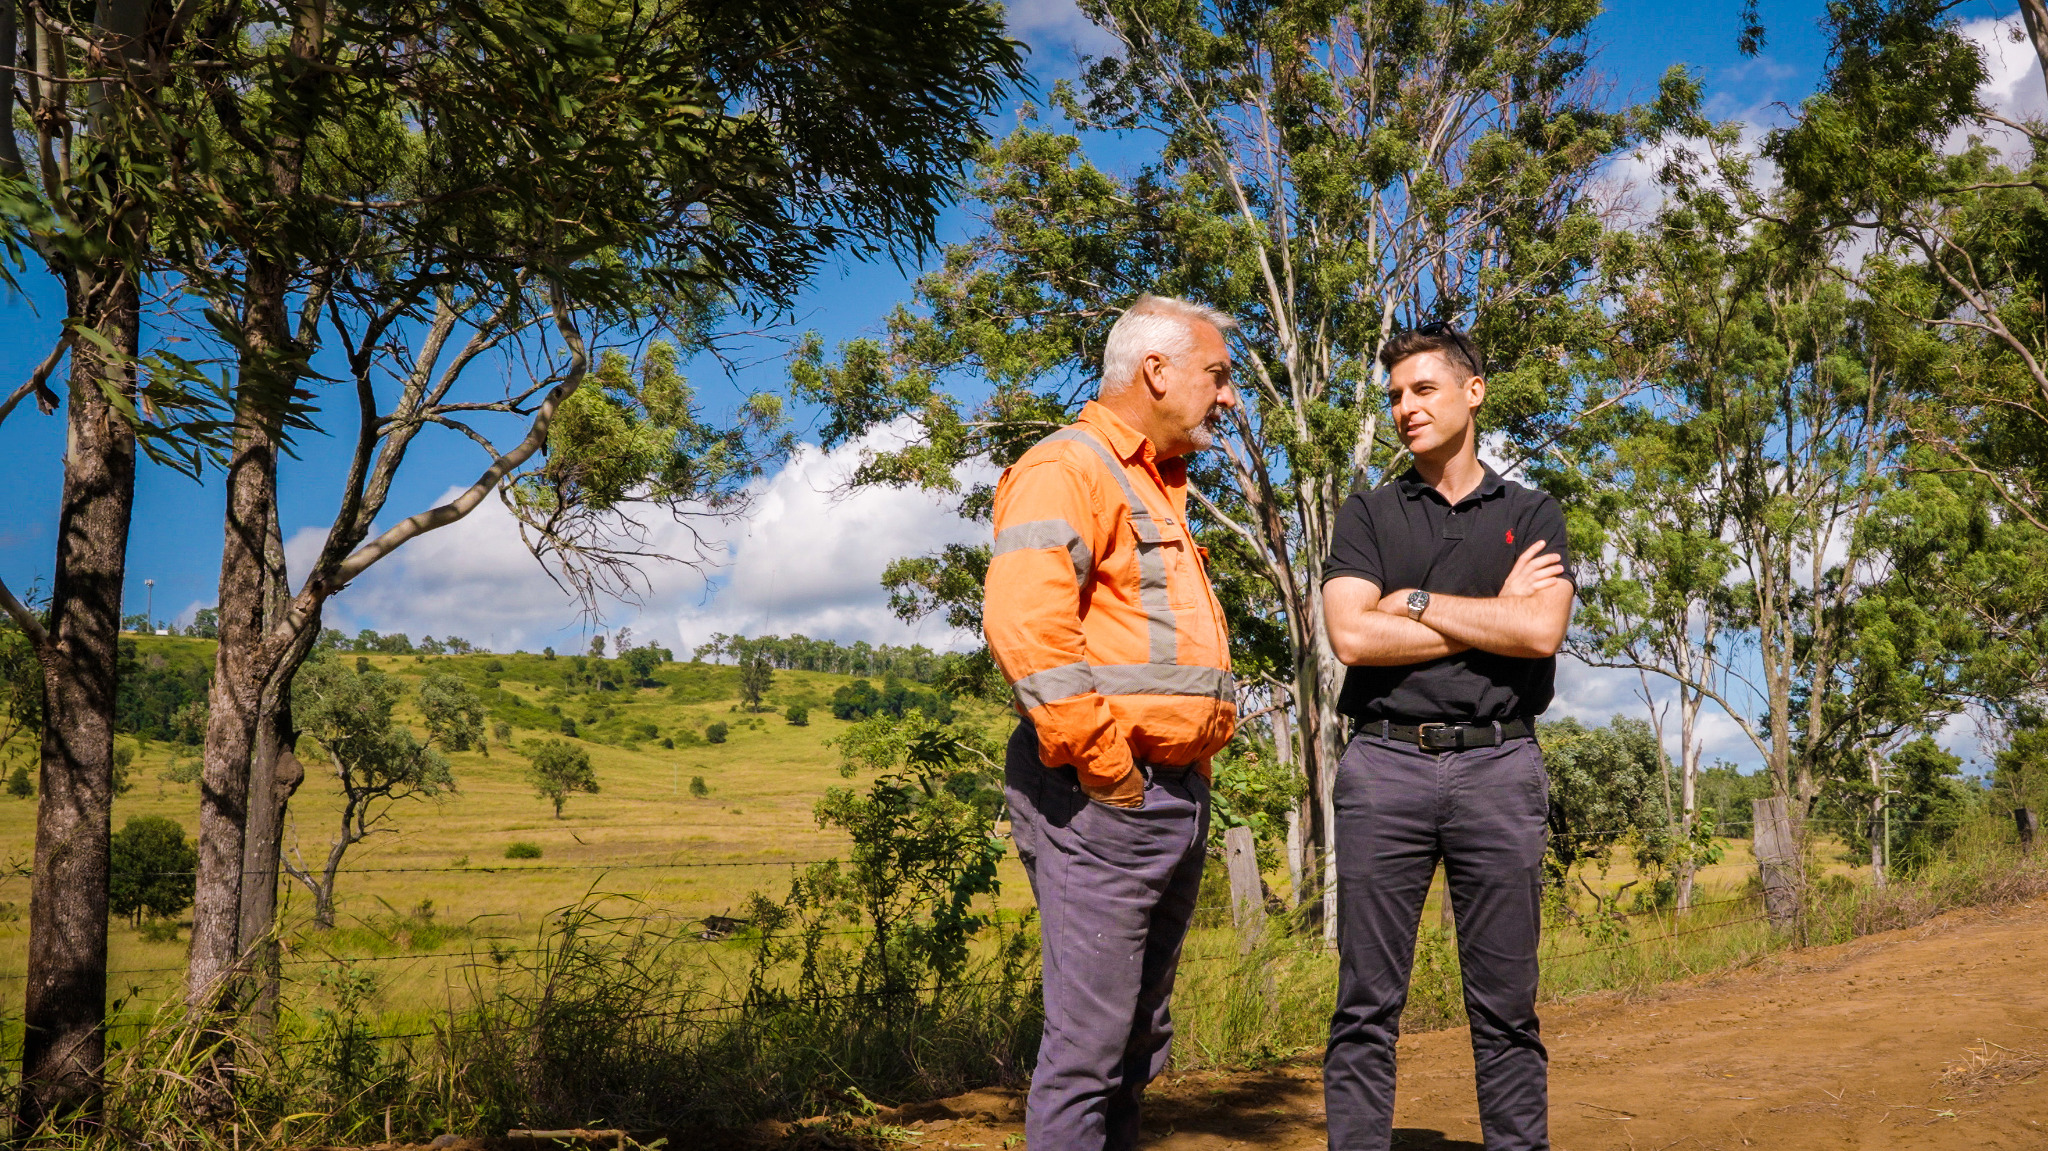
 A considered funding plan behind 66+ equipment purchases.See full story
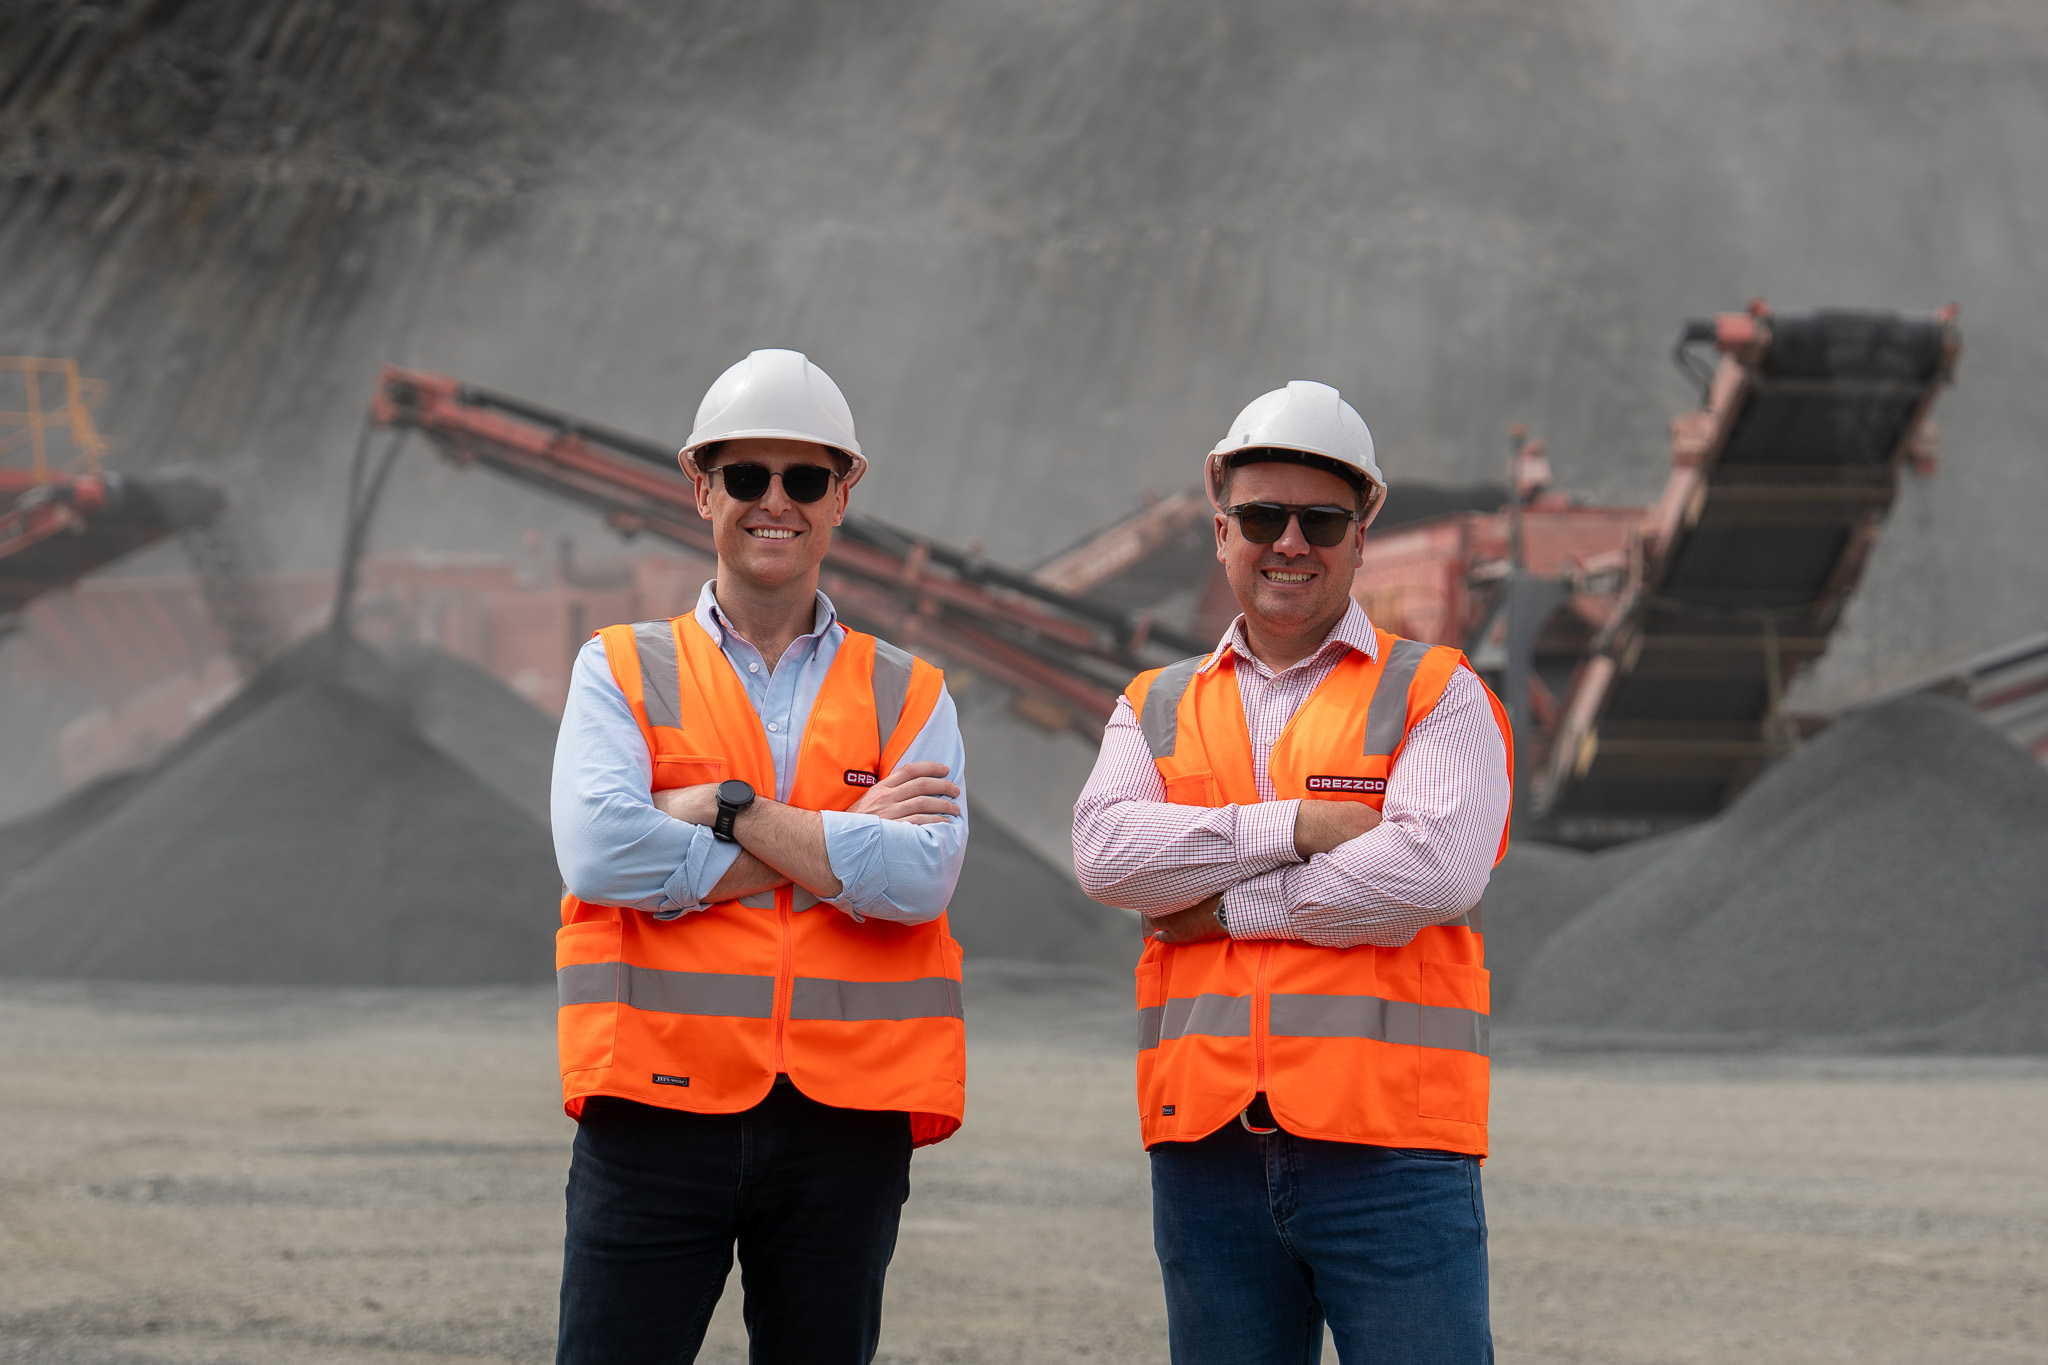
 Funding an acquisition and a new quarry contract.See full story
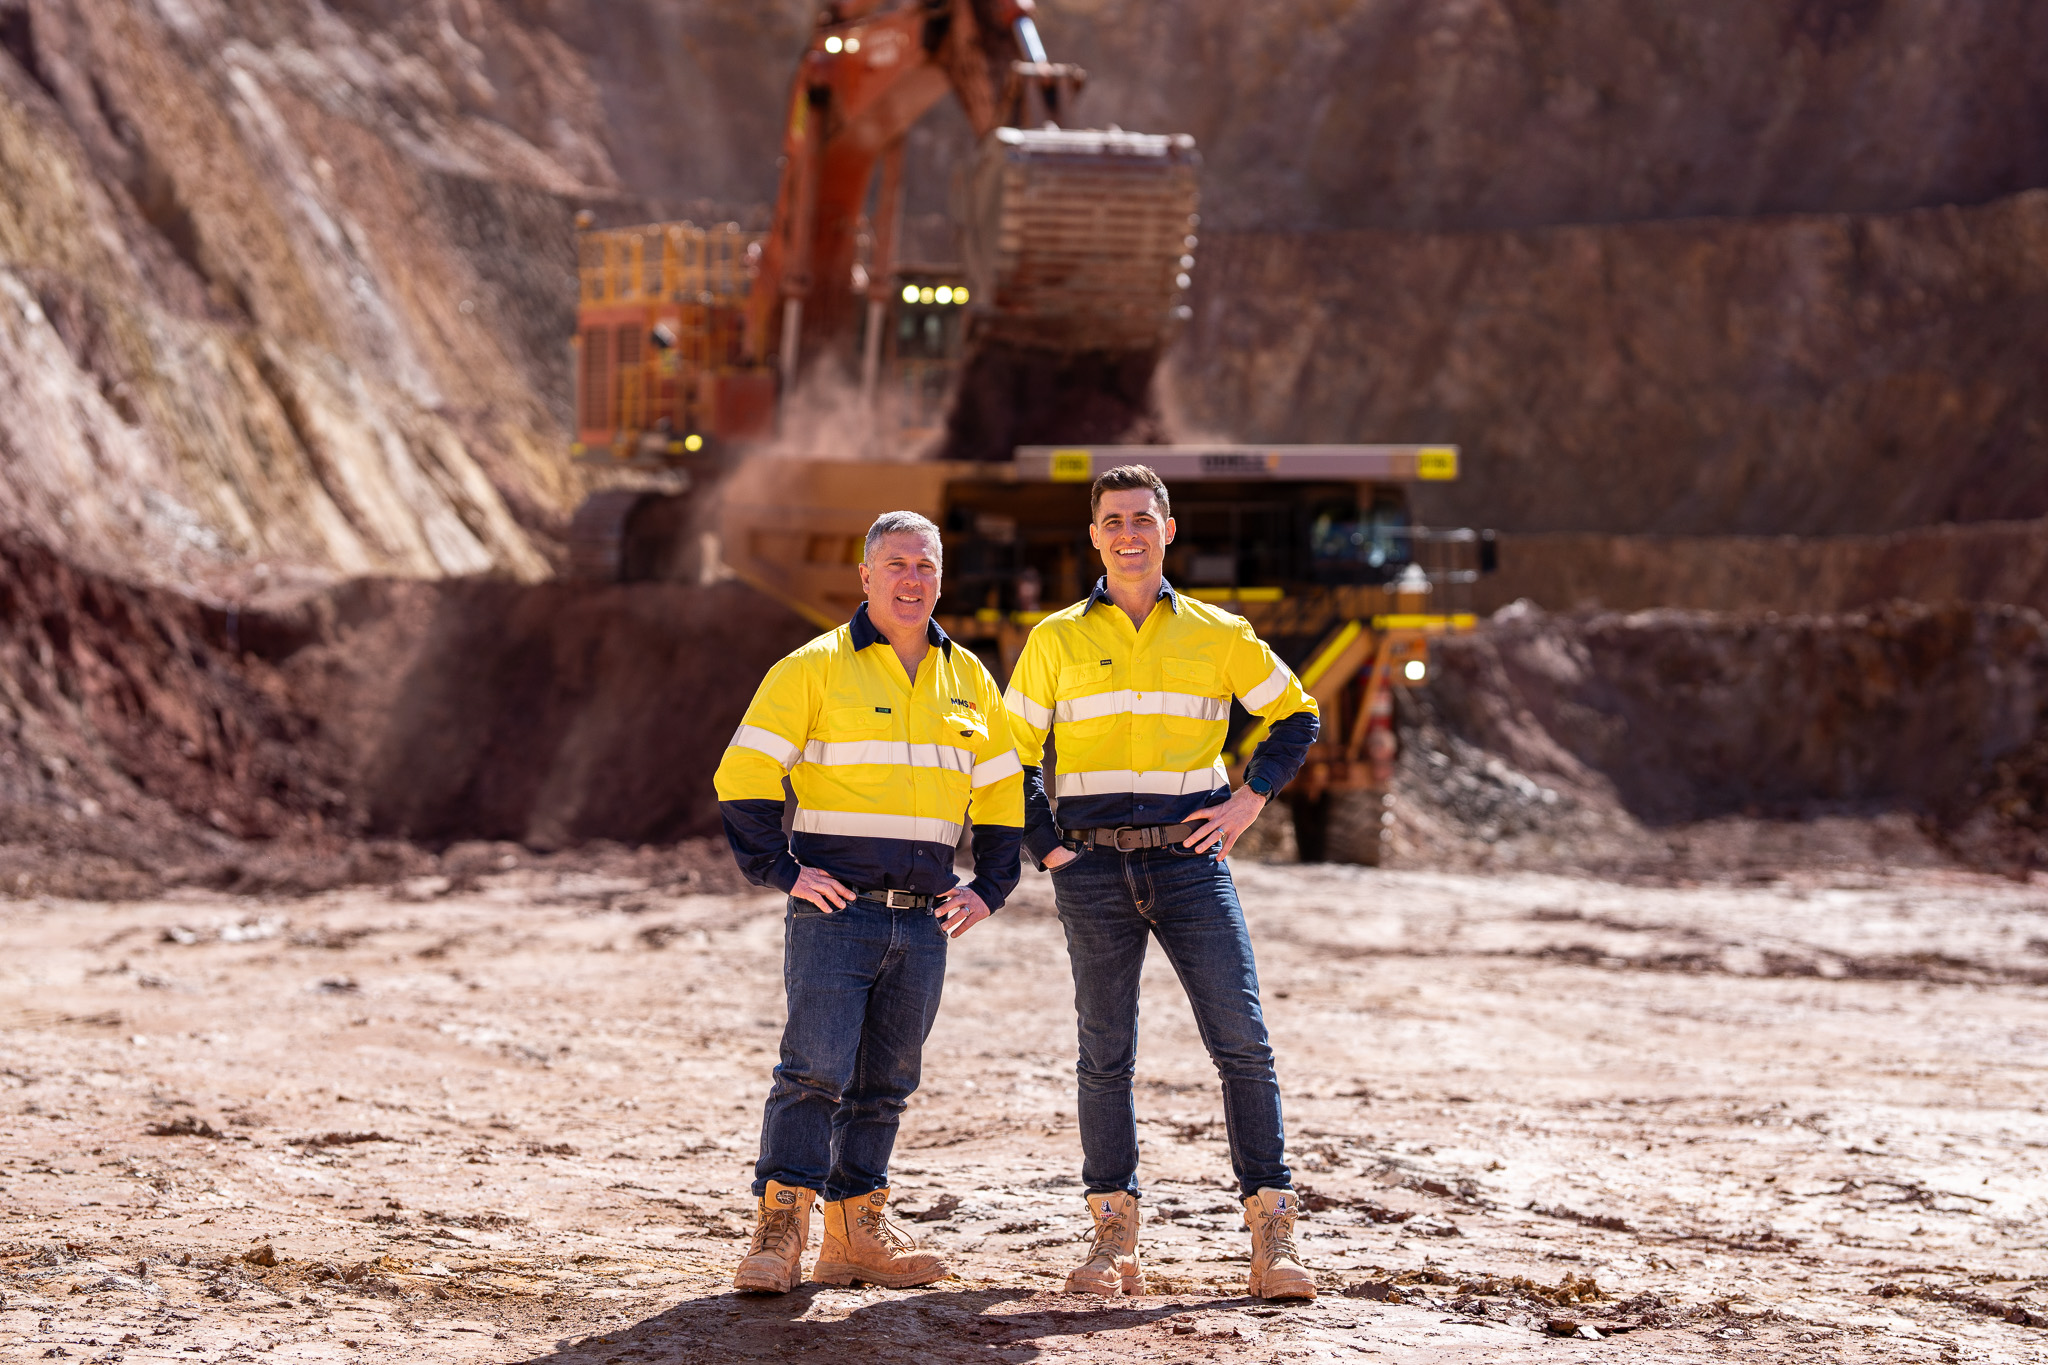
 More than 200 civil and mining assets financed over 10 years.See full story
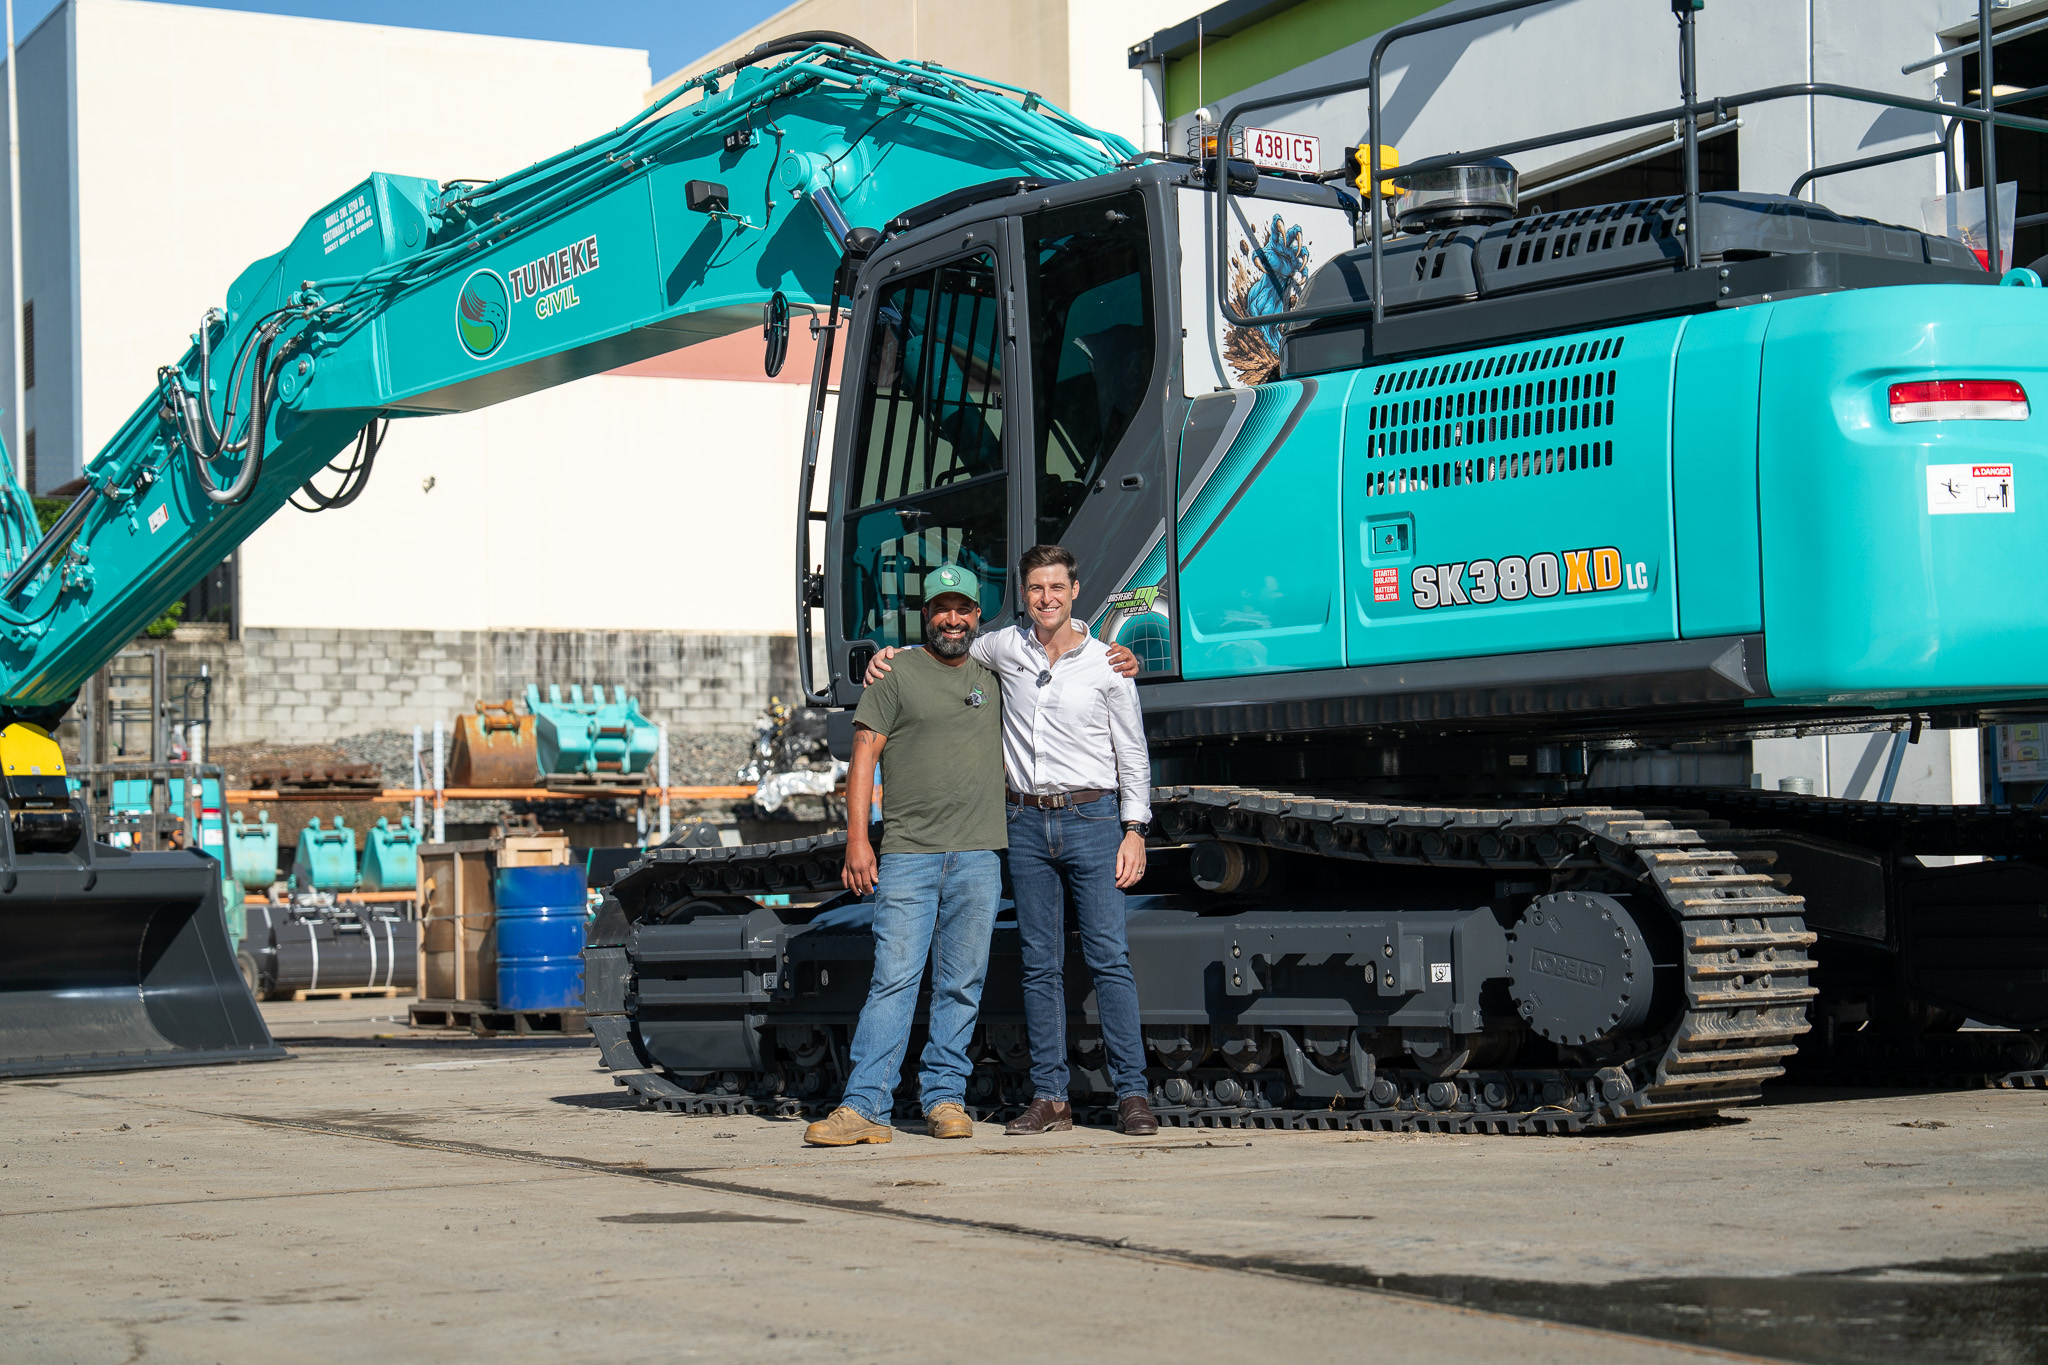
 Seven new Kobelcos to update an ageing fleet.See full story
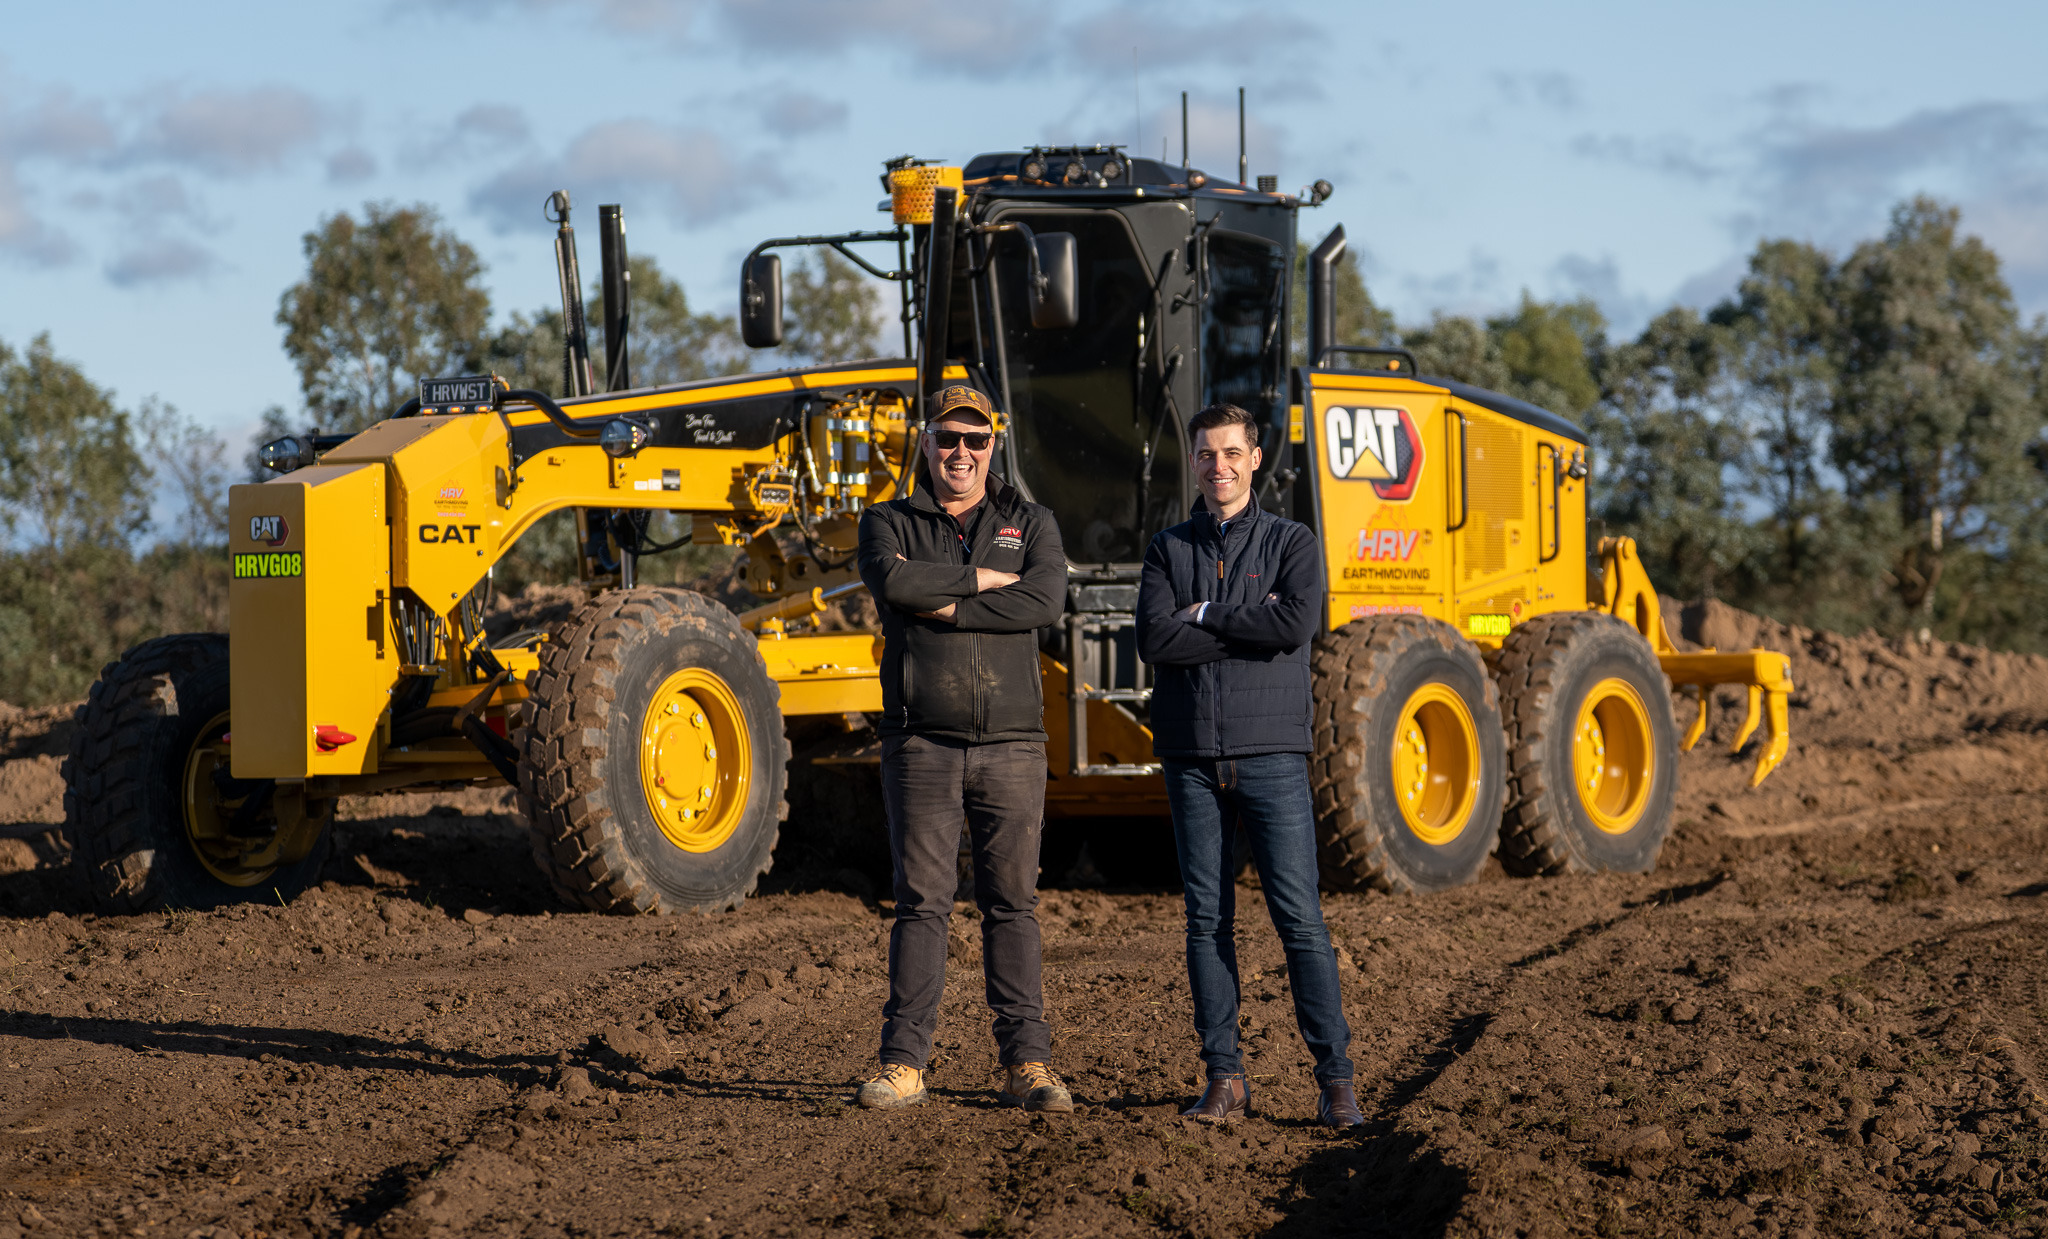
 Graders, dozers, utes and a float with major banks.See full story
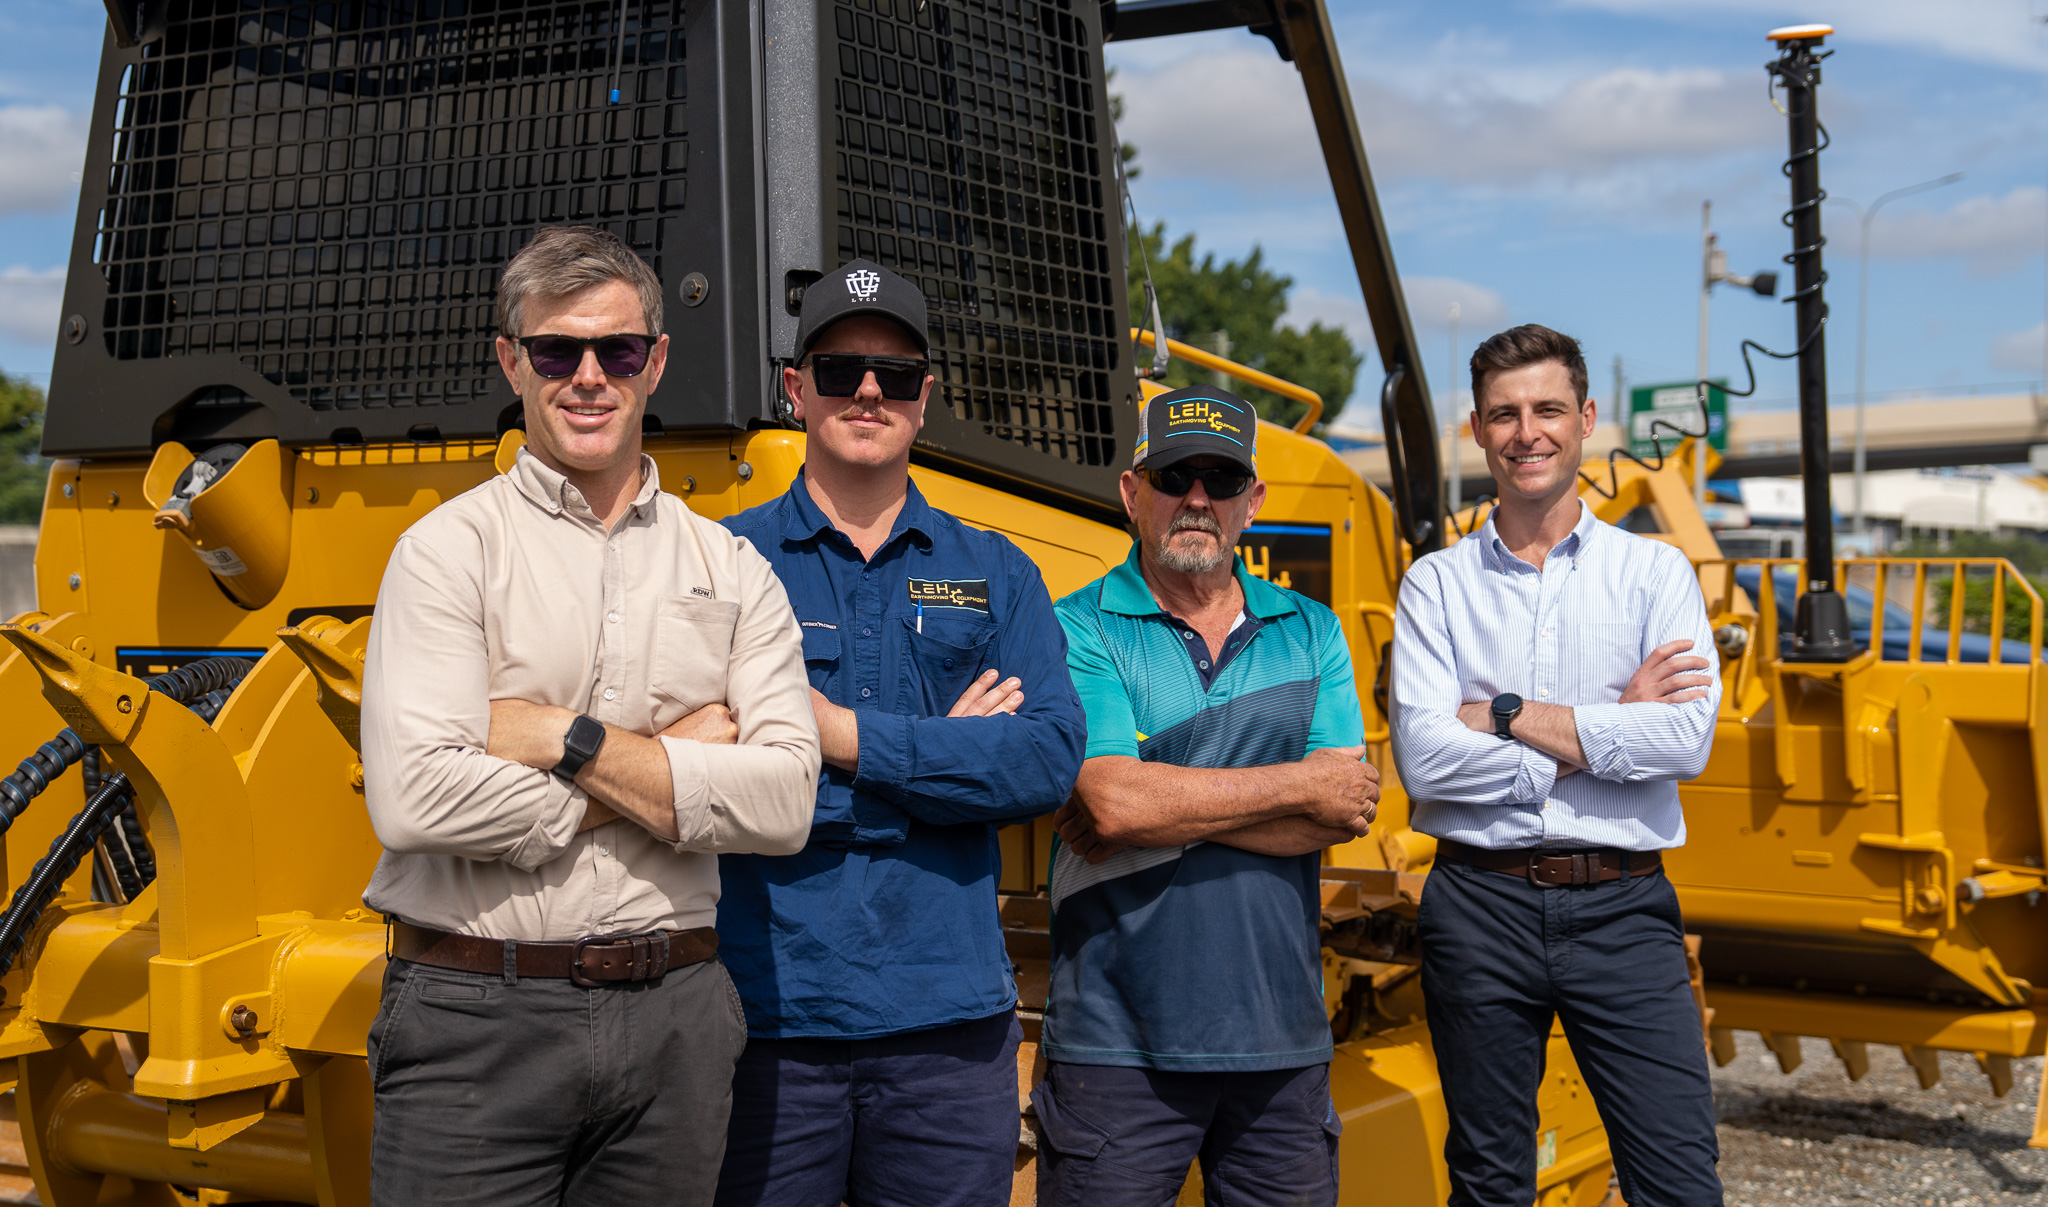
 From start-up to three dozers in three years.See full story

A clear funding purpose, a realistic repayment plan and the right information to approach suitable lenders.
Cash flow, contracts, stock and equipment commitments considered together as the business expands.
Coordinated facilities, lender relationships and debt reviews that support the business as its needs become more complex.
We match the facility to the purpose and repayment source, then consider how it fits with existing debt and future funding needs.
Funding for a defined business purpose, repaid over an agreed term. We assess recent reporting, cash flow and existing commitments to prepare the application for suitable banks and specialist business lenders.
A facility to manage timing gaps between operating costs and receipts. We work through the cash cycle, expected utilisation and review requirements, rather than treating short-term funding as a permanent fix.
Funding linked to eligible unpaid invoices can help bridge customer payment terms. We consider the debtor book, customer concentration, invoicing practices and costs before approaching appropriate lenders.
Facilities that support eligible supplier payments, stock purchases and imports. We map the order, payment and collection cycle so the proposed funding matches the business and transaction.
Eligible plant, equipment or commercial property may support a funding requirement. We review ownership, existing security, valuations and repayment capacity to assess options without assuming that an asset value alone will determine approval.
Review debt spread across lenders and facilities that no longer suit. We consider restructuring, lender capacity and monthly repayment pressure, accounting for security, payout costs and the total cost of a longer term.

James and Dan have worked in bank credit and broking. We review the financials, existing debt and supporting information before approaching lenders, and work with you and your advisers to explain material entries or changes clearly. A well prepared application gives lenders a fairer picture of the business.
We give you a direct view of the funding opportunities we see, where the challenges sit and how confident we are in the proposed approach. We map out existing debt, lender exposures and available capacity between all lenders, so you get complete visibility to the funding opportunities available to your business.
The lowest priced lender for today’s funding requirement may be the lender you need for a much larger facility tomorrow. We consider where each asset belongs across the available banks and specialist lenders, protecting room for future purchases where we can.
Where the business and lender criteria support it, we can pursue a coordinated funding plan with major banks. We consider working capital, term debt, security and review requirements together so facilities support the business as it grows.
As your needs grow, we can introduce and work alongside suitable business or corporate bankers. That can open conversations about broader facilities, including working capital, trade funding and commercial property finance, while keeping the wider debt strategy connected.
Unencumbered equipment, or assets nearing the end of their finance term, may offer an opportunity to release equity in times of a cashflow pinch. We can assess the equipment, valuation and lender options to see whether refinancing could return useful cash to the business.
Business owners need someone they can speak with candidly. We bring an independent perspective shaped by years of working with operators across the country, keep your information confidential and stay involved as your plans change.
A new contract, a cash flow gap or a bigger growth plan. Let’s map the facilities and capacity your business needs.
Let’s grow togetherCredit expertise, direct relationships and a wider choice of lenders, backed by recognised work in commercial finance.
Commercial Finance Awards
Finalist · 2026
Australian Broking Awards
Finalist 2026
CAFBA
Finalist 2023
James Allan on commercial finance
Featured guest
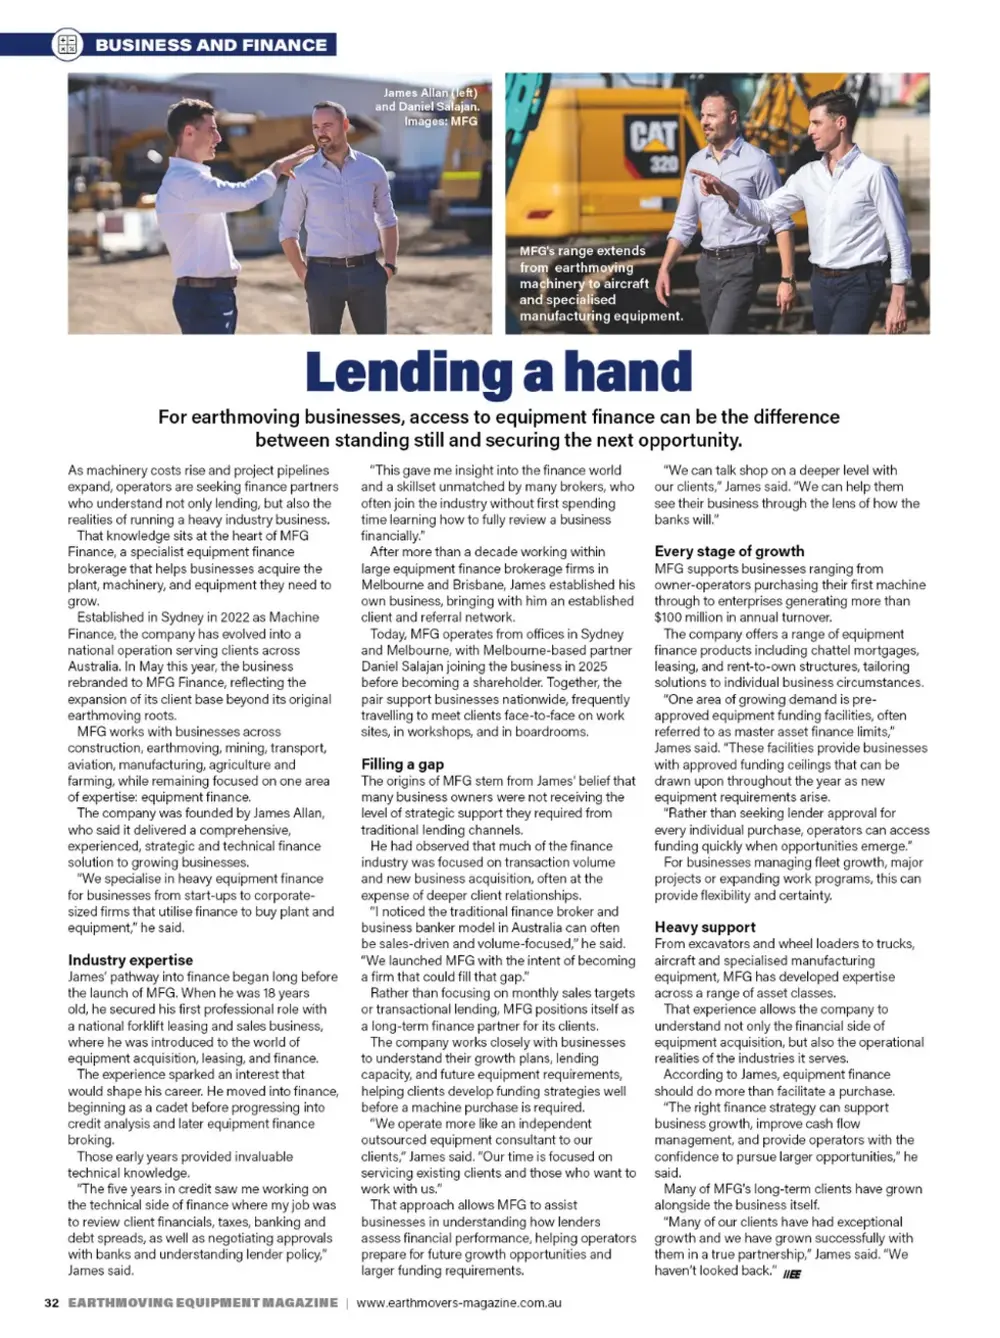
“Lending a hand”
Featured article
MFG is directly accredited with all major banks, alongside an extensive panel of non-bank, specialist and private lenders.
 CAFBA 101556
 FBAA M-359967
 AFCA 89354
Panel shown is indicative and subject to lender accreditation, credit policy and transaction requirements.
See how term, rate, balloon and payment timing change the monthly commitment.
Illustration only. Assumes a fixed nominal annual rate divided into monthly periods, level monthly payments and a balloon due at the end. Excludes fees, taxes and insurance. In advance means the first repayment is made at the start. This is not a lender quote.
Talk through the purchase →
We can assess business term loans, overdrafts, debtor finance, trade and import facilities, and eligible asset-backed funding. The appropriate option depends on the purpose, cash flow, security and lender criteria.
Usually recent business financials, current management reporting, bank statements and a schedule of existing debt. The exact requirements depend on the facility and lender. We will outline what is needed before preparing the application.
We can review the cash cycle and consider suitable working capital or debtor finance options. We look at why the gap occurs, the debtor book and the repayment source before recommending an approach.
Yes. We map the facilities, repayments, security and lender exposures to see whether the arrangement still suits. Any restructure needs to account for payout costs, available security and the total borrowing cost.
A different term or repayment structure may ease the monthly commitment. It can also increase the total interest paid. We compare those tradeoffs and any payout costs before you decide.
Not every business facility requires property. We can assess secured and unsecured options, but availability, limits, pricing and guarantees depend on the business and lender.
It depends on the facility, the business and how ready the information is. Tell us the deadline at the start and we will explain what is realistic. We do not promise an approval before assessing the position.
Yes. With your permission, we can work alongside your accountant and suitable business or corporate bankers to explain the reporting and coordinate the proposed funding.
We do not charge an upfront brokerage establishment fee. We are paid by lenders when a transaction settles. We will show you any lender fees in the proposed terms before you commit.
Tell us the funding purpose, amount and timing, plus a little about the business and its existing debt. James or Dan will talk through the position and outline the information needed for suitable lenders.
Managing cash flow, planning growth or reviewing existing debt? Start with the situation as it is. We’ll talk through the funding purpose, the timing and the wider business position.
Tell us what the funding needs to achieve and when you need it.