Buying your first truck or trailer?
Starting out as an owner-driver or arranging your first transport finance loan? We’ll assess the purchase, work pipeline and repayment options with you.
 Get started
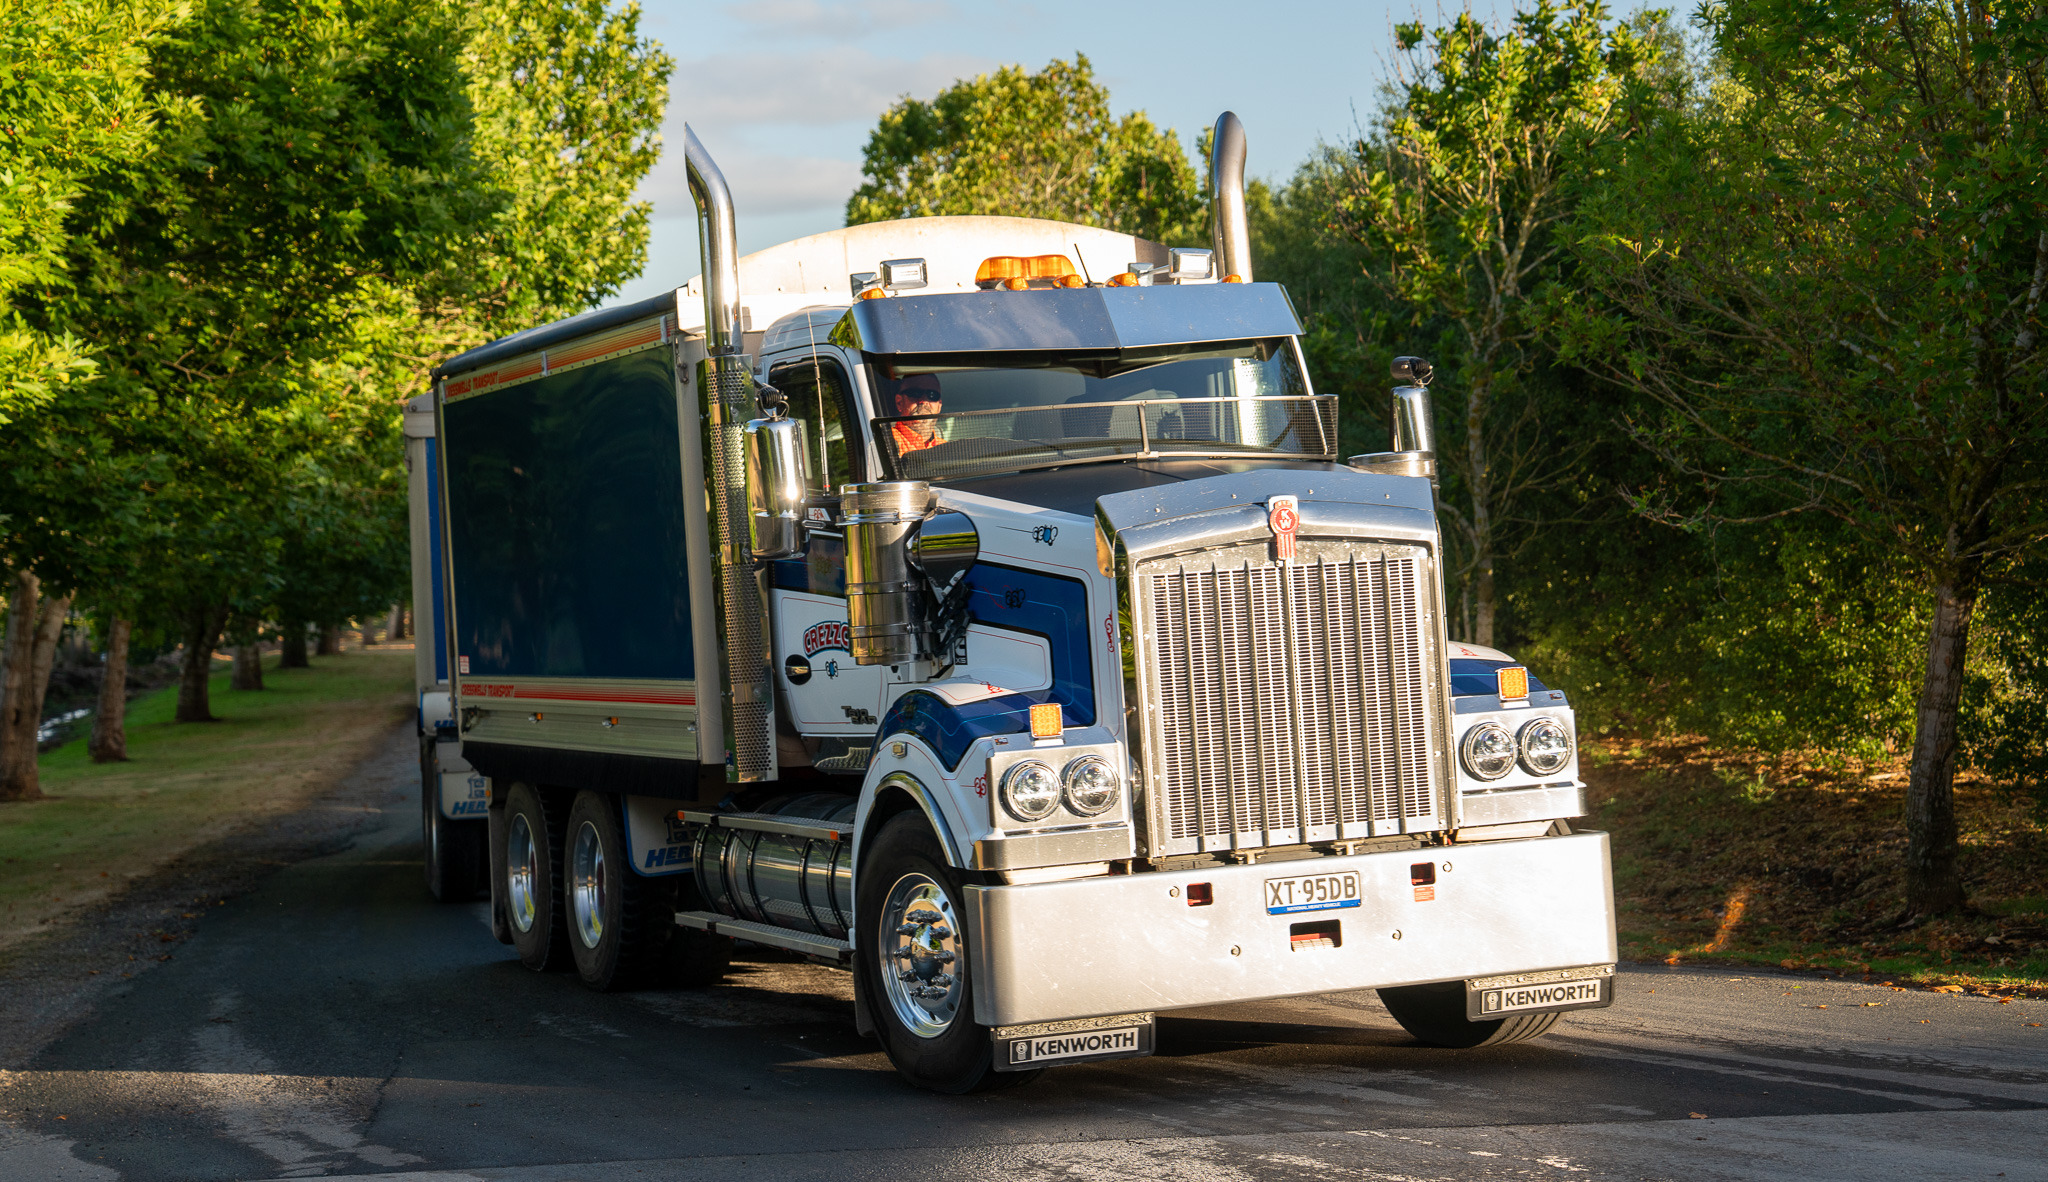
New and used prime movers, rigid trucks, trailers and specialist transport equipment. James and Dan assess low doc, full doc and master limits for eligible operators, then manage the lenders and paperwork around your purchase timing.
Speak with James and Dan ↗Tell us about the next purchase you have in mind.
"*" indicates required fields
We work with business owners buying their next truck, replacing trailers or planning a larger fleet. From owner operators to established transport businesses, we look at the contracts, routes and cash flow behind the vehicles.
These are typical clients, not a fixed rule. If a truck or trailer supports your business, talk to us about the vehicle, seller and timing. New and used, dealer, private sale and auction purchases can all be assessed.
Starting out as an owner-driver or arranging your first transport finance loan? We’ll assess the purchase, work pipeline and repayment options with you.
Plan the next truck, trailer or replacement program around existing payouts, lender capacity and the work ahead.
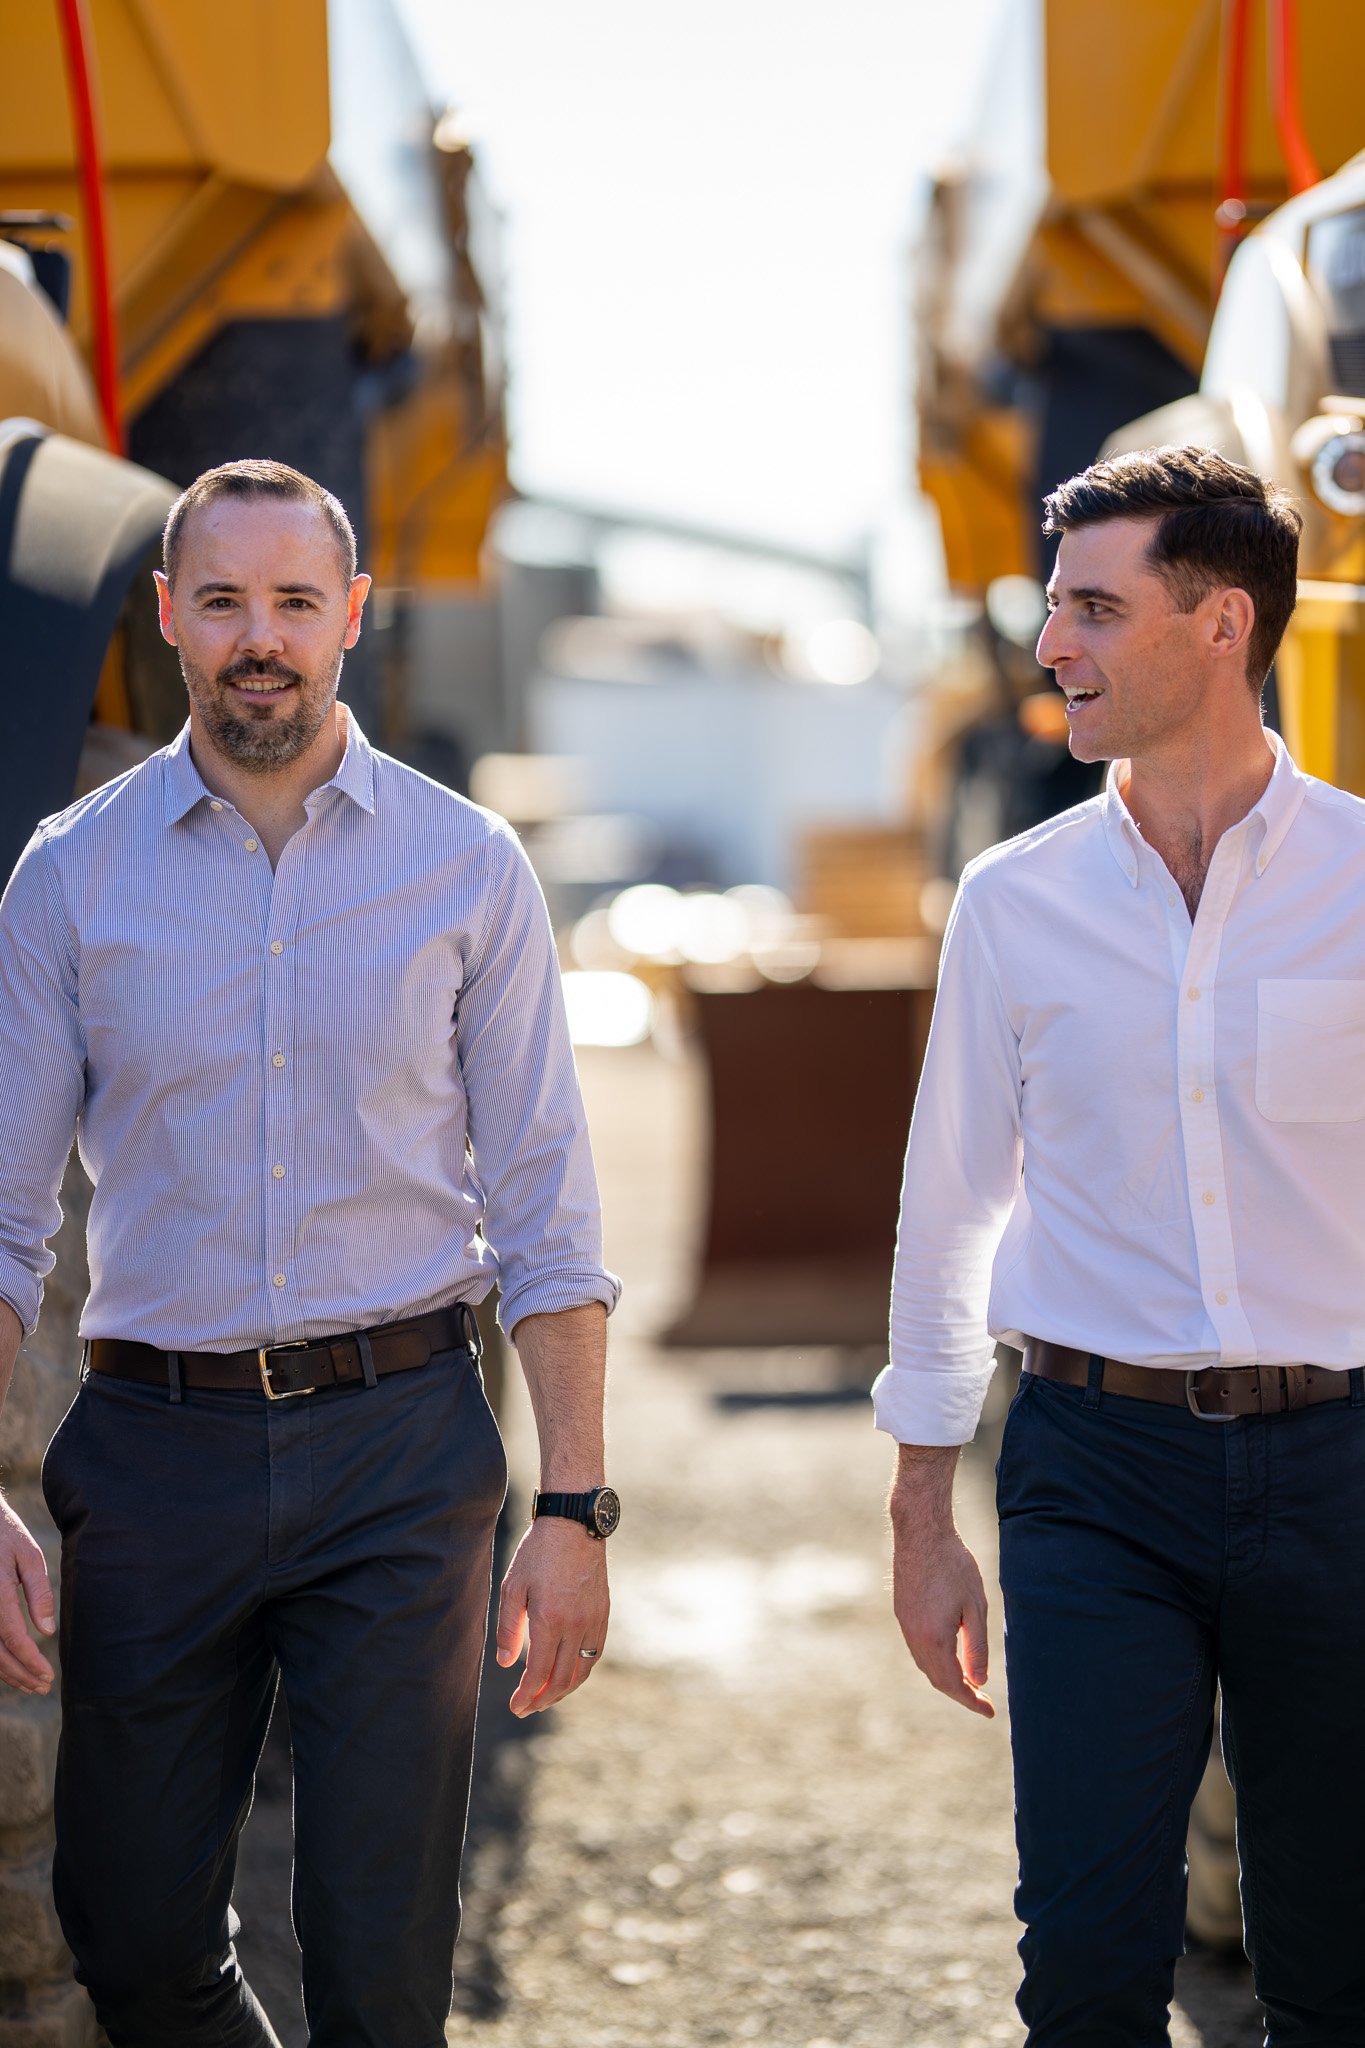
Deal directly with James Allan and Daniel Salajan, with 35 years of combined experience across bank credit and broking.
An owner-led brokerage with no sales team, KPIs or sales targets. We don’t sell, we consult. Deal directly with us, with the time and ongoing attention your business deserves.
We look deeper into your financials and reporting, working with you and your accountant to explain the numbers, identify opportunities and strengthen your position before approaching lenders.
Years in bank and brokerage credit roles give you the luxury of hindsight. We know how lenders assess a business and sharpen the application before it lands, bringing expertise and guidance beyond simply facilitating a low doc loan.
When experience matters, see how we have worked with the people behind the equipment.
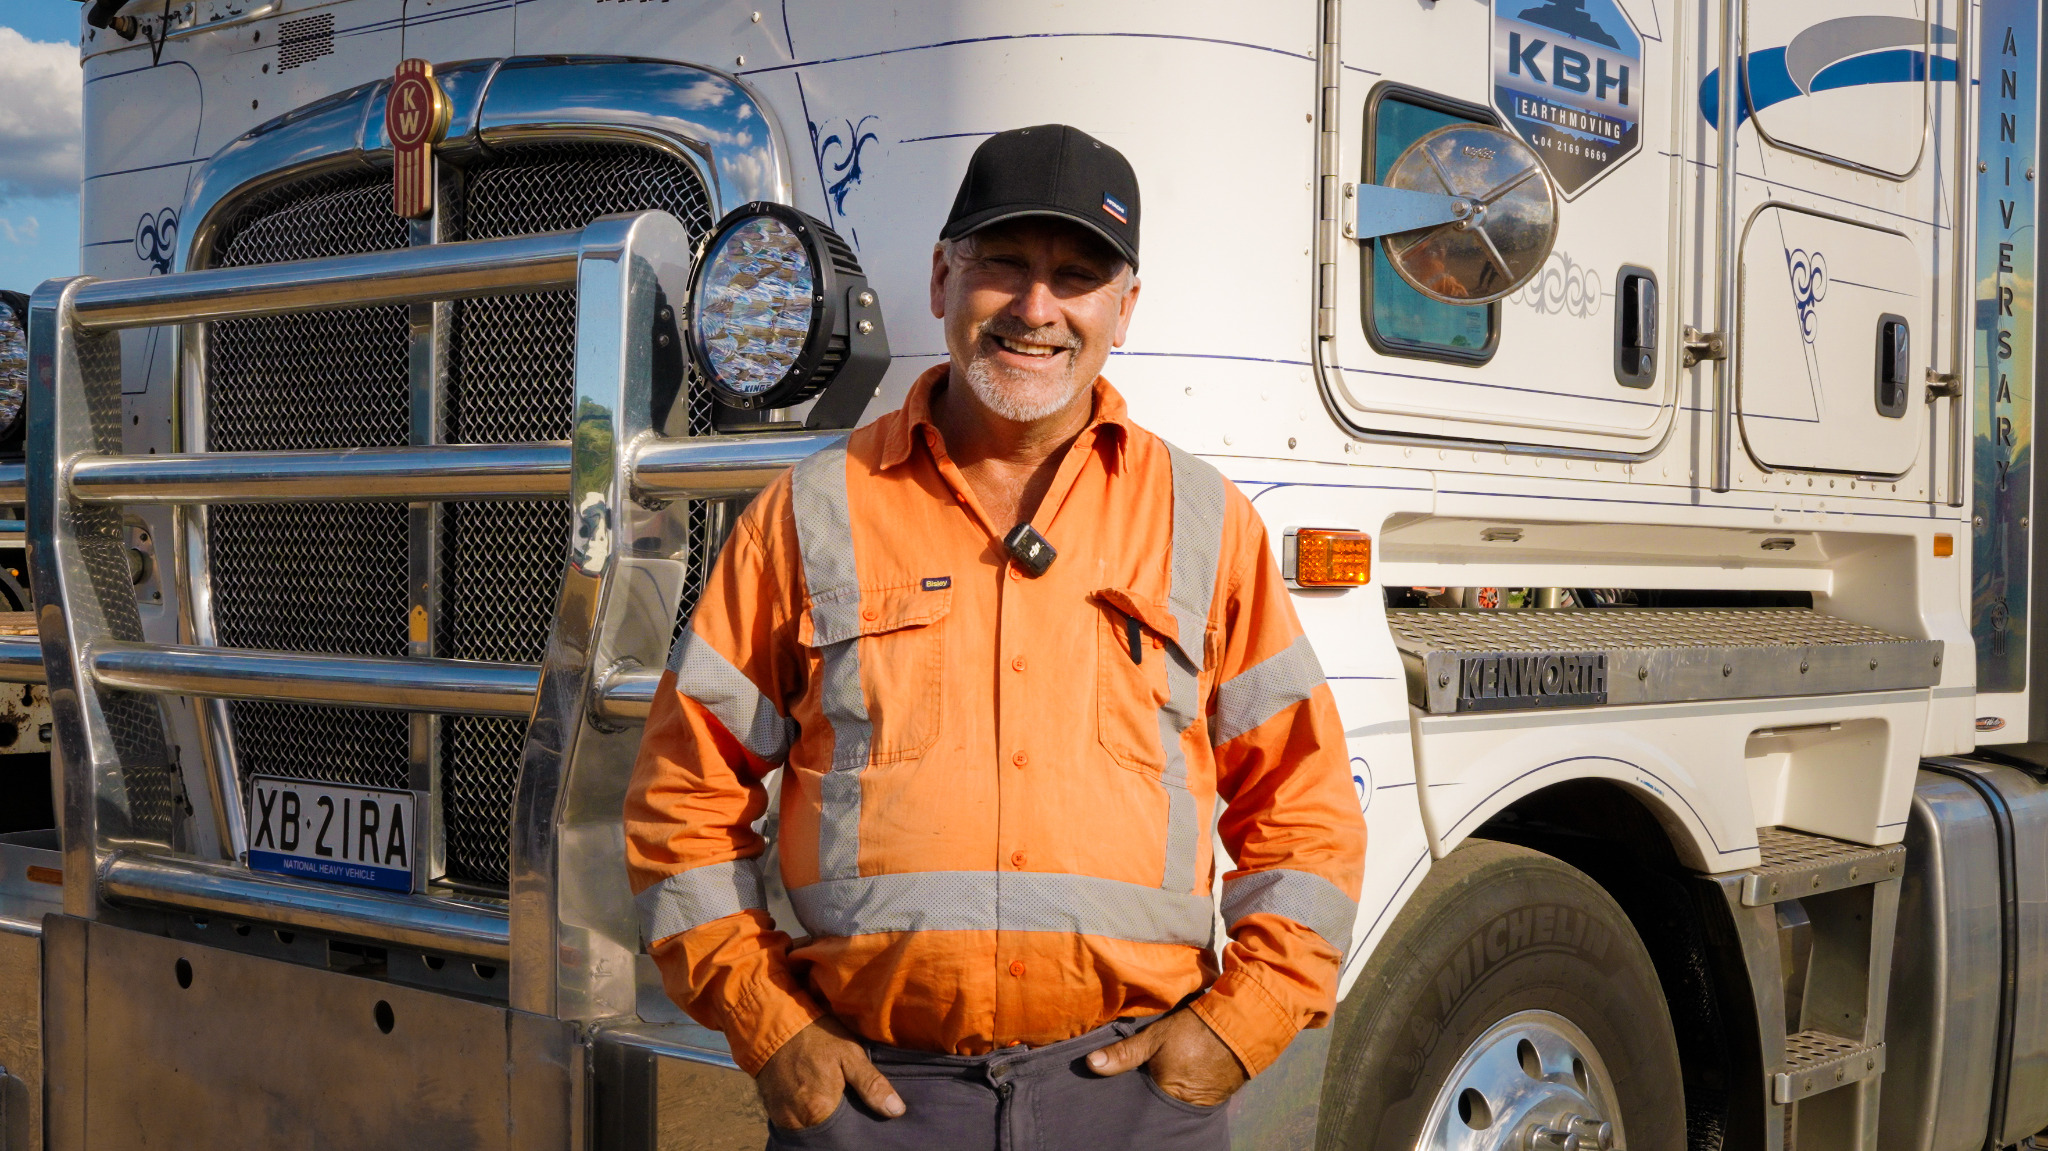
 66+ equipment purchases supporting a growing family business.See full story
 Graders, dozers, utes and a float with major banks.See full story
 Funding an acquisition and a new quarry contract.See full story
 More than 200 civil and mining assets financed over 10 years.See full story
 Seven new Kobelcos to update an ageing fleet.See full story
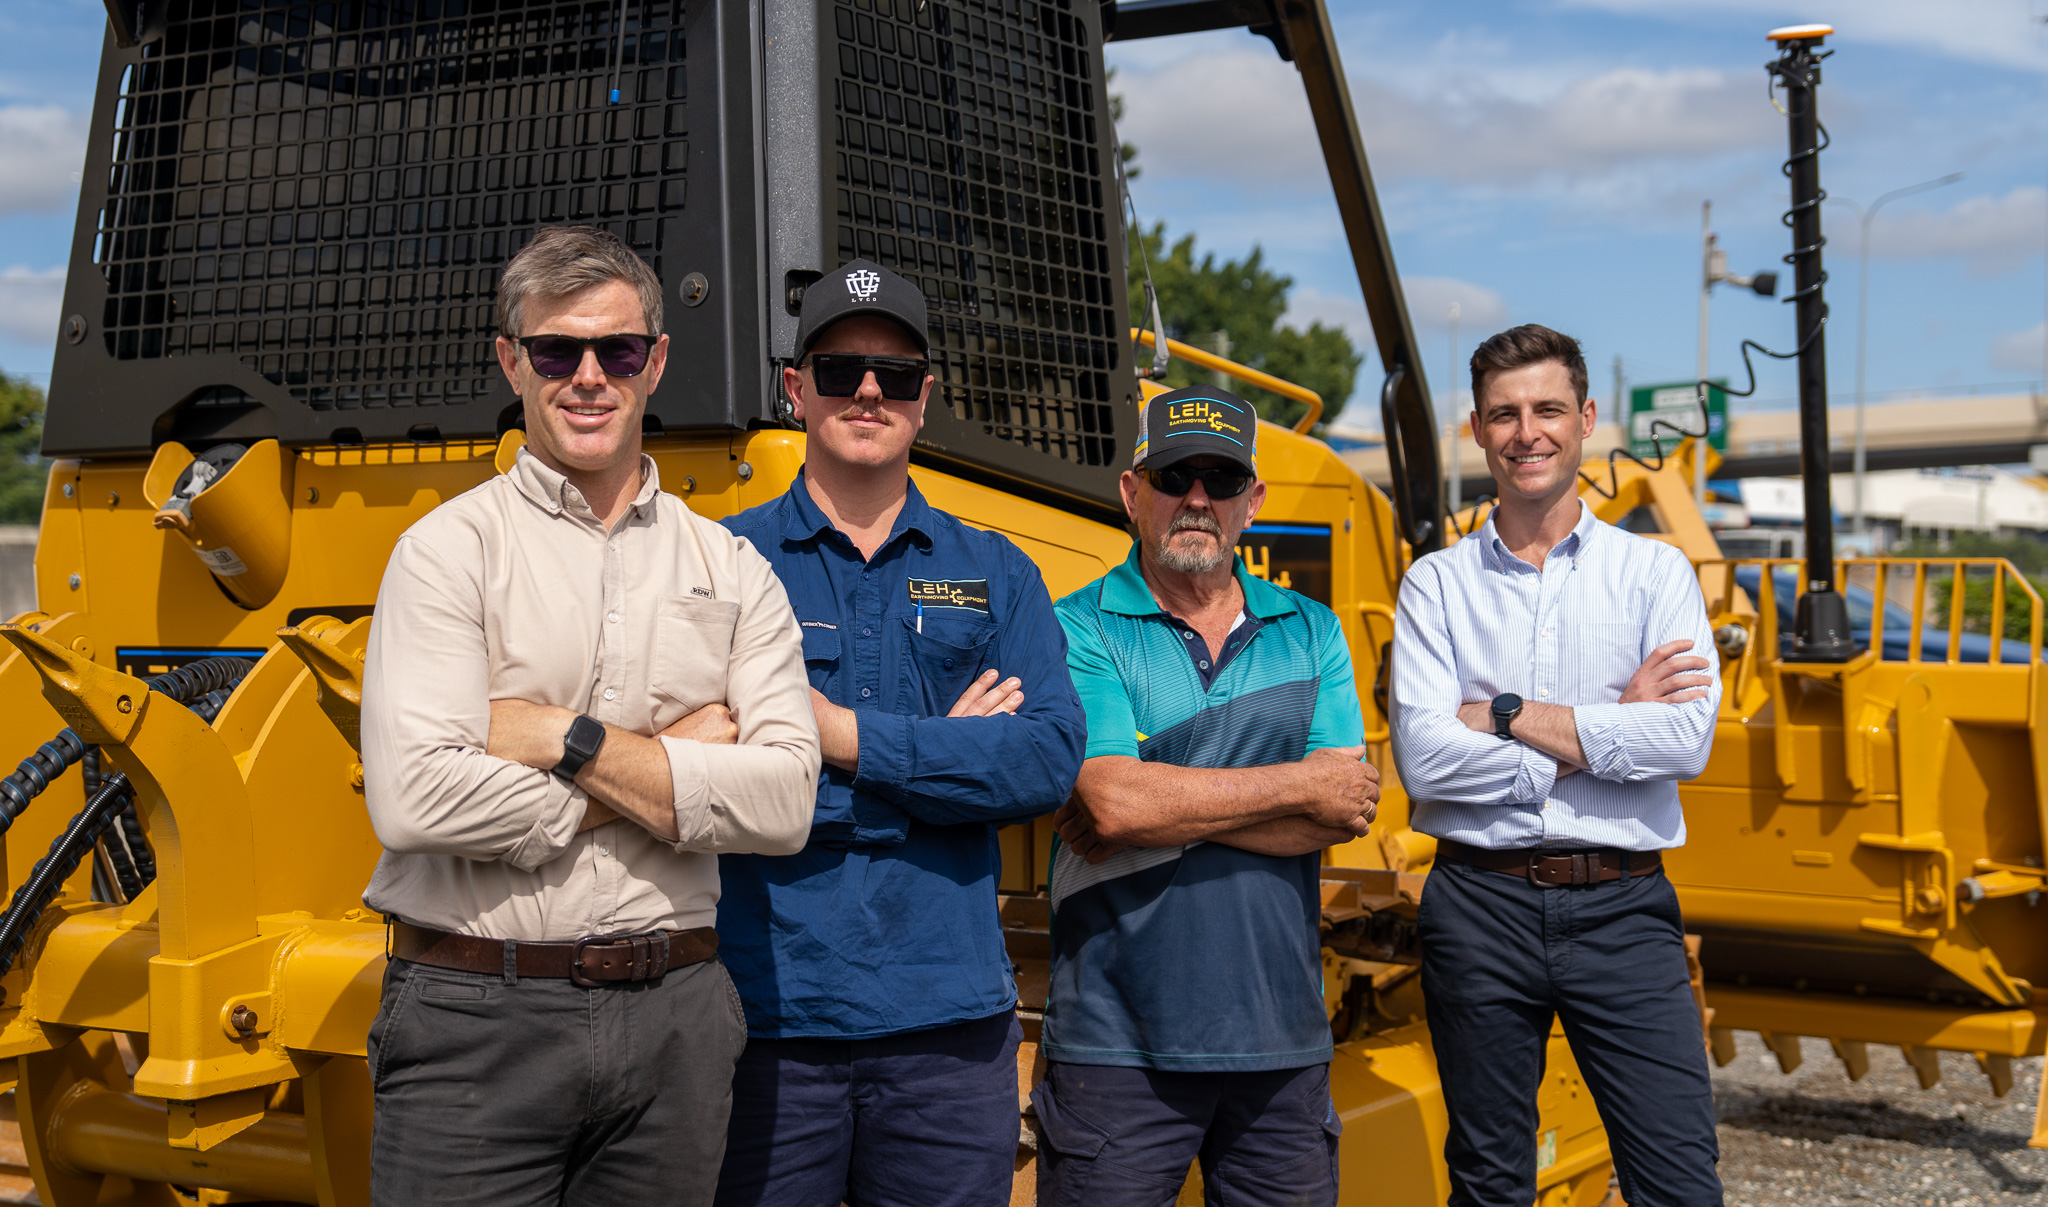
 From start-up to three dozers in three years.See full story
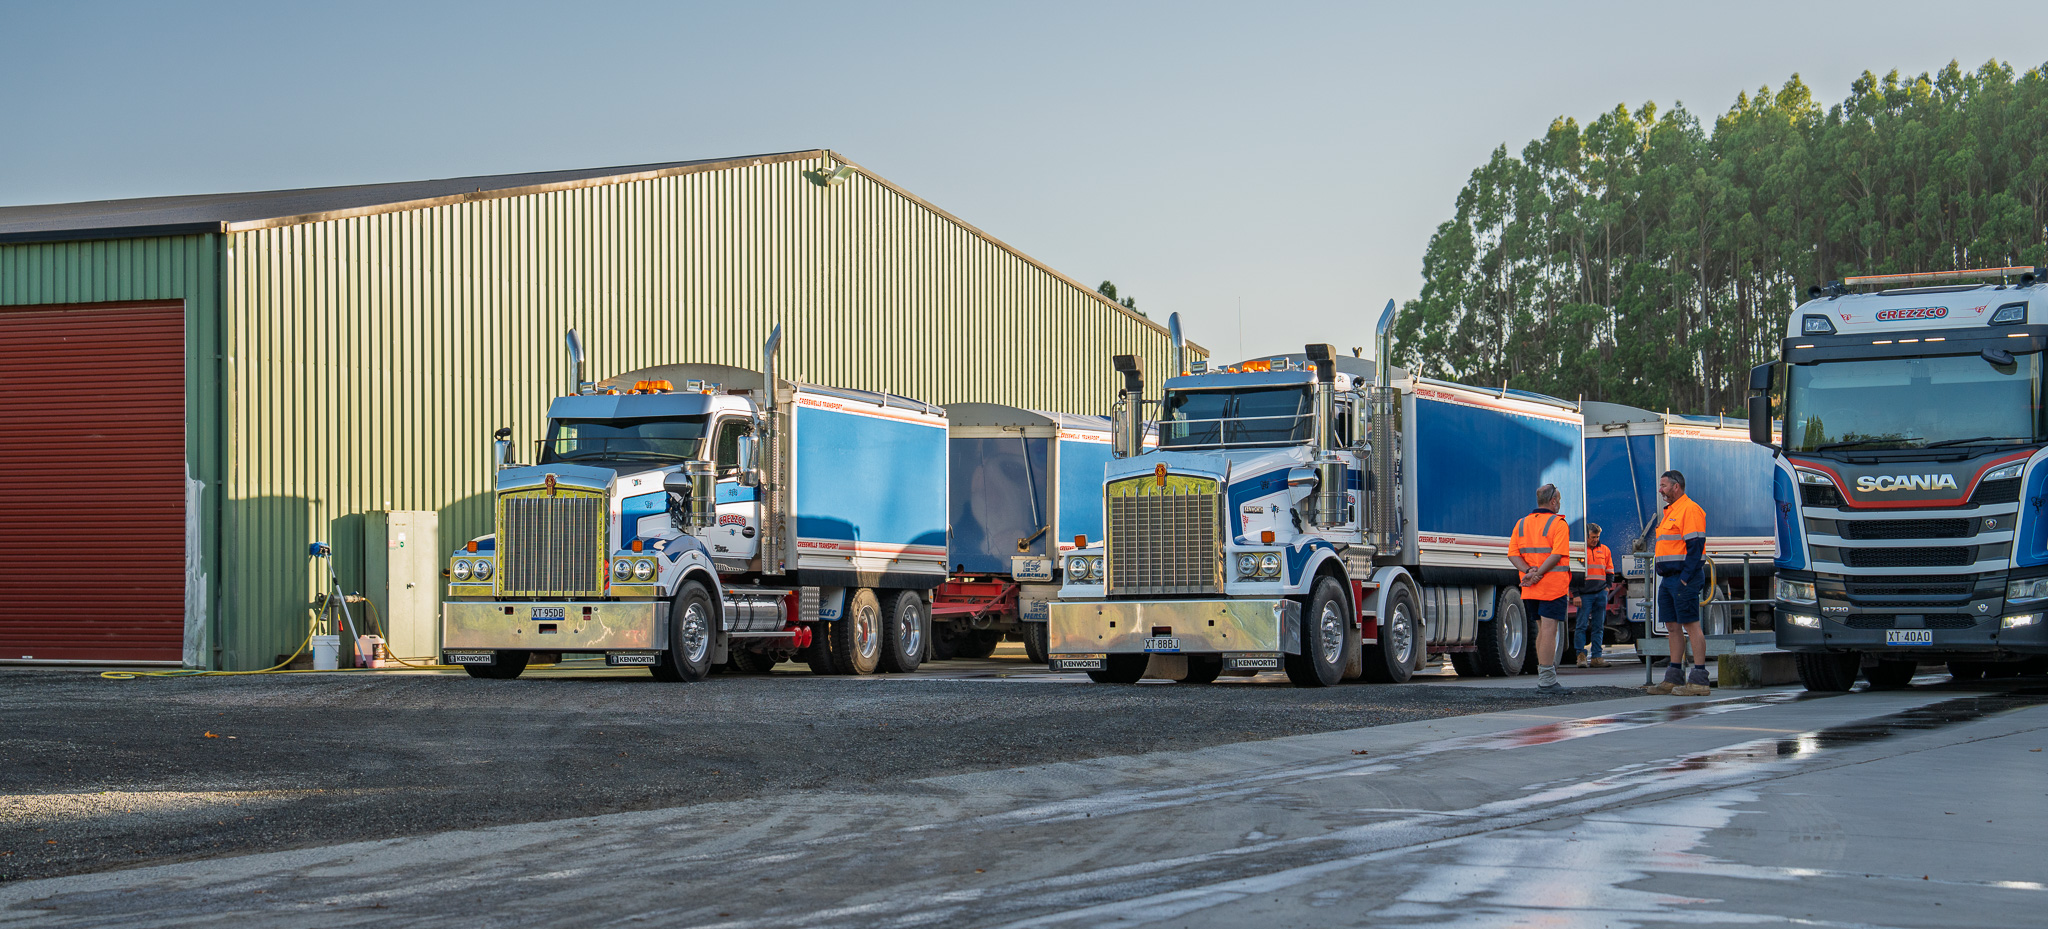
From linehaul to local delivery.
 Prime MoversLinehaul and heavy haulageExplore finance ↗Tippers & TankersCivil haulage and liquid transportExplore finance ↗
 Vac & Pump TrucksVacuum excavation and pumpingExplore finance ↗
 Concreting & AgitatorConcrete delivery and site workExplore finance ↗
 Bulk HandlingGrain, livestock and bulk freightExplore finance ↗
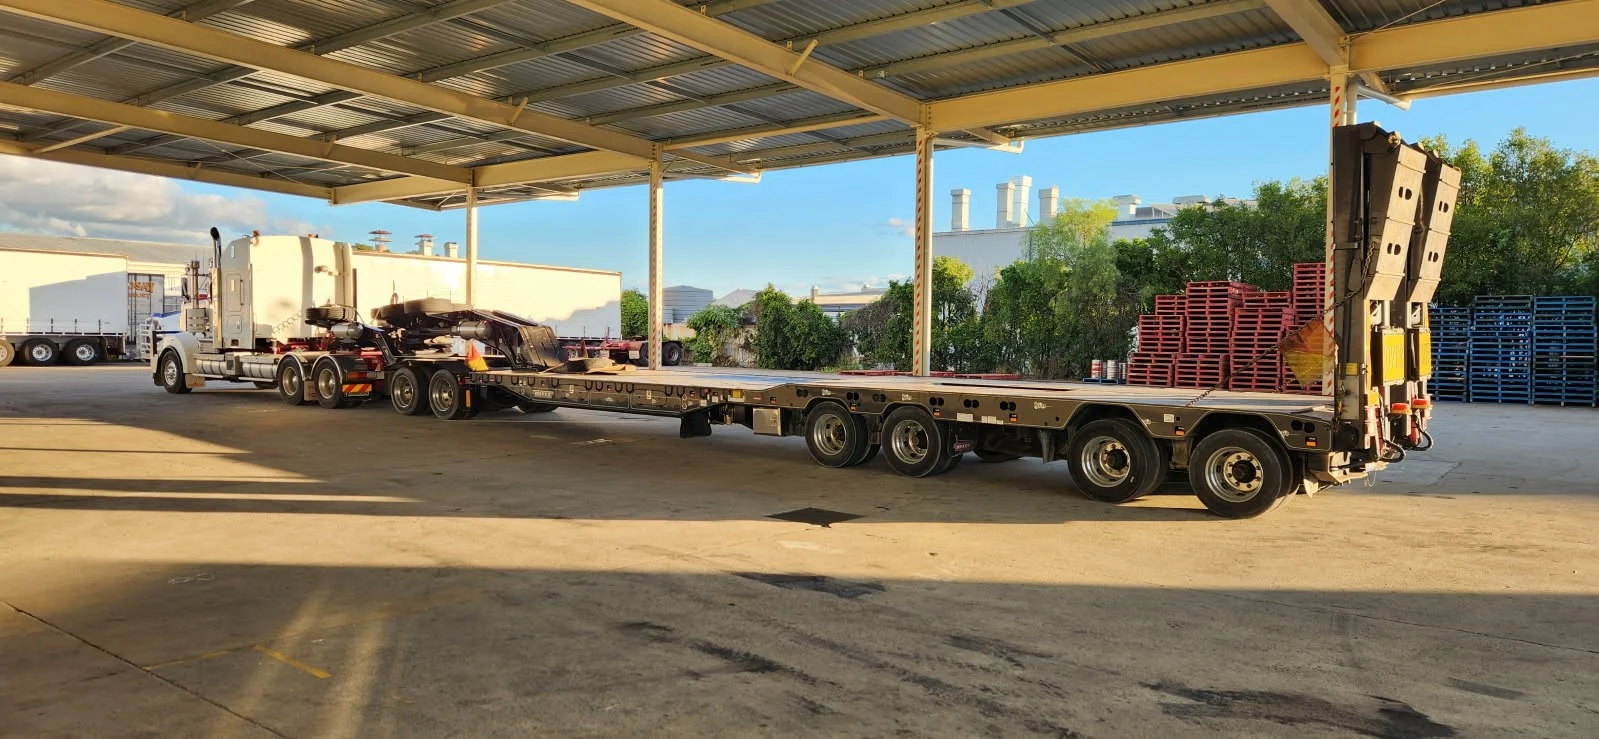
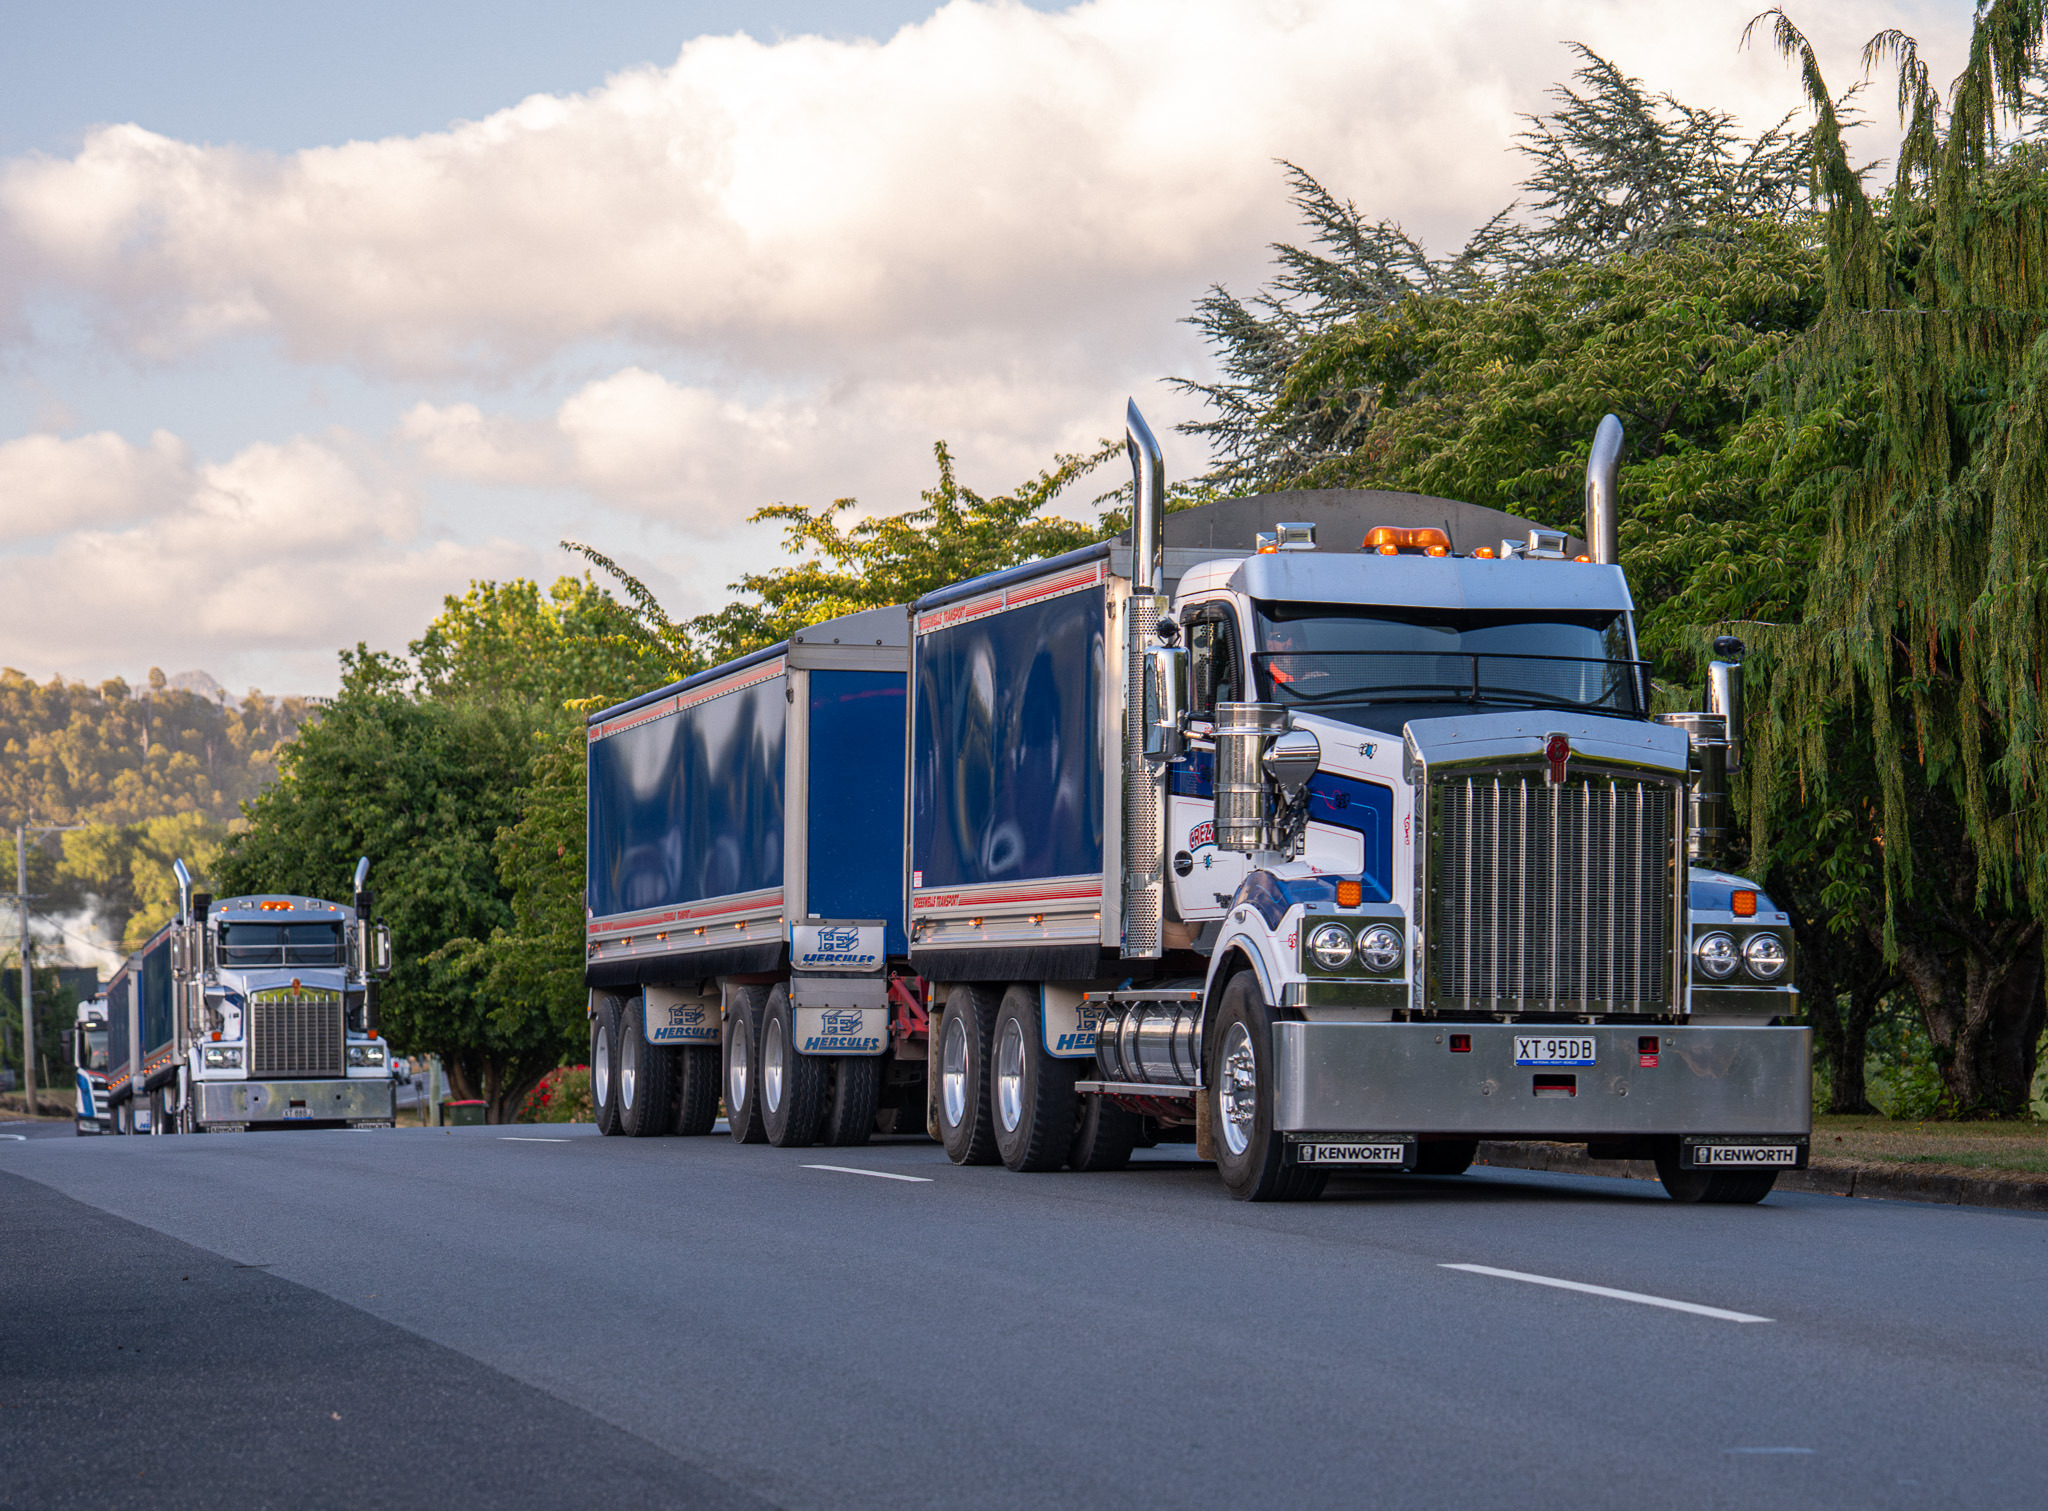 Low Loaders & Tilt TrayEquipment transport and recoveryExplore finance ↗
 Car CarriersVehicle transport and logisticsExplore finance ↗
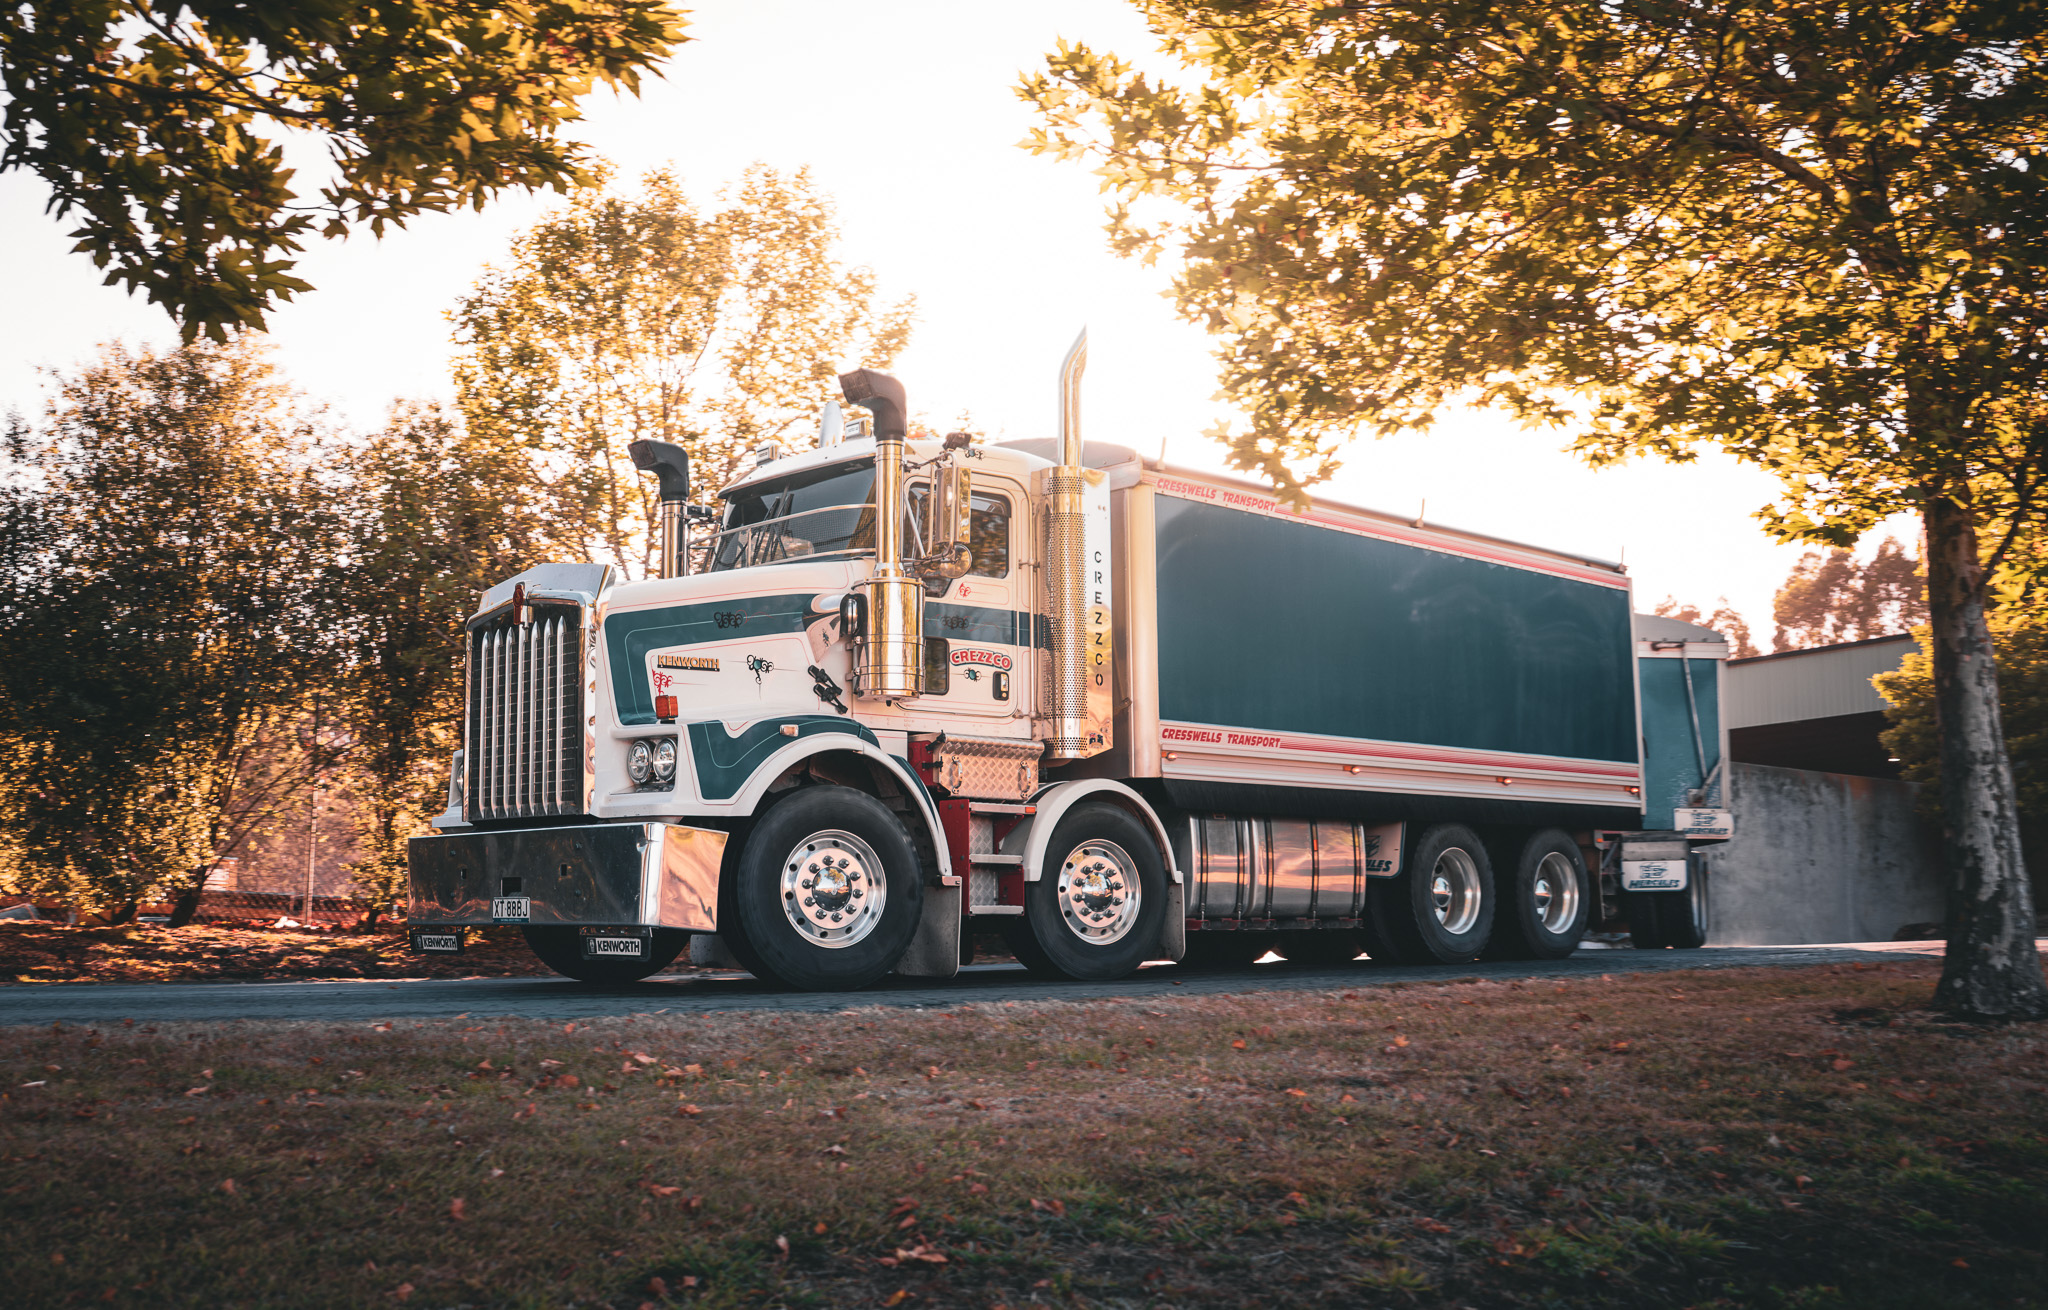 RefrigeratedTemperature-controlled freightExplore finance ↗
Bring us the truck or trailer, the seller and your deadline. We work through the purchase and funding before settlement.
We assess the supplier quote, asset details, fit-out and delivery timing together.
We coordinate ownership checks and the lender’s paperwork, then manage finance through to payment of the seller.
Speak with us before bidding. We assess the funding amount, asset conditions and settlement deadline so you understand your purchasing budget.
We can assess your position before you choose the final truck or trailer and discuss a pre-approval or purchasing budget, subject to lender and asset conditions.
Discuss your purchase ↗Bodies, cranes, refrigeration, tippers, tanks and other work-specific fit-outs can be assessed alongside the truck or trailer. Bring us the full purchase and installation plan.
A truck or trailer to take on contracted work, with repayments considered against the revenue and running costs.
Additional vehicles, trailer combinations and replacement purchases planned around utilisation and contract timing.
A planned funding program across lenders, with visibility to payouts, replacement cycles and capacity for the next move.
Match the funding to your contracts, replacement schedule and cash flow, with a clear view of the next truck as well as this one.
Using your last two years of financials and recent reporting, we prepare a thorough application for major banks and specialist vehicle and equipment finance lenders. We explain the business, the purchase and the numbers behind it.
Available when an urgent approval or settlement leaves little time for a full financial submission. We use low doc options selectively and preserve that capacity for the moments you need it, subject to lender criteria.
An annually reviewed ceiling for individual truck and trailer acquisitions throughout the year, typically from $1 million to $50 million. For growing fleets, an agreed limit brings clearer visibility to funding capacity. Each purchase remains subject to the facility’s terms and lender requirements.
Debtor finance, overdrafts, term loans and other commercial facilities can support the business around the fleet. We consider cash flow, existing security and fleet commitments together, then work with suitable business lenders and bankers.
Know what every vehicle owes and what can be traded towards new vehicles. We map payouts, trade values and replacement plans, including assets with existing debt, and coordinate supplier timing so the funding and fleet rollout work together.
Rapid growth can leave debt scattered across lenders or facilities that no longer suit. We assess restructuring with one or several lenders to release capacity where possible, improve the debt arrangement and reopen funding lines, accounting for payouts, costs and available security. Adjusting the term and repayment structure may also soften monthly repayments and ease cash flow pressure; a longer term can increase the total interest paid.
A recent outright purchase may be eligible for sale and buyback finance to return funds to the business. We assess ownership, purchase timing, value and lender criteria before recommending an approach.
James and Dan have worked in bank credit and broking. We review the financials, existing debt and supporting information before approaching lenders, and work with you and your advisers to explain material entries or changes clearly. A well prepared application gives lenders a fairer picture of the business.
We give you a direct view of the funding opportunities we see, where the challenges sit and how confident we are in the proposed approach. We map out fleet debt, lender exposures and available capacity between all lenders, so you get complete visibility to how far you can go on your fleet expansion.
The lowest priced lender for today’s machine may be the lender you need for a much larger facility tomorrow. We consider where each asset belongs across the available banks and specialist lenders, protecting room for future purchases where we can.
Where the business and lender criteria support it, we can pursue an annual trucks and trailers finance limit. It gives you an agreed funding framework for eligible purchases through the year, with each drawdown assessed and documented under the lender’s terms.
As your needs grow, we can introduce and work alongside suitable business or corporate bankers. That can open conversations about broader facilities, including working capital, trade funding and commercial property finance, while keeping the trucks and trailers strategy connected.
Unencumbered trucks and trailers, or assets nearing the end of their finance term, may offer an opportunity to release equity in times of a cashflow pinch. We can assess the trucks and trailers, valuation and lender options to see whether refinancing could return useful cash to the business.
Business owners need someone they can speak with candidly. We bring an independent perspective shaped by years of working with operators across the country, keep your information confidential and stay involved as your plans change.
One truck or a whole working fleet. Let’s map the funding and replacement timing around the work ahead.
Let’s grow togetherCredit expertise, direct relationships and a wider choice of lenders, backed by recognised work in commercial finance.
Commercial Finance Awards
Finalist · 2026
Australian Broking Awards
Finalist 2026
CAFBA
Finalist 2023
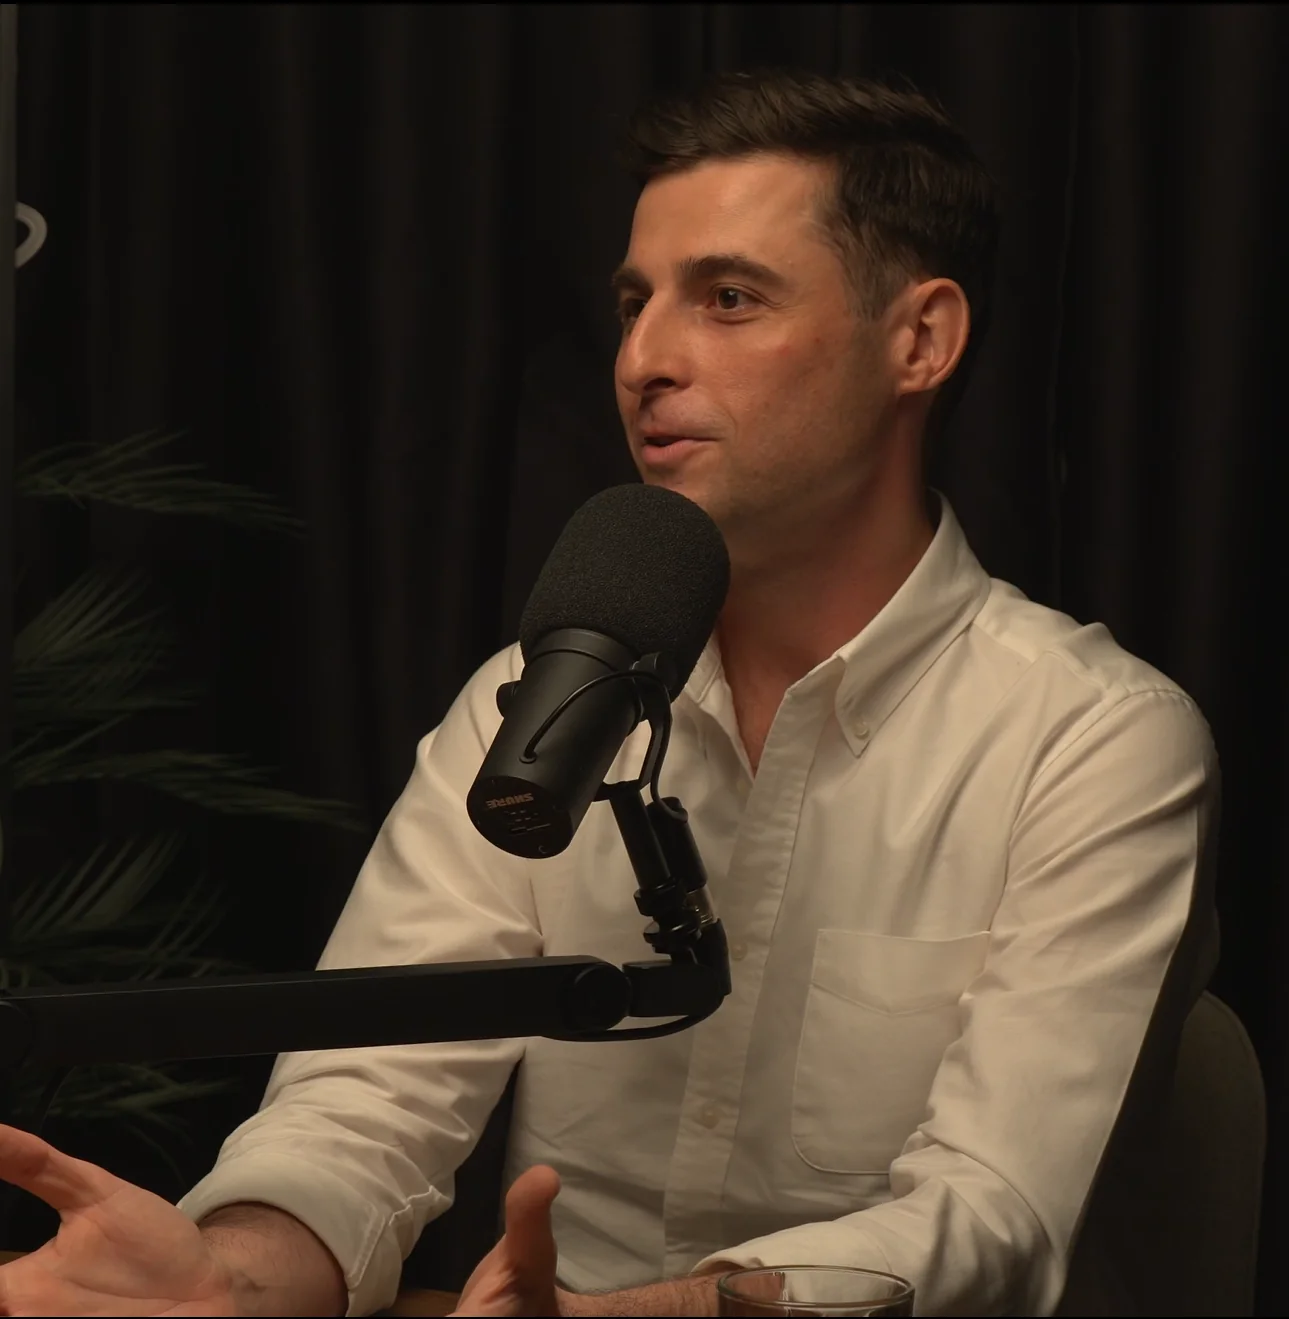
James Allan on commercial finance
Featured guest
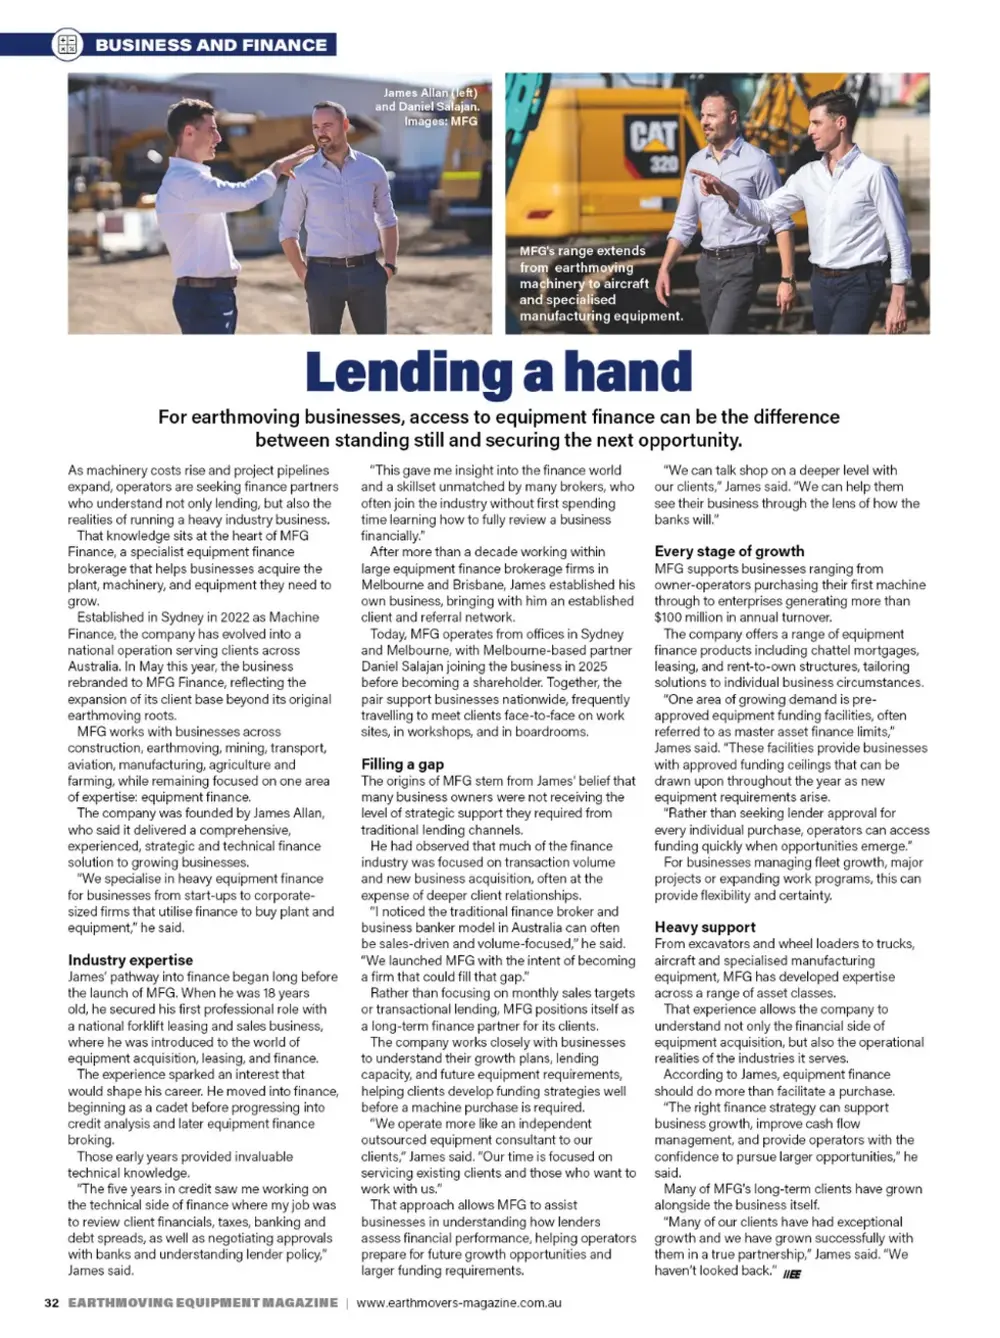
“Lending a hand”
Featured article
MFG is directly accredited with all major banks, alongside an extensive panel of non-bank, specialist and private lenders.
 CAFBA 101556
 FBAA M-359967
 AFCA 89354
Panel shown is indicative and subject to lender accreditation, credit policy and transaction requirements.
See how term, rate, balloon and payment timing change the monthly commitment.
Illustration only. Assumes a fixed nominal annual rate divided into monthly periods, level monthly payments and a balloon due at the end. Excludes fees, taxes and insurance. In advance means the first repayment is made at the start. This is not a lender quote.
Talk through the purchase →
You deal directly with James or Dan. We have worked inside credit, so we look at how a lender will assess the business as well as the equipment. The aim is to fund this purchase without losing sight of the next one.
We do not charge an upfront brokerage establishment fee. We are paid by lenders when a transaction settles. If a lender has its own fees, we will show you those in the proposed terms before you commit.
We work with prime movers, rigids, tippers, specialist trucks and trailers across linehaul, metro freight, heavy haulage, civil work and logistics. New or used, single vehicles and whole fleets are all worth a conversation.
Often, yes. Age alone does not decide it. The lender will also look at the equipment type, condition, hours or kilometres, value and how the business will use it. Tell us what you are considering before you lock in a short settlement date.
Those purchases can be financed, but the paperwork and timing matter. We may need to check ownership, identification, condition, value and how payment will be made. Auction deadlines in particular can be tight, so involve us early.
It depends on the business, the equipment, the lender and whether the information is ready. A straightforward repeat purchase may move quickly; a larger or more involved transaction needs more work. Give us the deadline and we will tell you what is realistic.
There is no one rate that fits every purchase. The lender, business profile, equipment, deposit, term and repayment structure all affect the offer. We compare the whole deal, including fees, balloon and future borrowing capacity, rather than quoting a headline rate in isolation.
Possibly. Some lenders offer reduced-documentation options for eligible businesses. We will look at whether that route actually makes sense, because a full assessment can sometimes lead to a better structure or more room for the next purchase.
We can look at the position and tell you honestly where it stands. Trading history, contracts, cash flow, deposit and the reason for any credit issue all matter. There is no blanket yes or no, and we will not promise an approval we cannot support.
Not always. It depends on the business, equipment and lender. We will weigh up the benefit of keeping cash in the business against the cost and terms of borrowing more.
That depends on the purchase, the business’s ability to repay, existing commitments and the lender’s policy. The useful question is what level of debt and repayment suits the work the equipment will do, not just the maximum someone will approve.
It is an agreed amount left to pay at the end of the term. It can reduce regular repayments, but the final amount still needs a plan. We look at likely resale value, replacement timing and the payout before recommending one.
Yes. If you are building or replacing a fleet, we can map the purchases, allocate them across lenders and consider an equipment finance limit where the business qualifies. That can help preserve capacity for what comes next.
Sometimes. Depending on the lender and the business, we may be able to assess a funding limit or obtain an indication before the final asset is known. The lender will still need to approve the actual equipment and seller before settlement.
We can review it. The existing payout, current value, remaining term and reason for refinancing will determine whether there is a worthwhile option. We will also consider how it affects your broader lender capacity.
We need the trade value and any payout on the existing loan. The equity or shortfall becomes part of the new purchase calculation, so it is best to work through both sides before you agree to the deal.
Potentially. Imported purchases need more planning around supplier terms, currency, shipping, identification and when the lender can take security. Bring us in before a deposit or payment milestone is due.
That depends on the lender and product. Some facilities allow flexibility; others may have early payout costs or a different interest calculation. If early repayment is likely, tell us at the start so we can factor it into the structure.
A chattel mortgage is common for business equipment, but it is not the only structure. Depending on the purchase, we may also consider a lease or another facility. We will explain who owns the equipment, the repayment and any final amount before you choose.
Sometimes. We need to be clear about which entity is buying the equipment, which one will use it and where the income sits. We can map the group and approach lenders that are comfortable with that structure.
Of course. Send the full terms, not just the rate. We will look at fees, balloon, security, flexibility and what the deal might mean for the next purchase. If your existing offer is the right one, we will tell you.
Tell us what you are buying, the price, seller and timing, plus a little about the business and its existing finance. James or Dan will talk through the purchase with you and outline the information needed for the right lenders.
Buying your first machine? Replacing a fleet? Start with the situation as it is. We’ll talk through the assets, the timing and what the next decision means for your business.
Replacing equipment or planning the next purchase? Tell us what you have in mind.