The first productive asset.
Funding for tractors, harvesters, forestry machines and supporting equipment, considered against the work, running costs and repayment capacity.
 Get started
Finance for farm and forestry machinery that earns its keep in the field.
Explore what we finance ↓Tell us about the next purchase you have in mind.
"*" indicates required fields
We work with business owners investing in tractors, harvesters, forestry machines and supporting equipment. From an individual purchase to an established operation planning its next stage, we consider seasonal income, utilisation and replacement timing alongside the business financials and existing debt.
These are typical clients, not a fixed rule. If your business provides a related service, talk to us about the equipment, its work and the purchase timing. New and used serial numbered assets, dealer purchases, eligible private sales, auctions and imports can all be assessed.
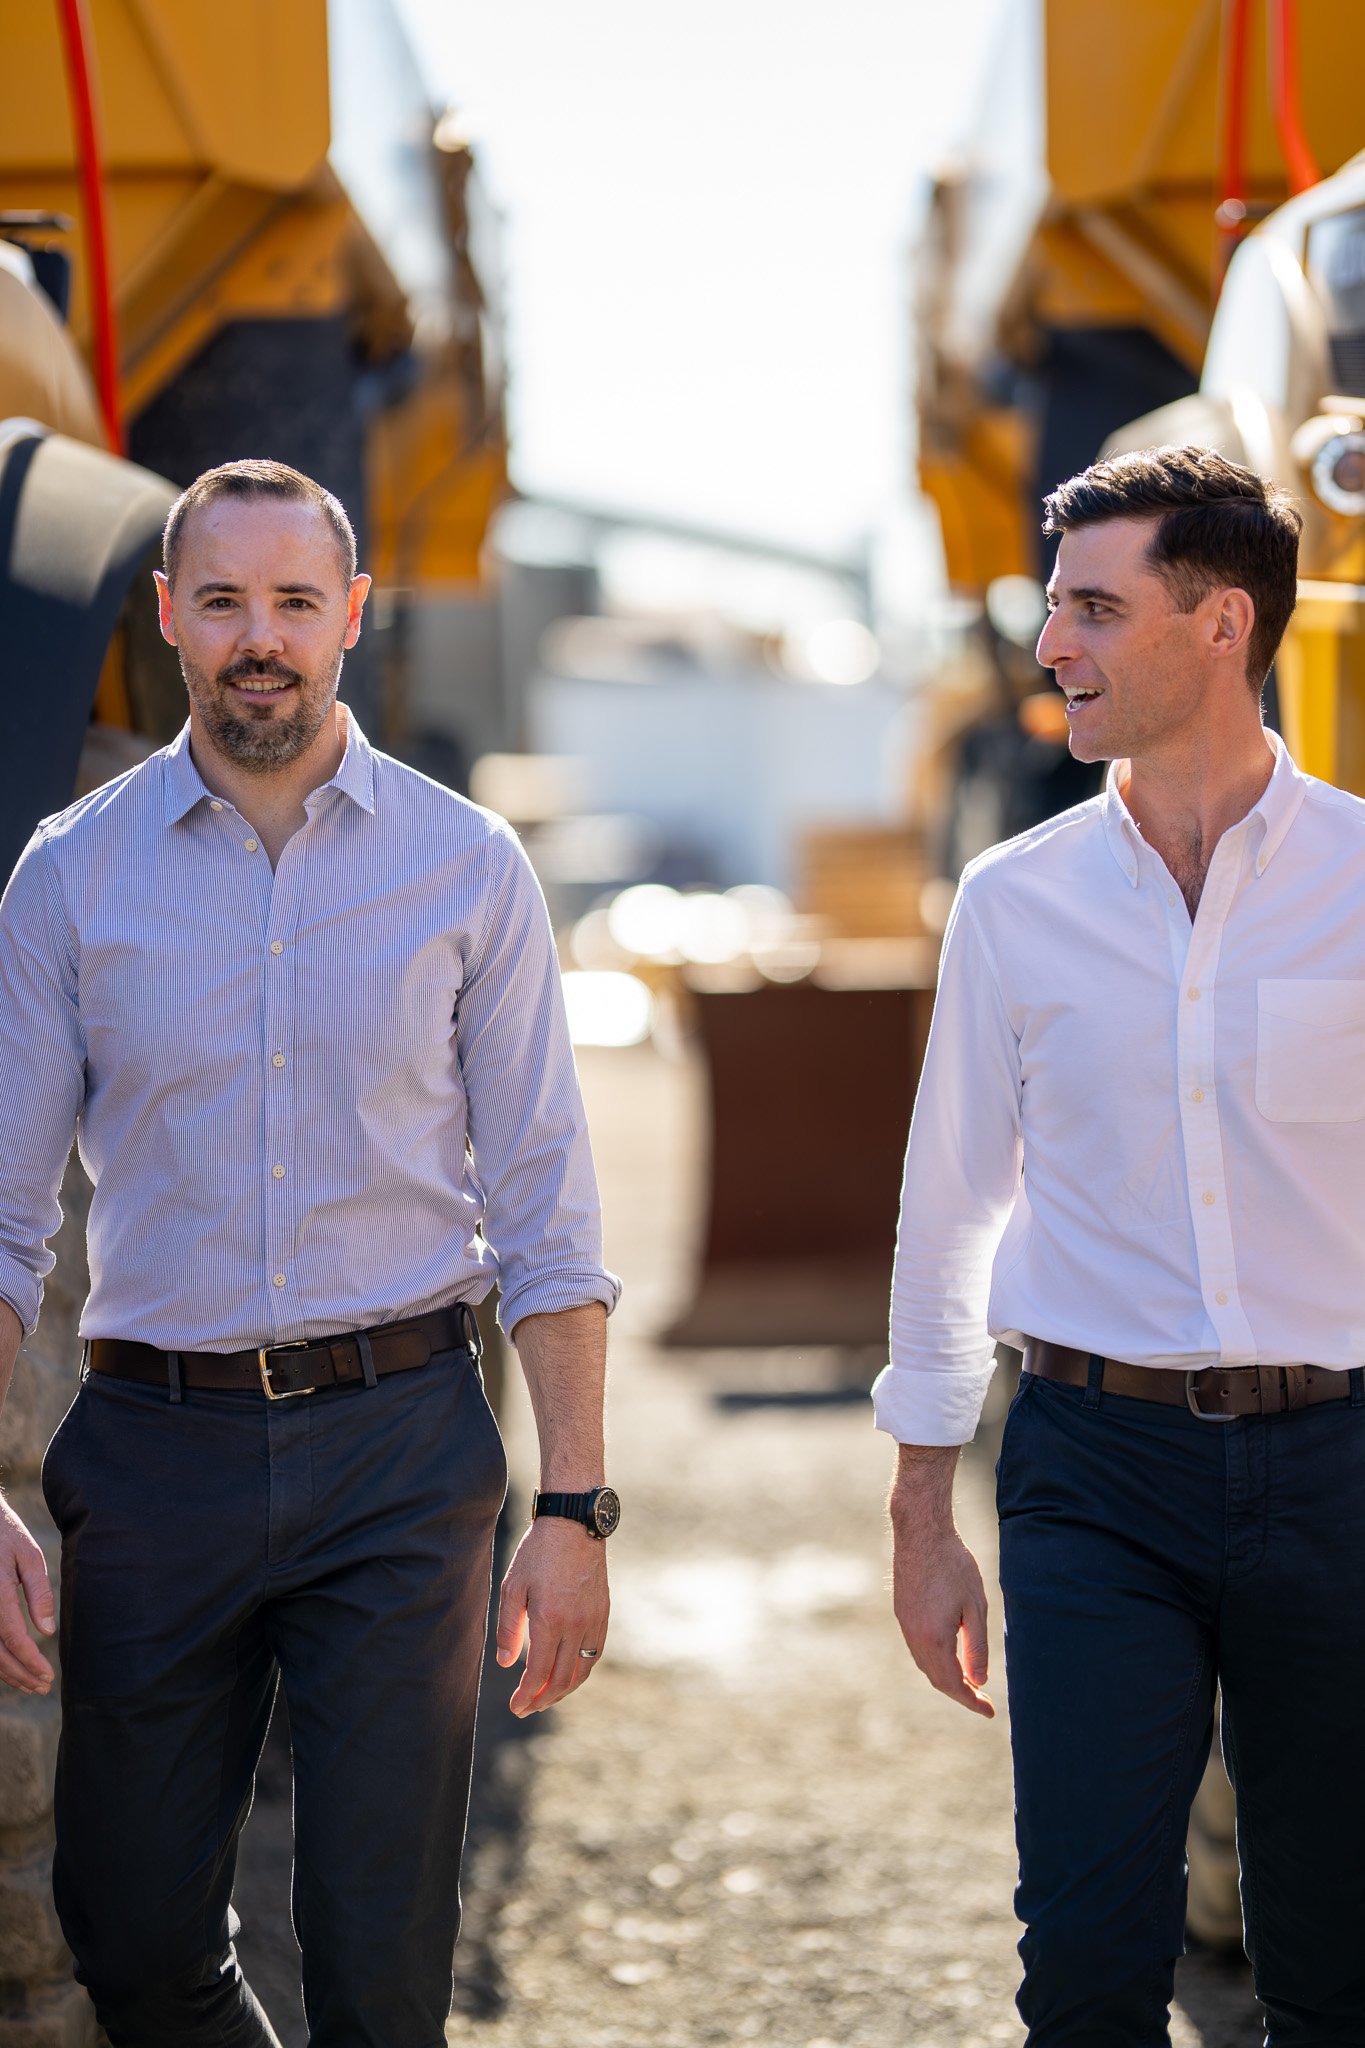
Deal directly with James Allan and Daniel Salajan, with 35 years of combined experience across bank credit and broking.
An owner-led brokerage with no sales team, KPIs or sales targets. We don’t sell, we consult. Deal directly with us, with the time and ongoing attention your business deserves.
We look deeper into your financials and reporting, working with you and your accountant to explain the numbers, identify opportunities and strengthen your position before approaching lenders.
Years in bank and brokerage credit roles give you the luxury of hindsight. We know how lenders assess a business and sharpen the application before it lands, bringing expertise and guidance beyond simply facilitating a low doc loan.
These stories show our wider commercial finance work, including fleet growth, replacements and business acquisitions.
 A considered funding plan behind 66+ equipment purchases.See full story
 Funding an acquisition and a new quarry contract.See full story
 More than 200 civil and mining assets financed over 10 years.See full story
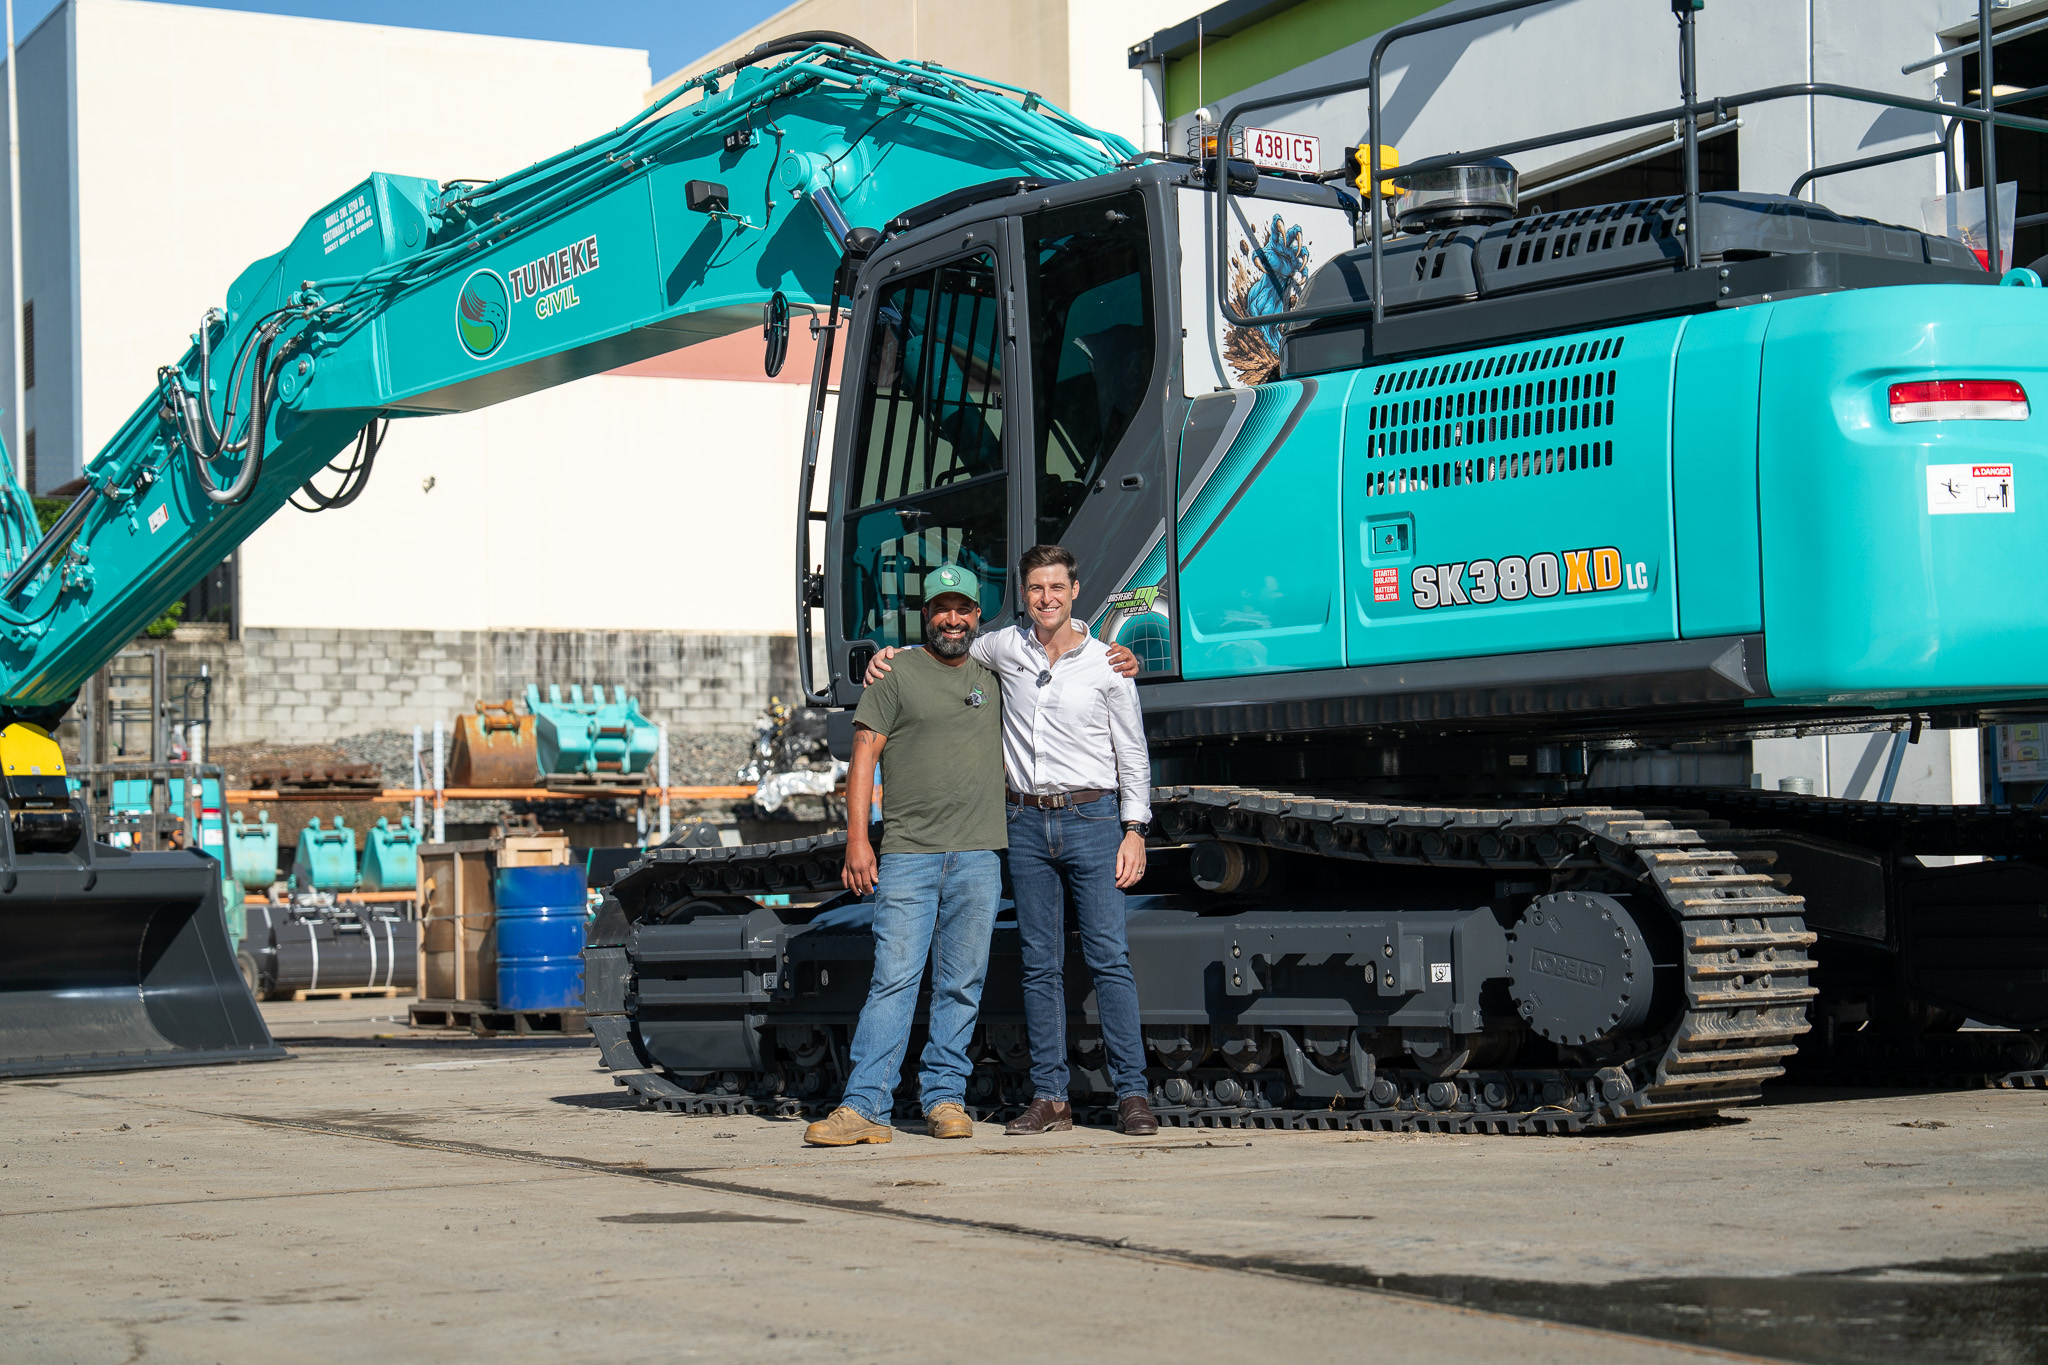
 Seven new Kobelcos to update an ageing fleet.See full story
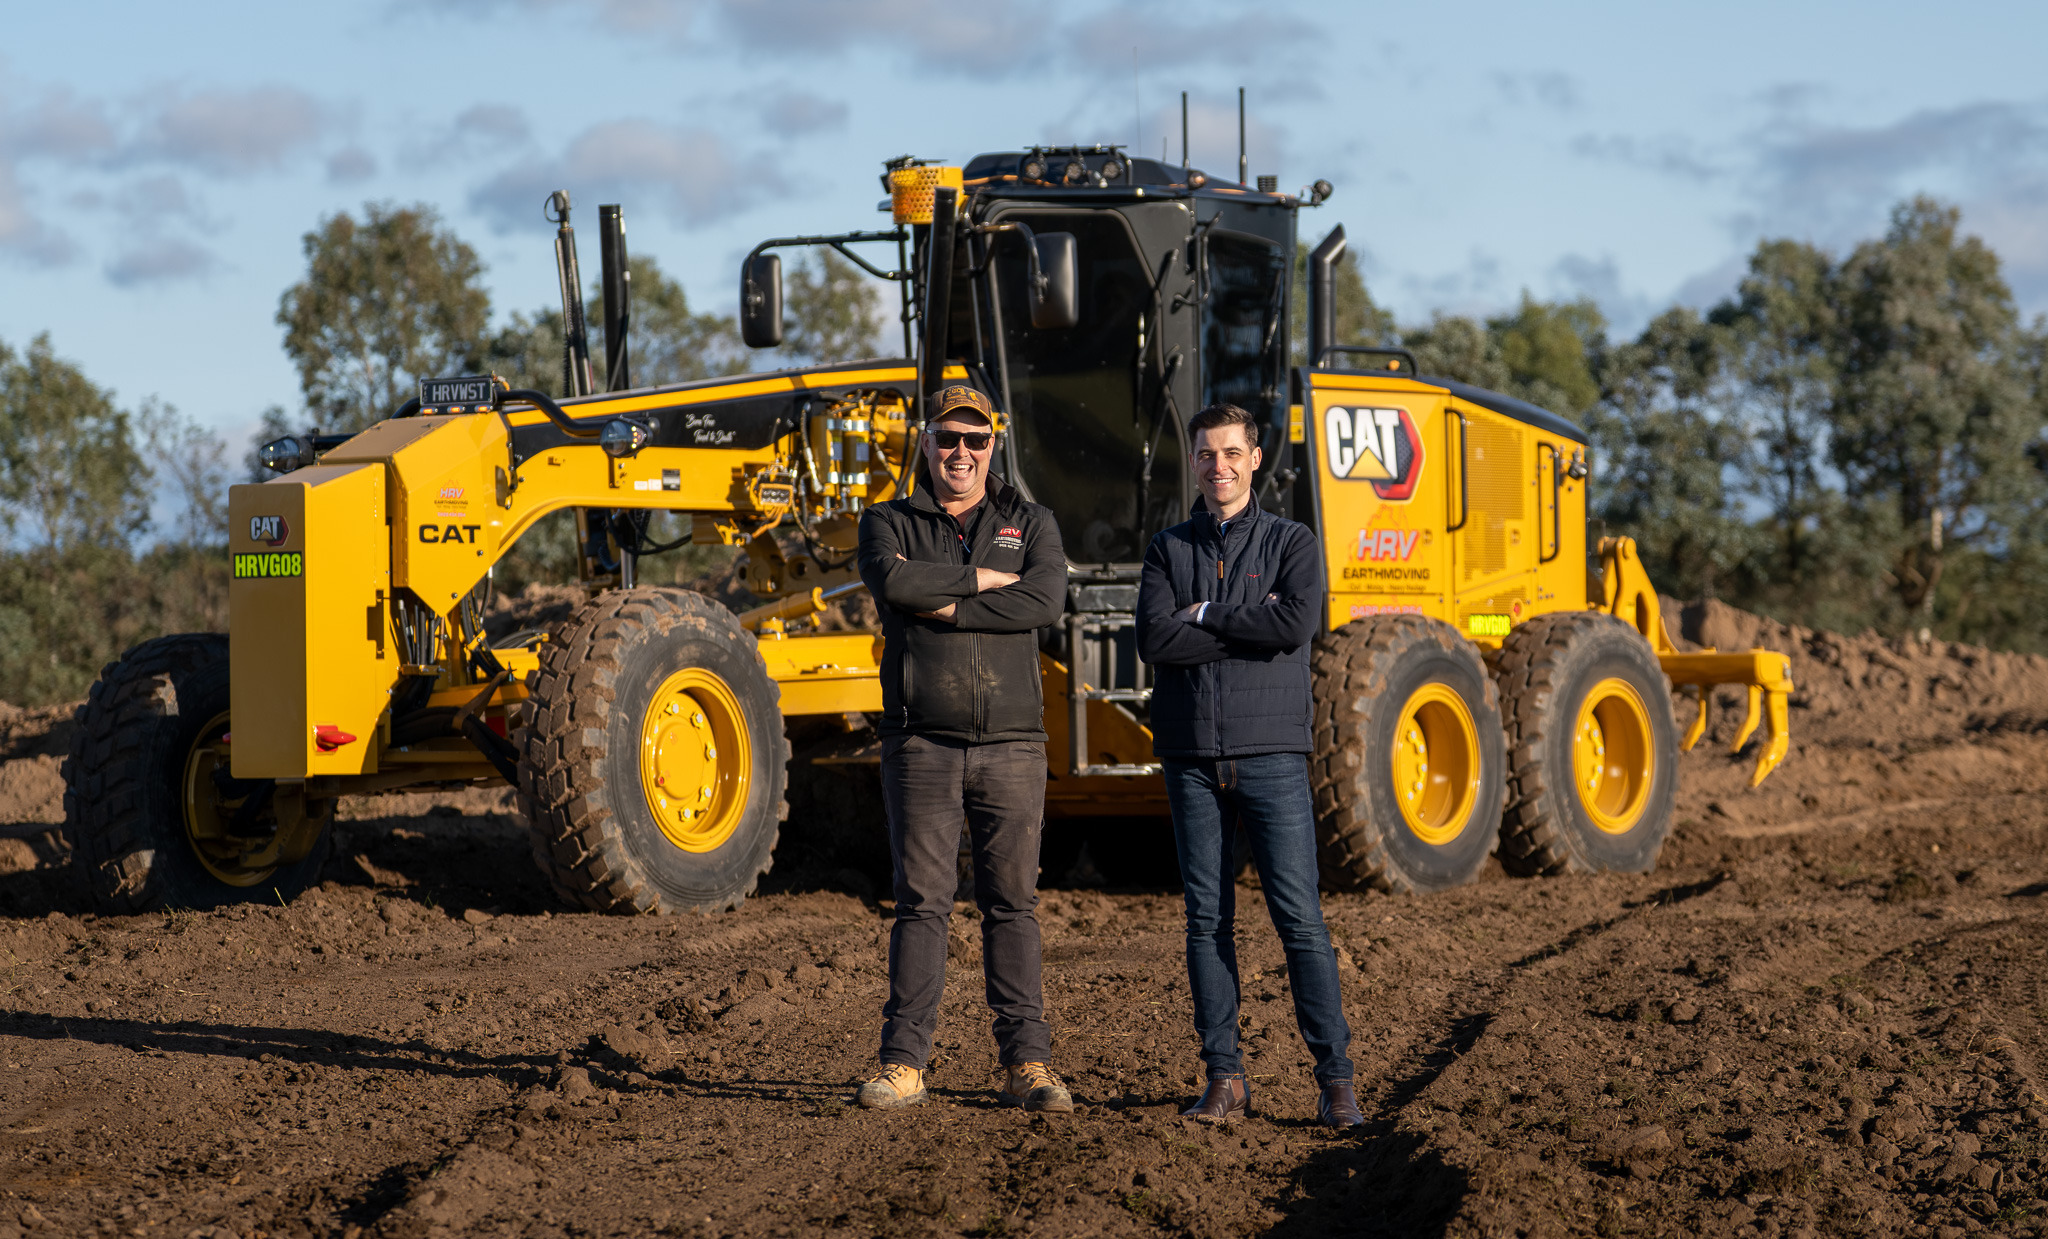
 Graders, dozers, utes and a float with major banks.See full story
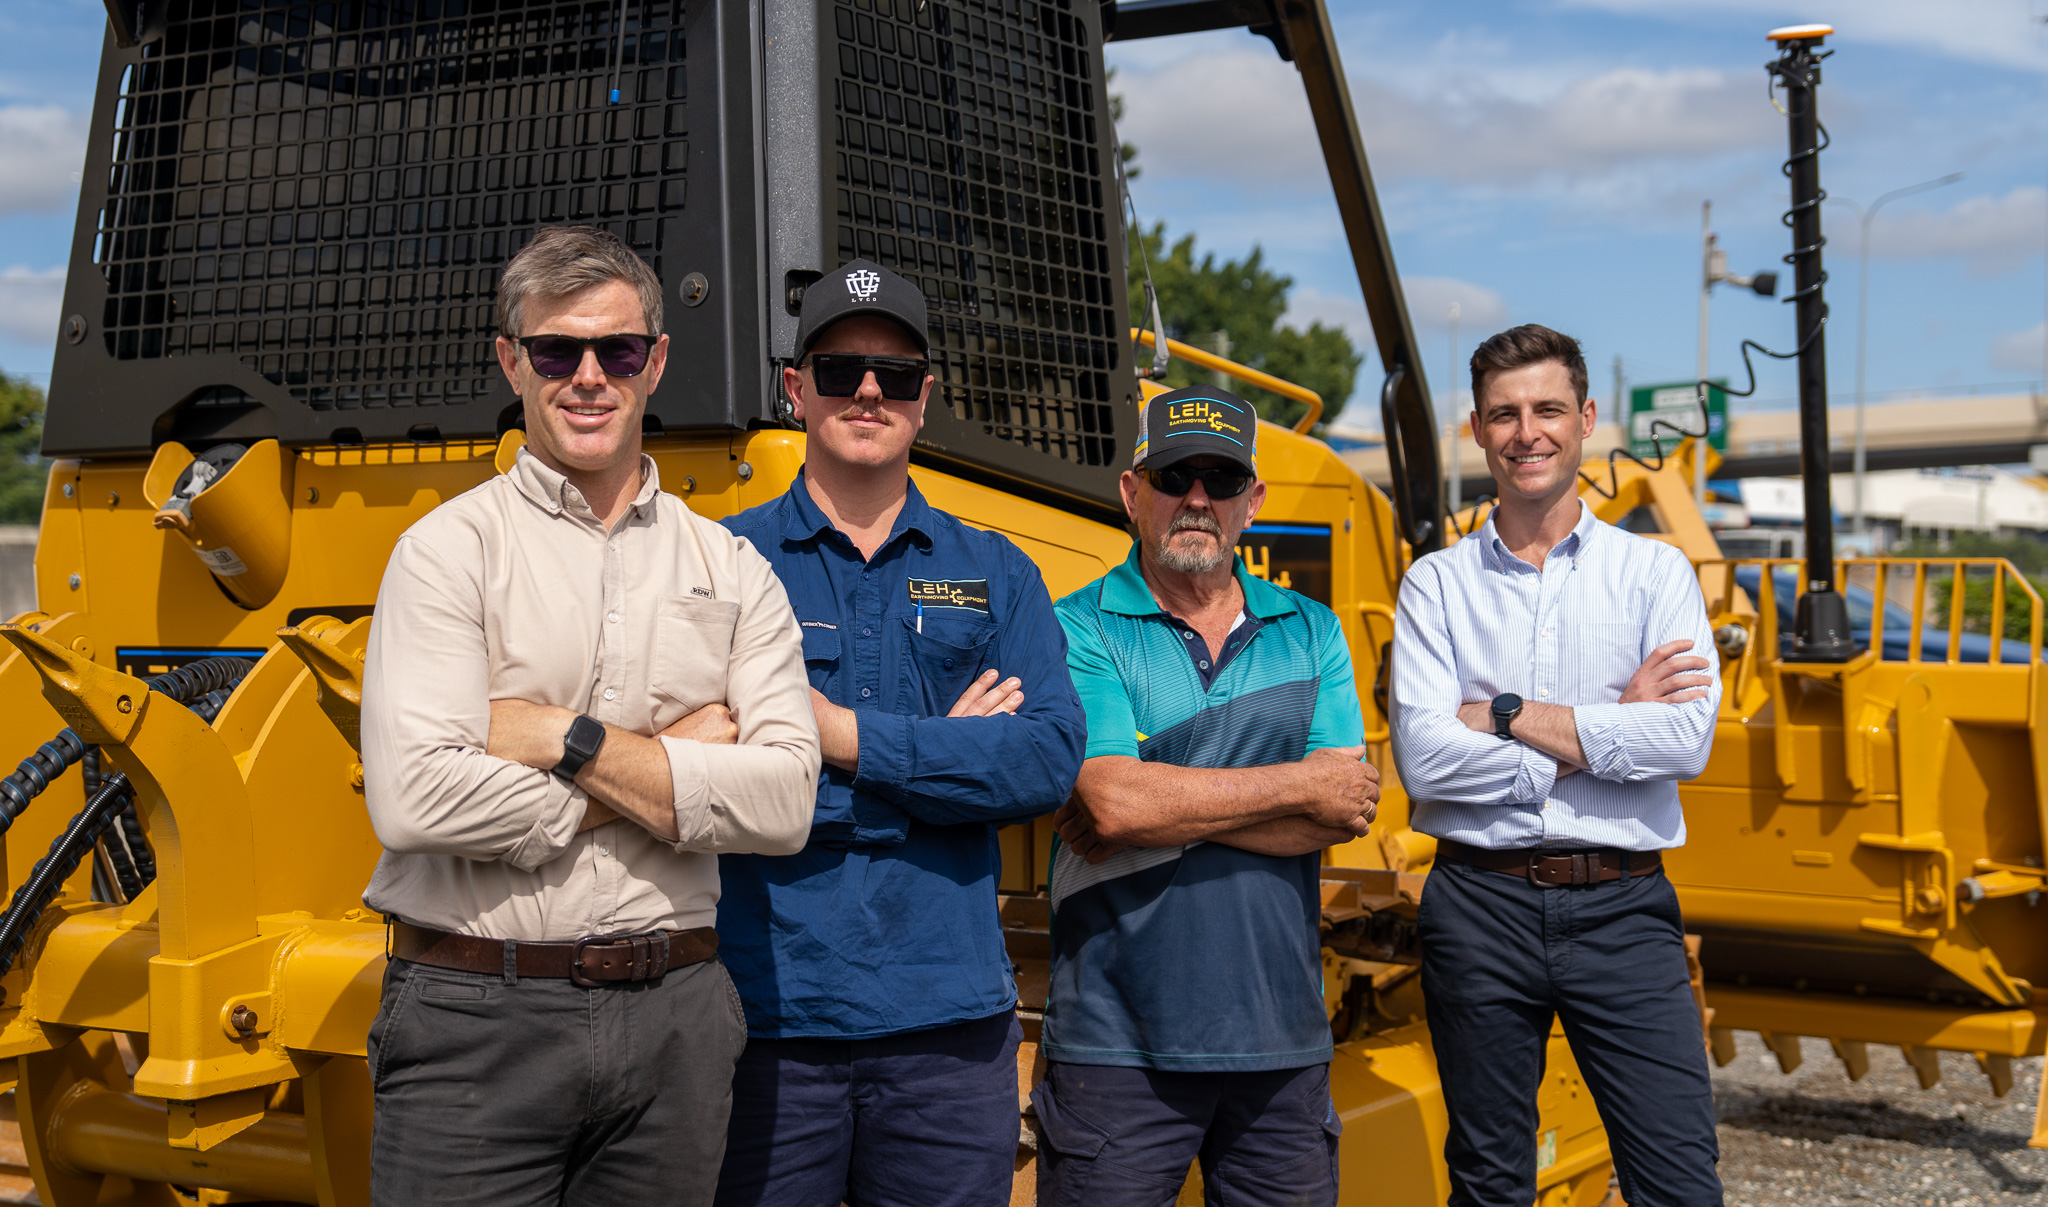
 From start-up to three dozers in three years.See full story
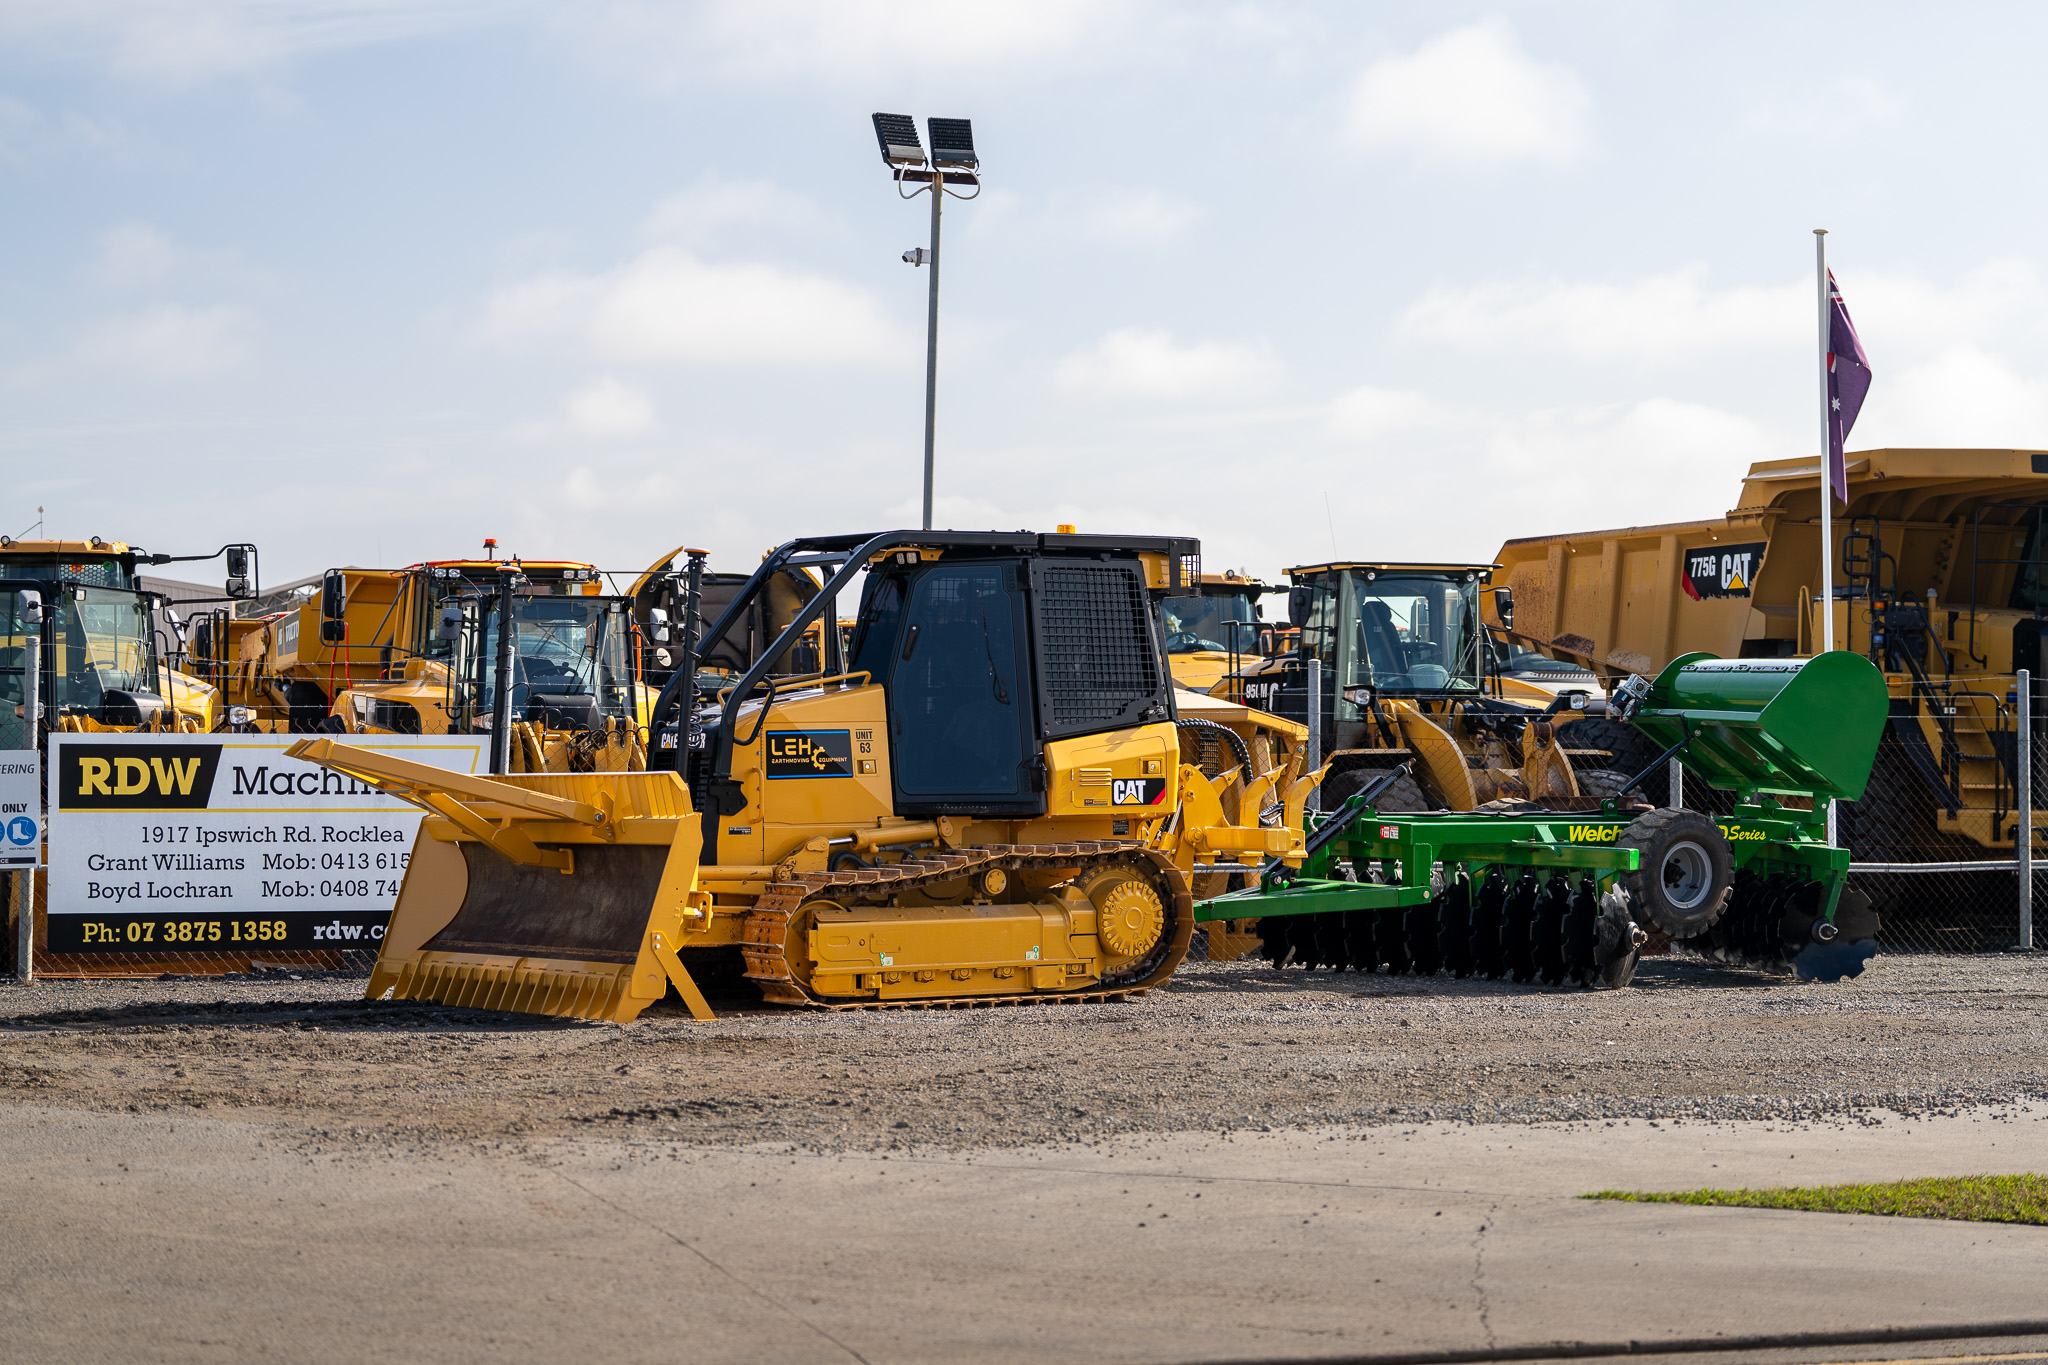
Funding for tractors, harvesters, forestry machines and supporting equipment, considered against the work, running costs and repayment capacity.
Additional equipment and replacements planned around seasonal income, utilisation and replacement timing, rather than as isolated purchases.
Larger equipment programs, lender relationships and annual funding capacity considered together, with visibility to debt and the next investment.
Plan the purchase around seasonal income, utilisation and replacement timing, with a clear view of repayments, existing commitments and future funding capacity.
Using two years of financials and recent reporting, we prepare the credit case for tractors, harvesters, forestry machines and supporting equipment. We explain trading performance, the purchase purpose and existing commitments to suitable banks and specialist equipment lenders.
Available for eligible purchases when approval or settlement timing is tight. We assess suitability and use these options selectively, preserving capacity for urgent requirements rather than defaulting to them for every purchase.
For eligible businesses making regular equipment acquisitions, an annually reviewed limit can provide clearer visibility to funding capacity. We assess expected purchases and lender criteria, with each drawdown subject to the agreed facility terms.
Equipment investment also affects working capital. We consider overdrafts, debtor finance, term loans and eligible trade facilities alongside seasonal income, utilisation and replacement timing and the wider debt position.
Know the payouts and potential trade values before replacing tractors, harvesters, forestry machines and supporting equipment. We map the existing debt, supplier delivery dates and funding requirements to help coordinate the changeover.
Review facilities that no longer fit, debt spread across lenders and opportunities to release eligible asset equity. Restructuring may free up funding capacity or soften monthly repayments; we assess payout costs, security and the total interest effect of a longer term.

James and Dan have worked in bank credit and broking. We review the financials, existing debt and supporting information before approaching lenders, and work with you and your advisers to explain material entries or changes clearly. A well prepared application gives lenders a fairer picture of the business.
We give you a direct view of the funding opportunities we see, where the challenges sit and how confident we are in the proposed approach. We map out equipment debt, lender exposures and available capacity between all lenders, so you get complete visibility to how far you can go on your equipment investment.
The lowest priced lender for today’s equipment may be the lender you need for a much larger facility tomorrow. We consider where each asset belongs across the available banks and specialist lenders, protecting room for future purchases where we can.
Where the business and lender criteria support it, we can pursue an annual equipment finance limit. It gives you an agreed funding framework for eligible purchases through the year, with each drawdown assessed and documented under the lender’s terms.
As your needs grow, we can introduce and work alongside suitable business or corporate bankers. That can open conversations about broader facilities, including working capital, trade funding and commercial property finance, while keeping the equipment strategy connected.
Unencumbered equipment, or assets nearing the end of their finance term, may offer an opportunity to release equity in times of a cashflow pinch. We can assess the equipment, valuation and lender options to see whether refinancing could return useful cash to the business.
Business owners need someone they can speak with candidly. We bring an independent perspective shaped by years of working with operators across the country, keep your information confidential and stay involved as your plans change.
One machine or a major equipment program. Let’s map the capacity and timing before you commit.
Let’s grow togetherCredit expertise, direct relationships and a wider choice of lenders, backed by recognised work in commercial finance.
Australian Broking Awards
Finalist 2026
CAFBA
Finalist 2023
James Allan on commercial finance
Featured guest
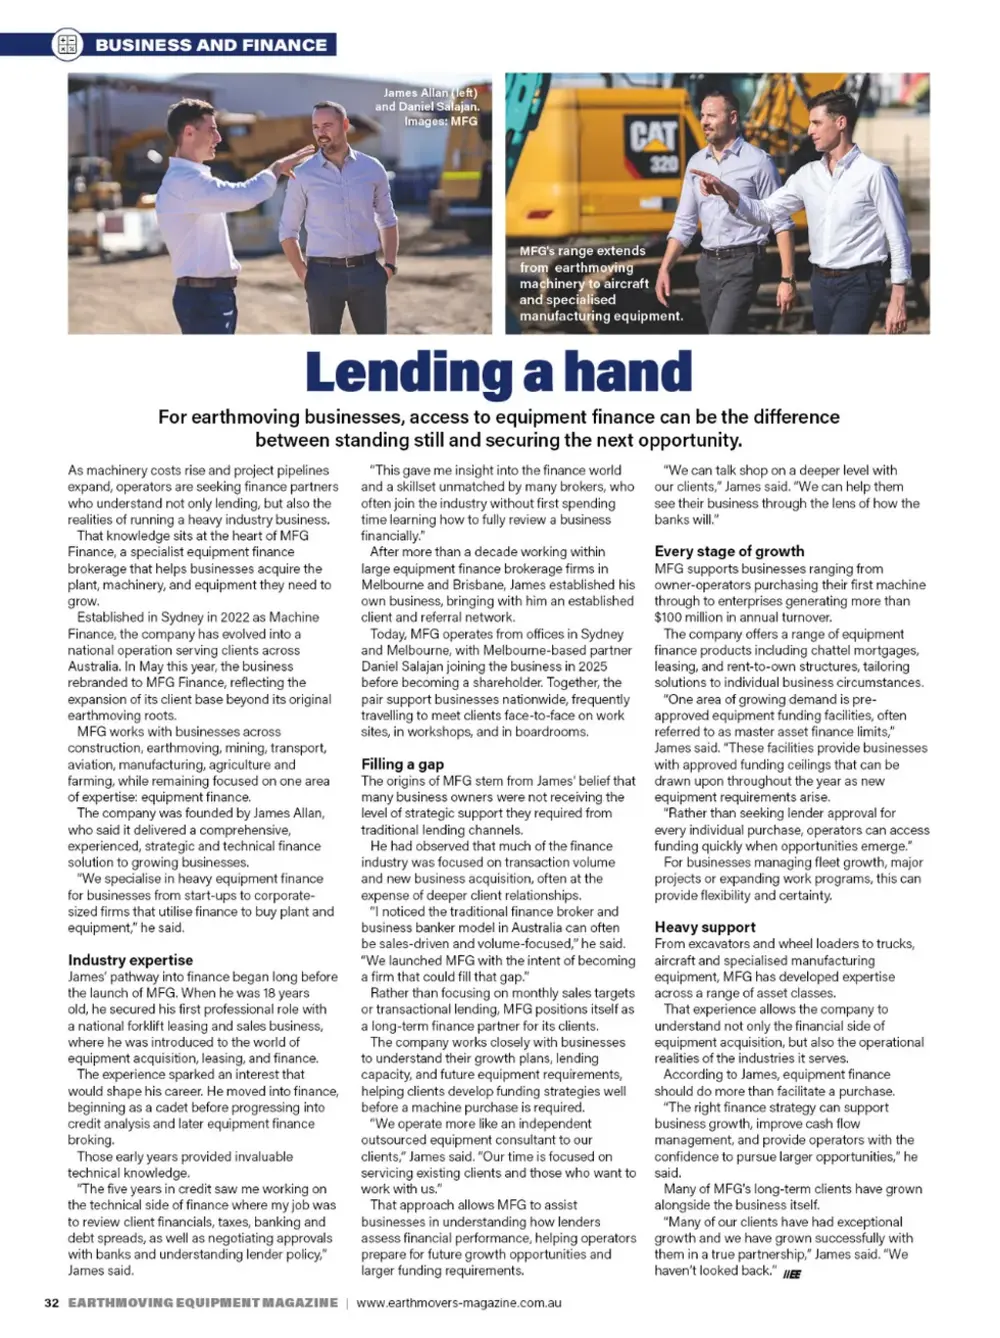
“Lending a hand”
Featured article
MFG is directly accredited with all major banks, alongside an extensive panel of non-bank, specialist and private lenders.
 CAFBA 101556
 FBAA M-359967
 AFCA 89354
Panel shown is indicative and subject to lender accreditation, credit policy and transaction requirements.
See how term, rate, balloon and payment timing change the monthly commitment.
Illustration only. Assumes a fixed nominal annual rate divided into monthly periods, level monthly payments and a balloon due at the end. Excludes fees, taxes and insurance. In advance means the first repayment is made at the start. This is not a lender quote.
Talk through the purchase →








Yes. We assess tractors, harvesters, forestry machines and supporting equipment, including new and used purchases, against the asset condition, valuation, business cash flow and lender criteria.
Tell us about supplier payments, freight, installation and commissioning early. We assess which costs and payment stages lenders can support before you commit, including eligible overseas purchases.
We work through seasonal income, utilisation and replacement timing, recent reporting and existing debt to assess the term, deposit, balloon and repayment options available. The lender must be comfortable with the repayment capacity and proposed structure.
Yes. We map each payout, proposed trade or sale value and replacement cost, then work through any shortfall and supplier timing before arranging the new funding.
Yes. A coordinated equipment program may suit a growing business better than individual applications. We review existing lender exposure, expected acquisitions and whether annual limits are appropriate.
Buying your first machine? Replacing a fleet? Start with the situation as it is. We’ll talk through the assets, the timing and what the next decision means for your business.
Replacing equipment or planning the next purchase? Tell us what you have in mind.
"*" indicates required fields