From business acquisition to quarry mobilisation.

How MFG helped Jesse Medwin map an acquired fleet and fund roughly $2 million in crusher and screener equipment.

See the story ↓

Let’s grow together.

Tell us about the next purchase you have in mind.

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
Name*
Crezzco

One acquisition. A working fleet. The next contract.

Crezzco operates near Launceston, Tasmania. Jesse Medwin owns and runs a business supplying quarry and crushing products, fertiliser to local farmers and bulk haulage services. It owns a quarry and undertakes quarry contracting work.

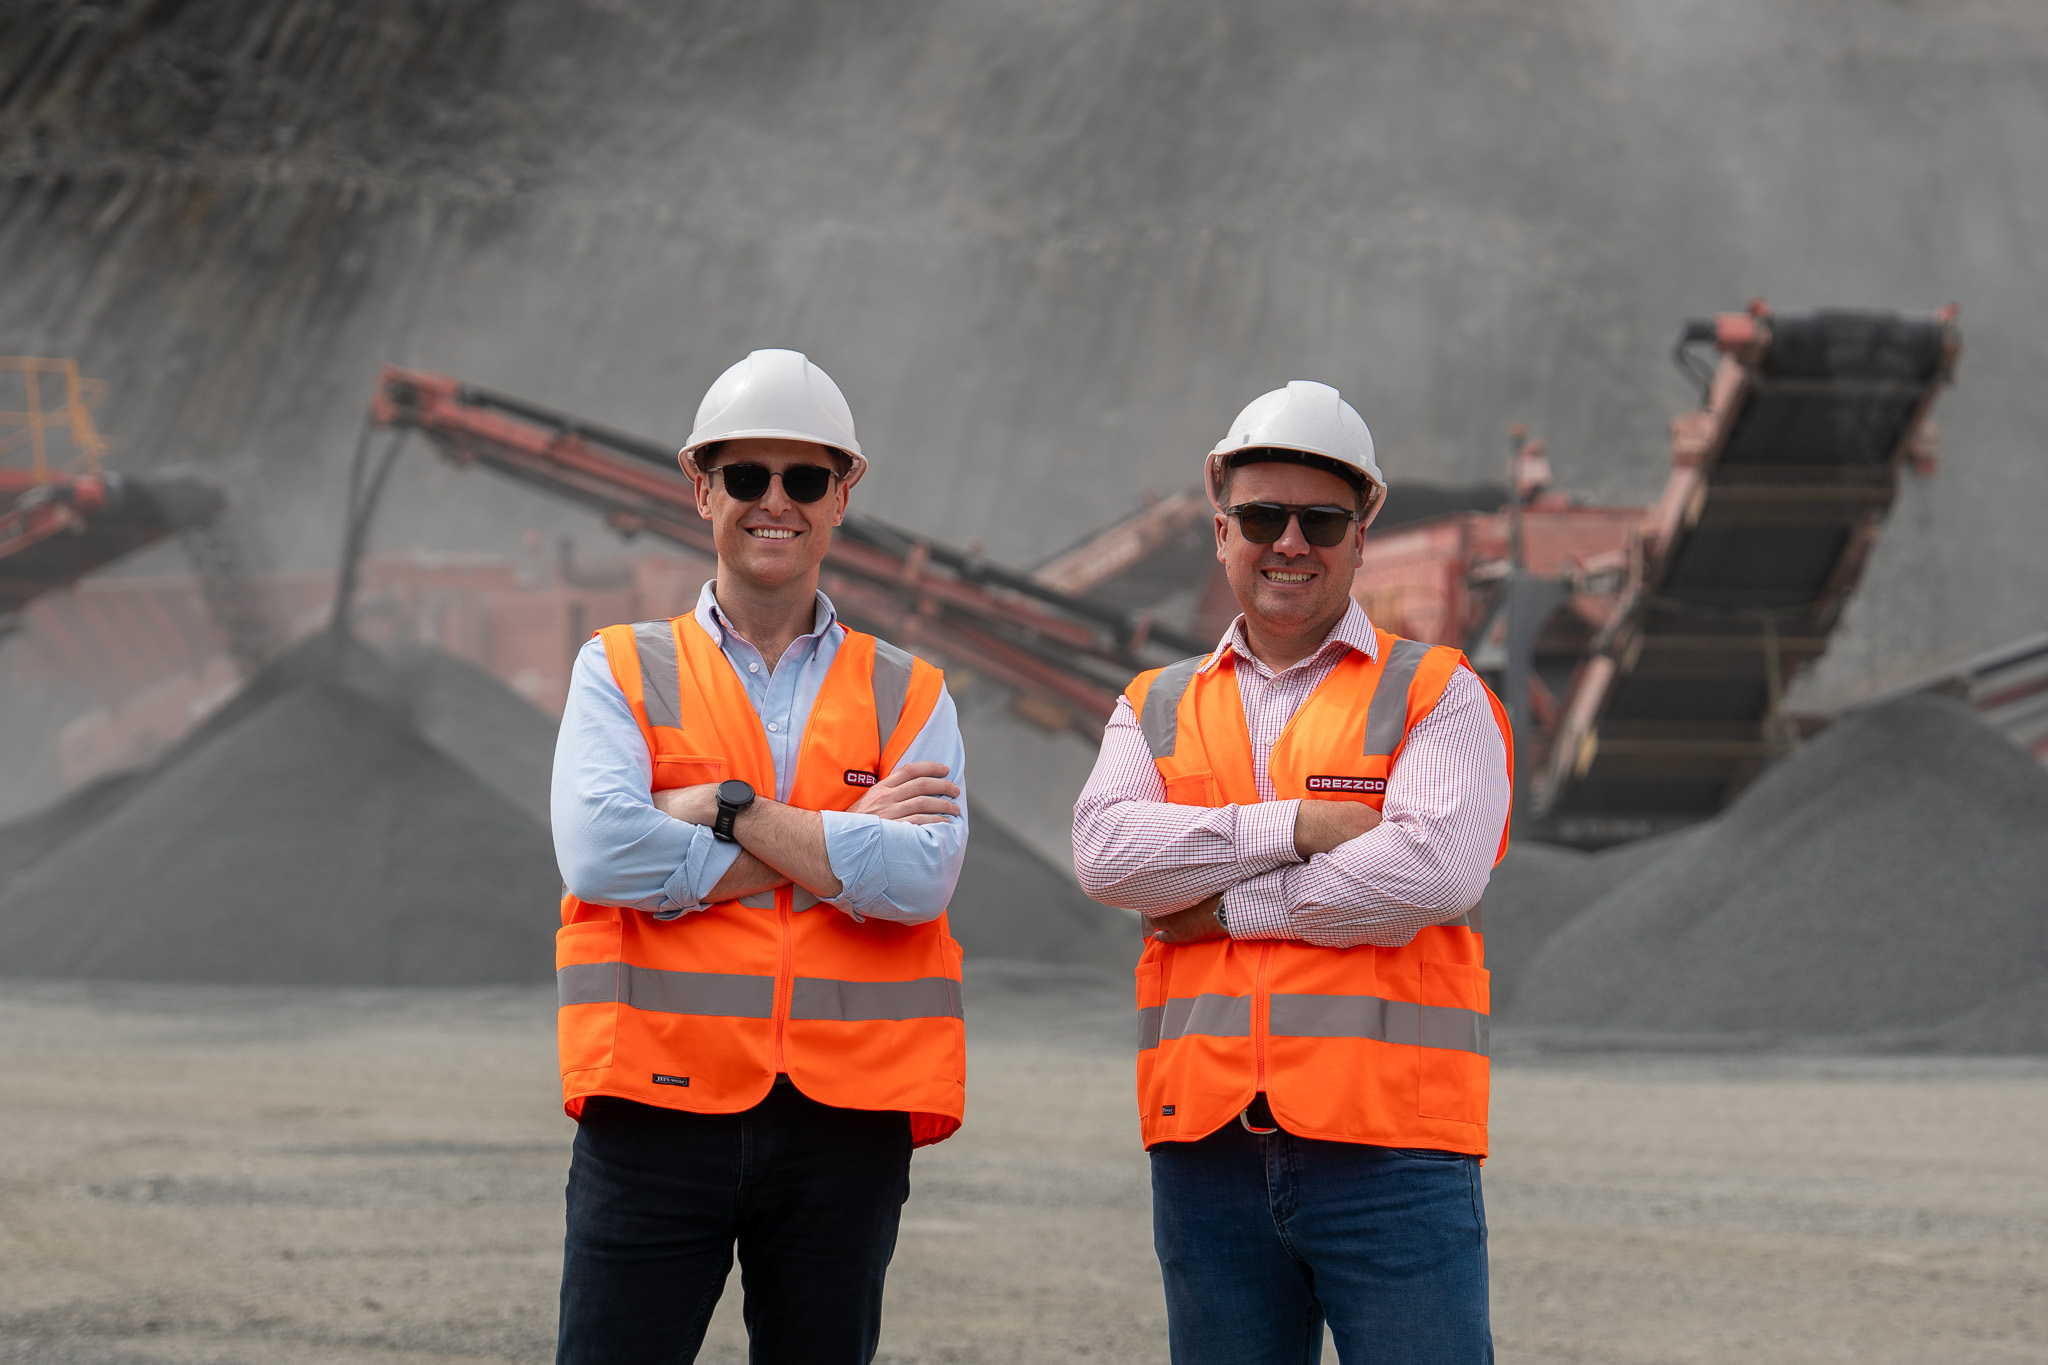
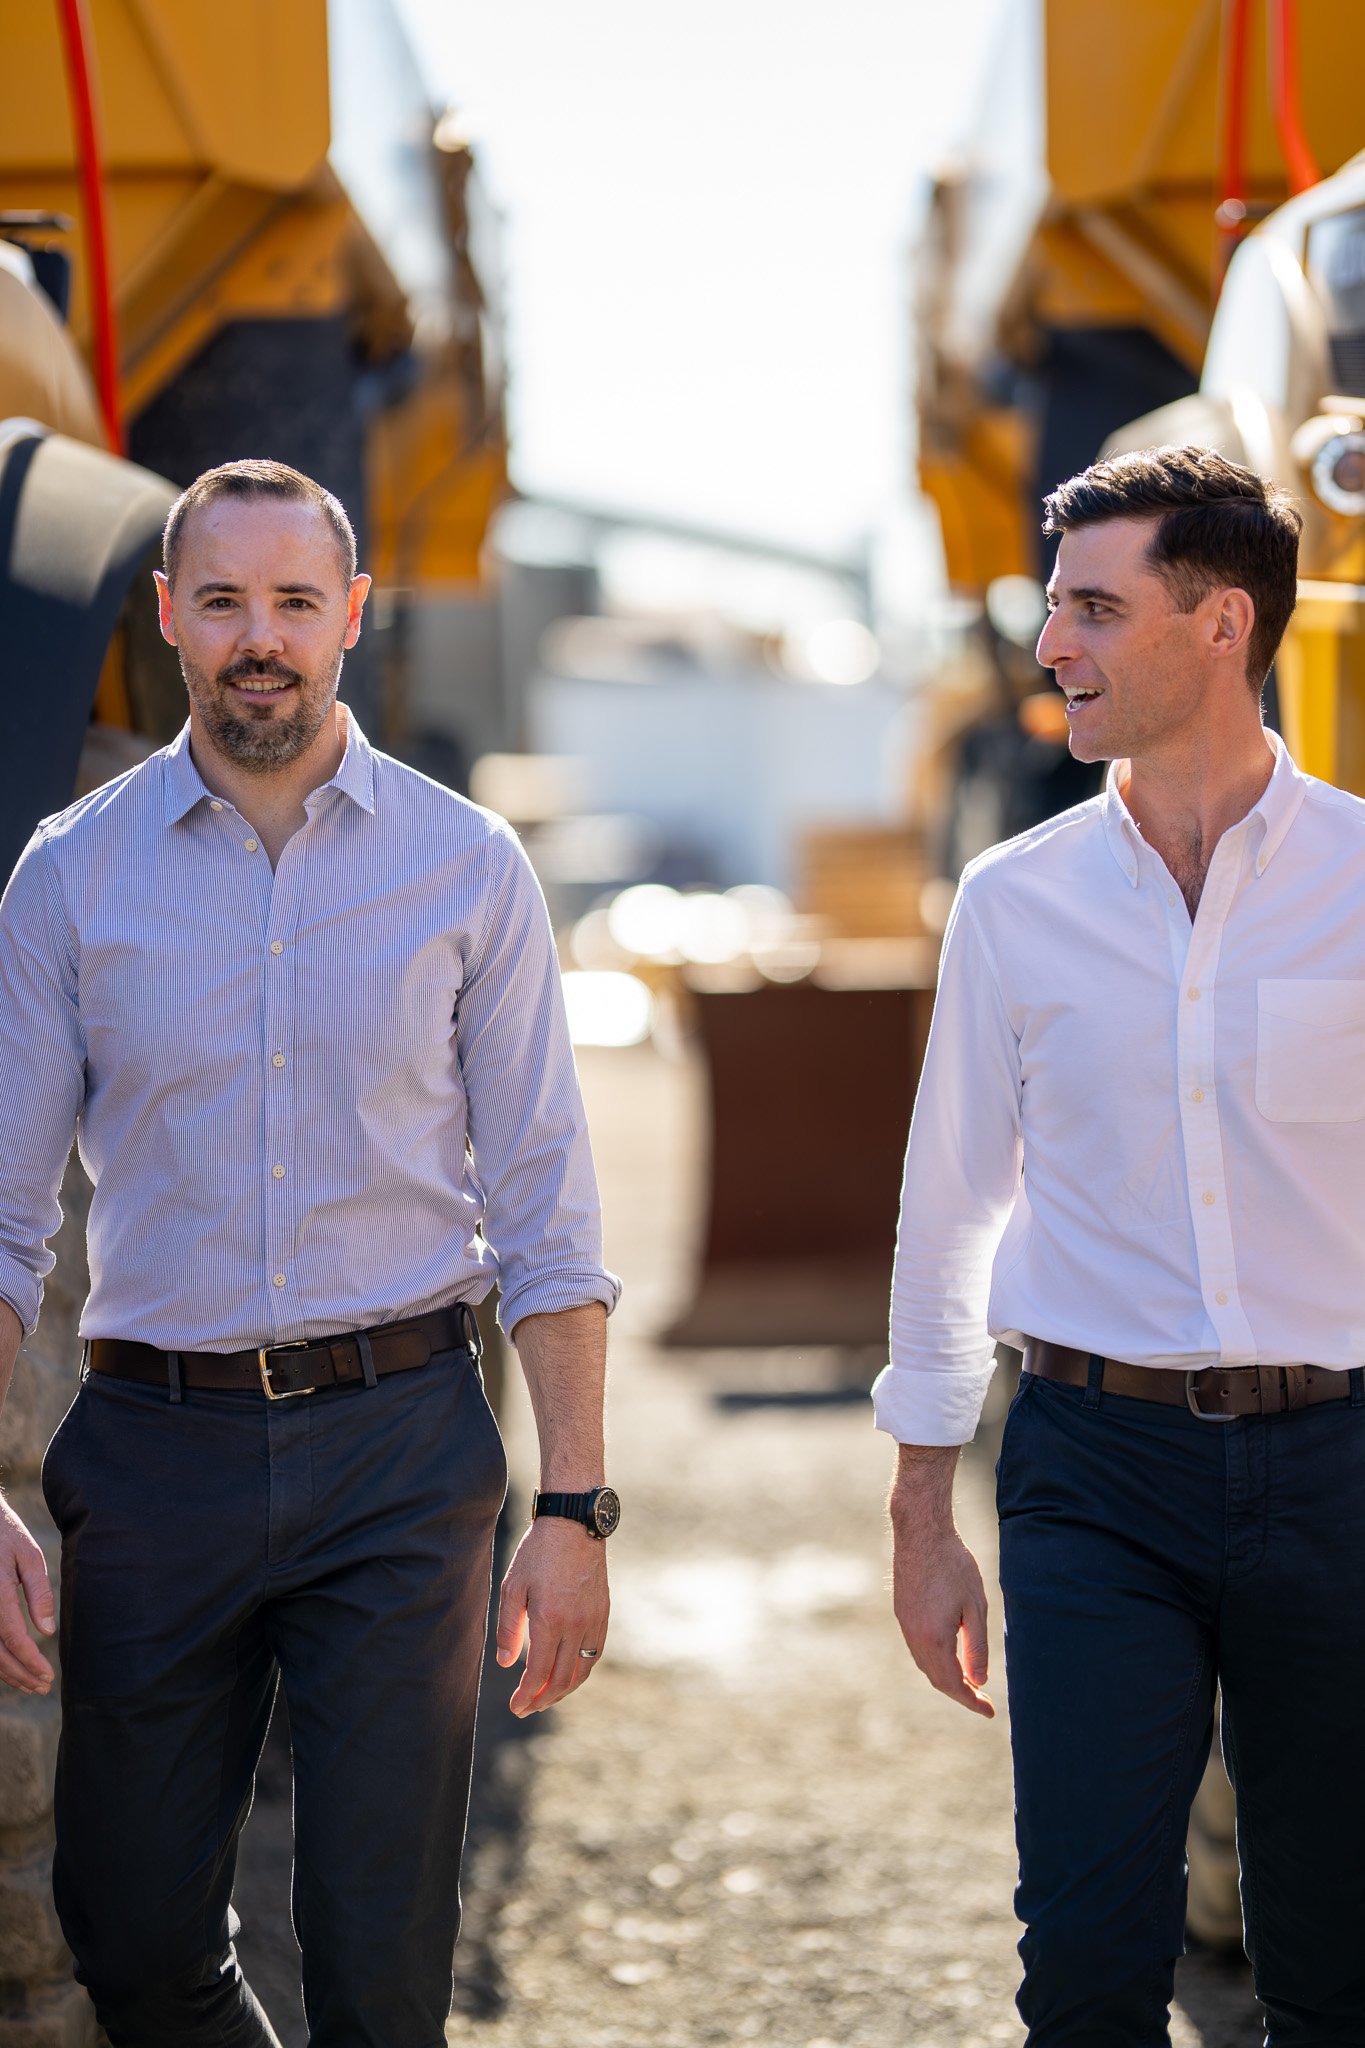
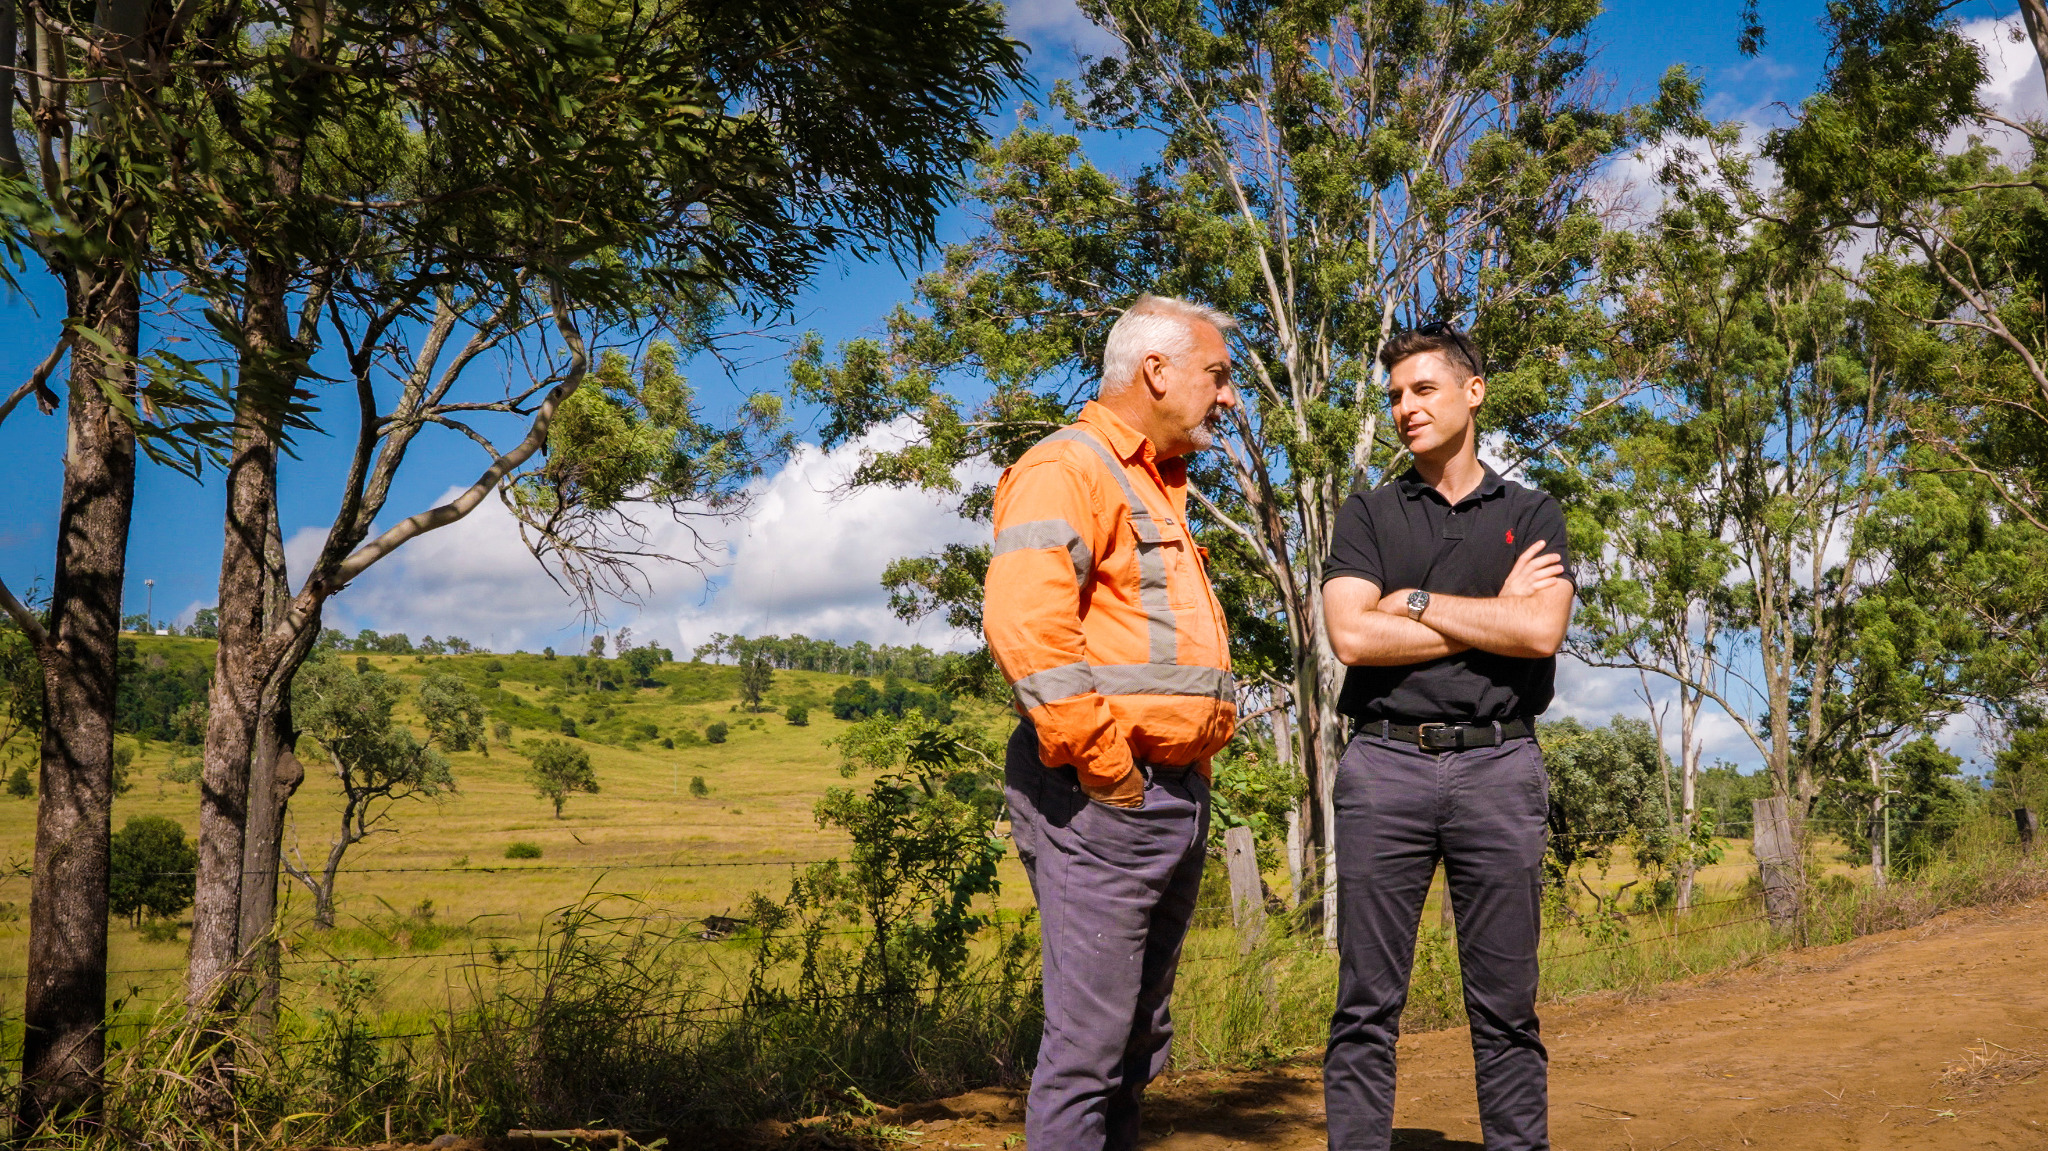
Jesse Medwin and James Allan at the quarry
A new owner

An established business and a fleet to understand

James Allan met Jesse in late 2024 or early 2025 as Jesse worked through the acquisition. Jesse had sold a successful finance brokerage and was involved in a family civil contracting business. He knew lending, but this purchase brought an operating business and a varied fleet of approximately 50 assets together.

Jesse was already arranging acquisition funding when MFG became involved. We examined the equipment and debt position within the wider transaction, looking for alternatives to placing all funding with one lender.

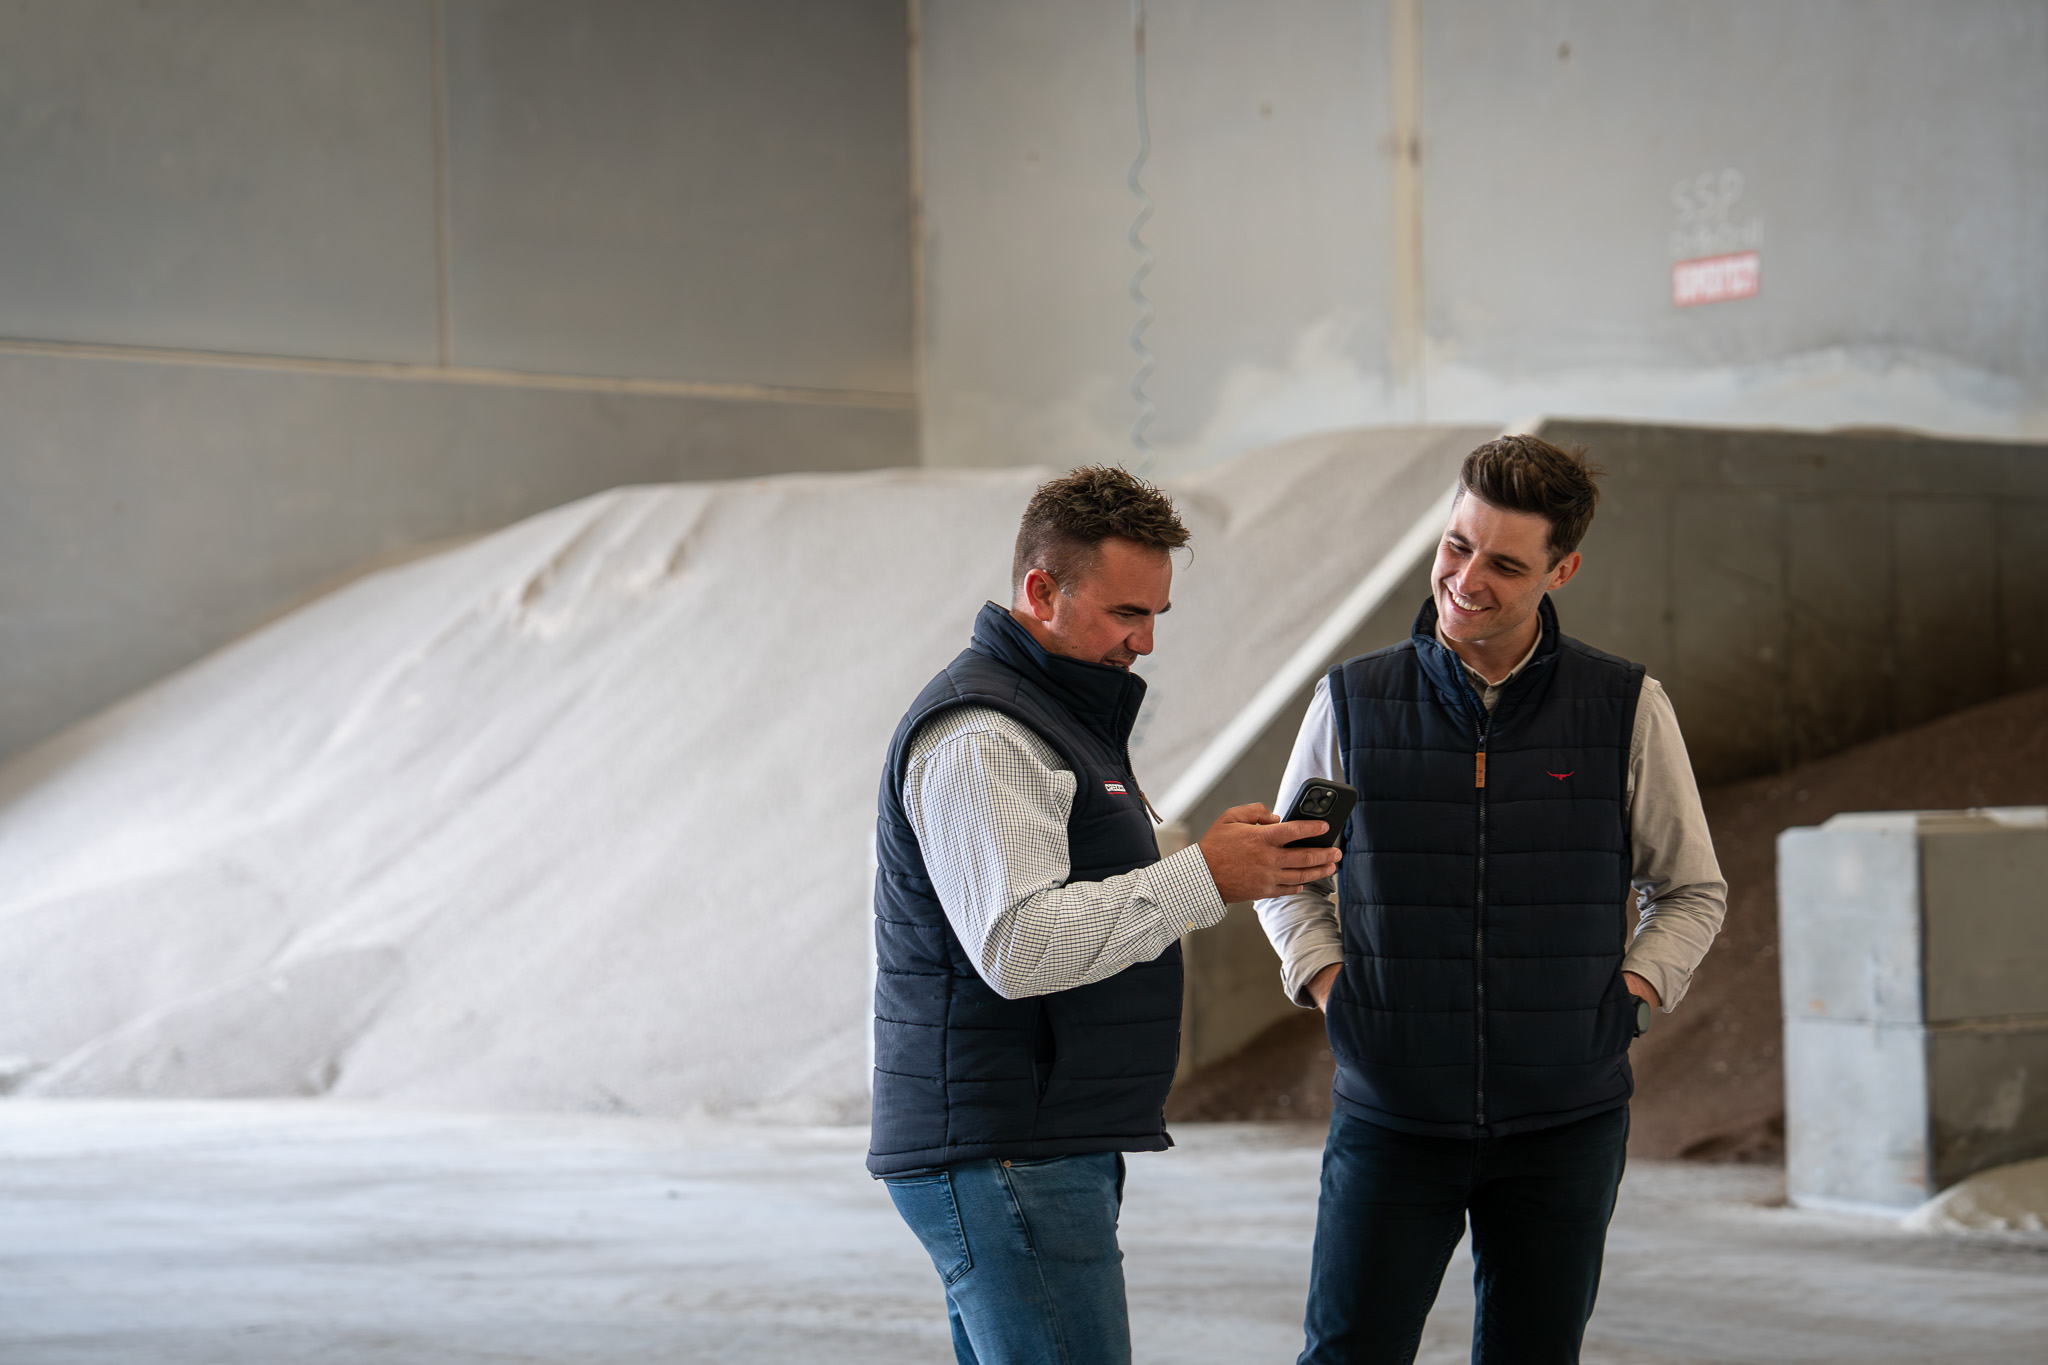
James and Jesse reviewing the operation
The acquisition

Dissecting the equipment debt

A business can have one negotiated purchase price without funding every asset in the same way. MFG reviewed the fleet and its existing commitments, then considered which equipment could be financed separately through suitable lenders.

That gave Jesse options during the acquisition. Spreading eligible equipment debt could reduce the amount sought from the principal acquisition lender and create room to negotiate credit conditions, including security. MFG consulted on the wider funding position and arranged finance for selected equipment. We did not finance the entire business purchase.

The review also gave Jesse a clearer starting point as owner: what sat in the fleet, which lenders already had exposure and where future capacity might be available. He could consider older assets and replacement needs with the full operation in view.

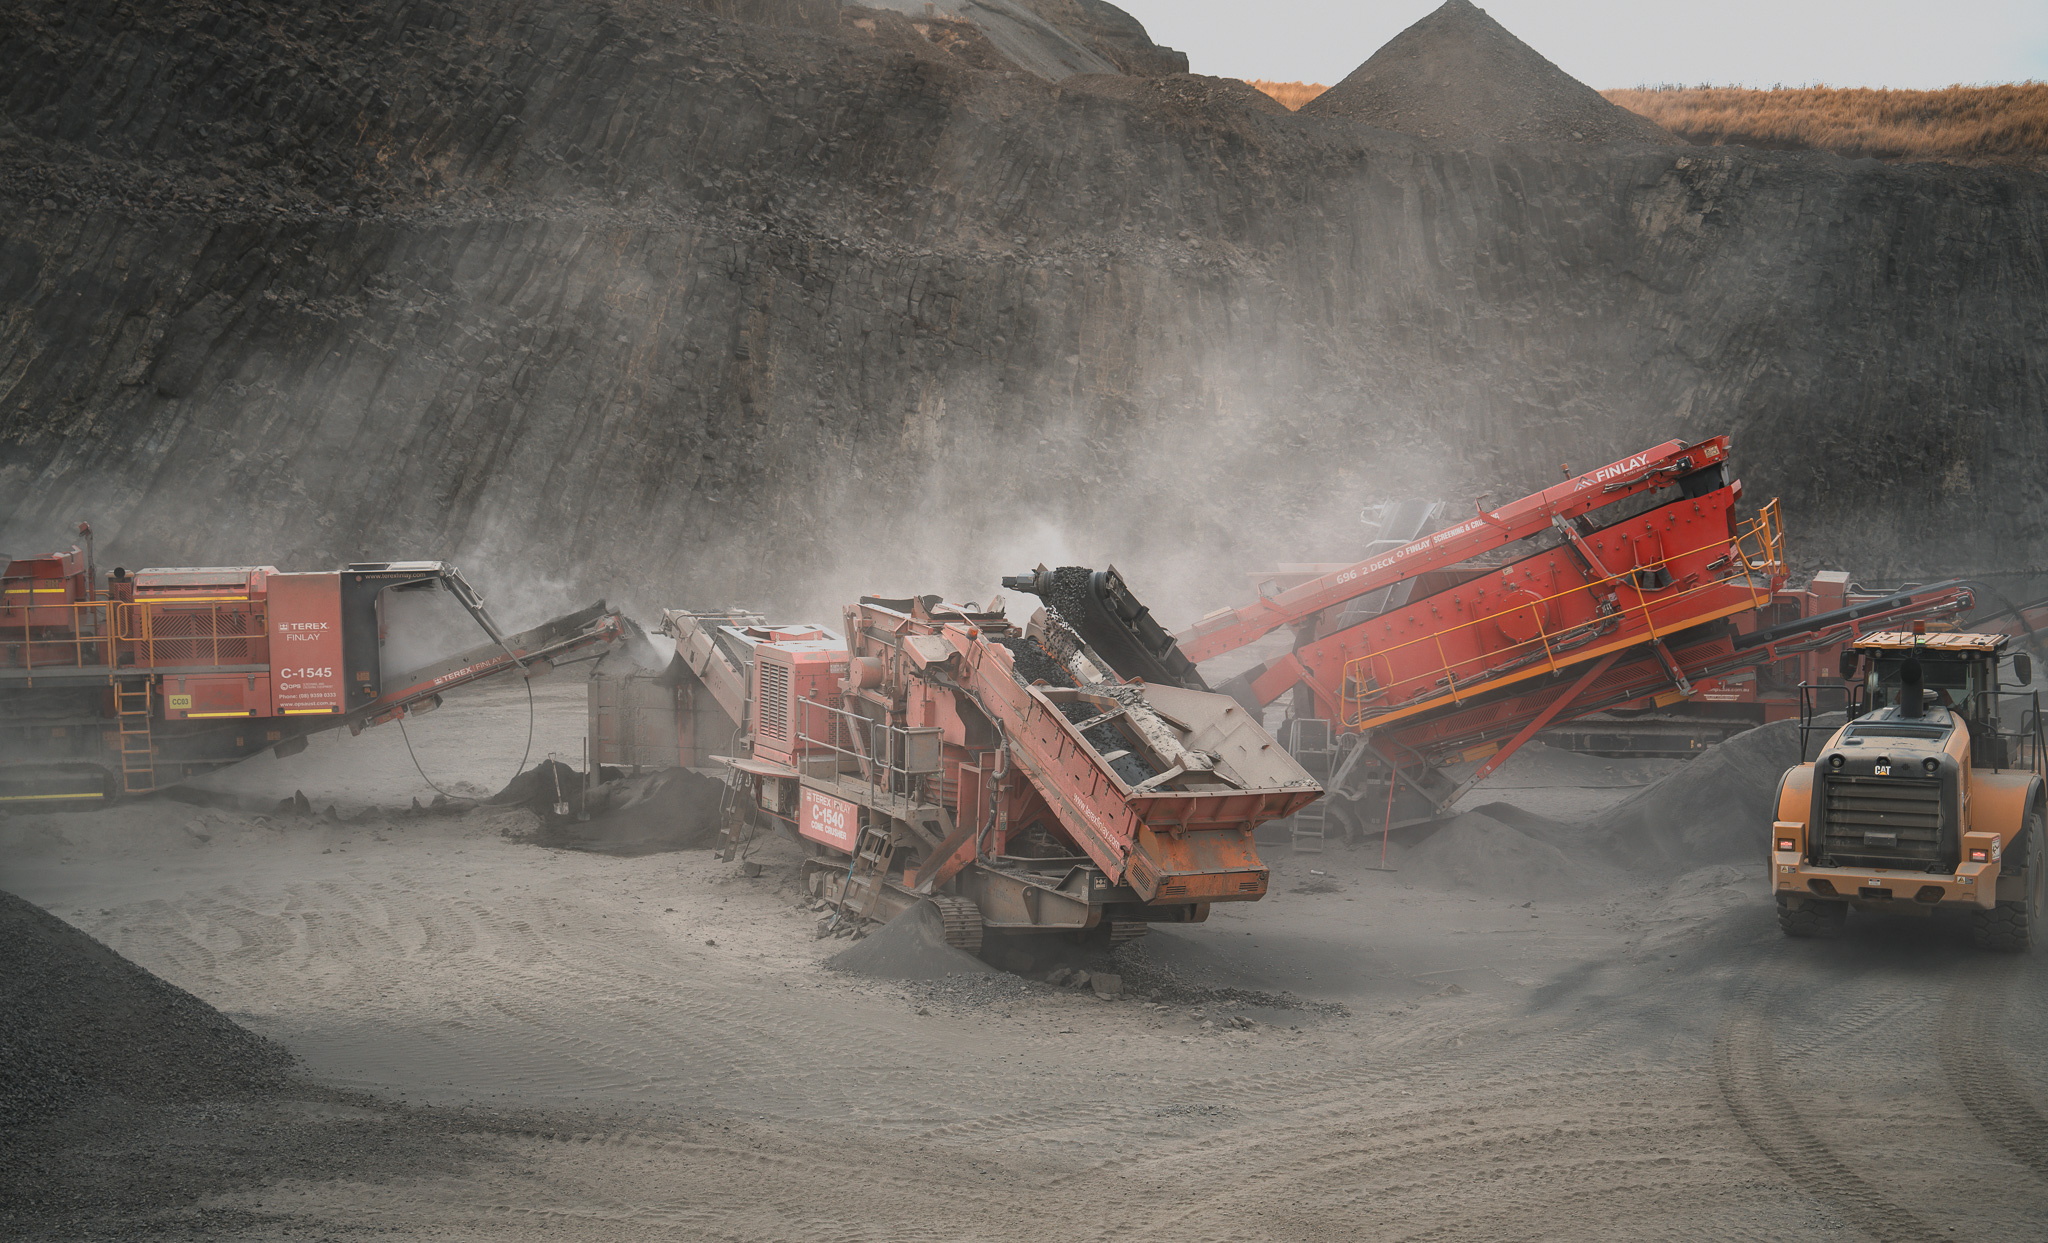
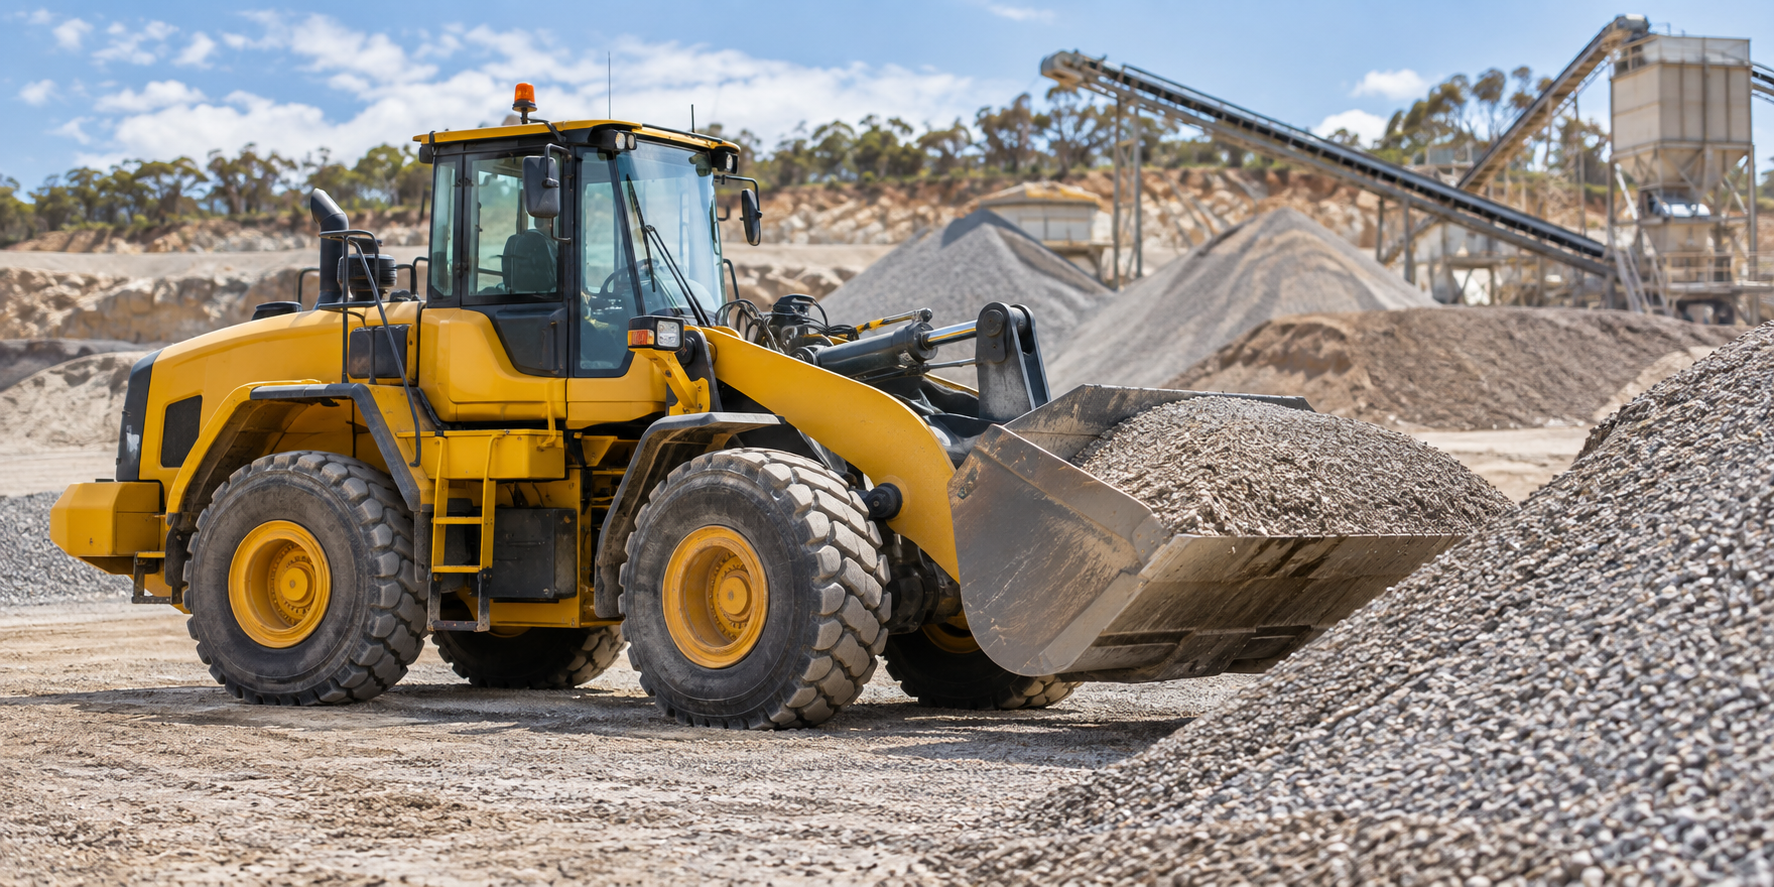
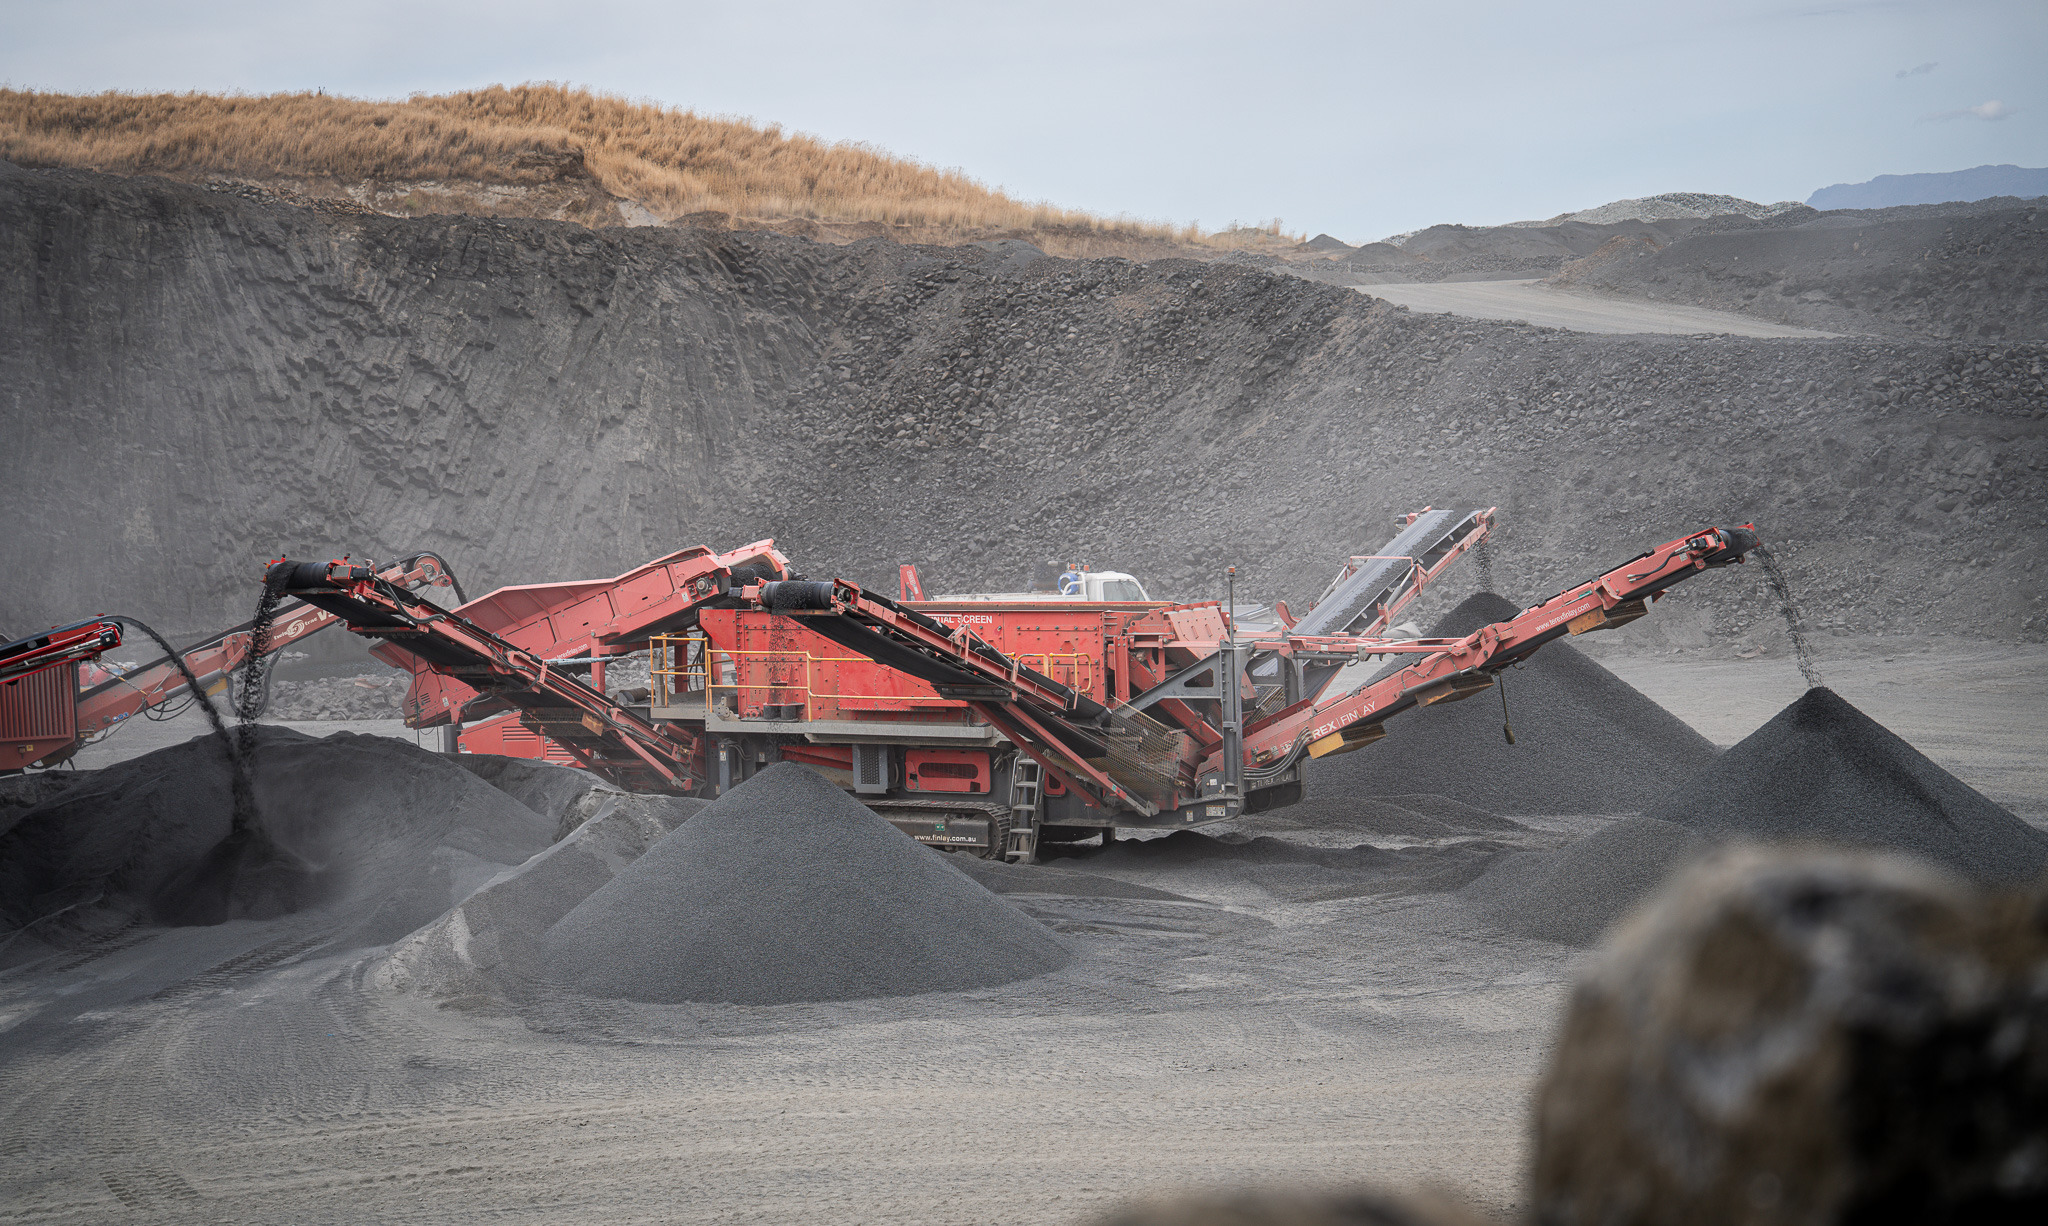
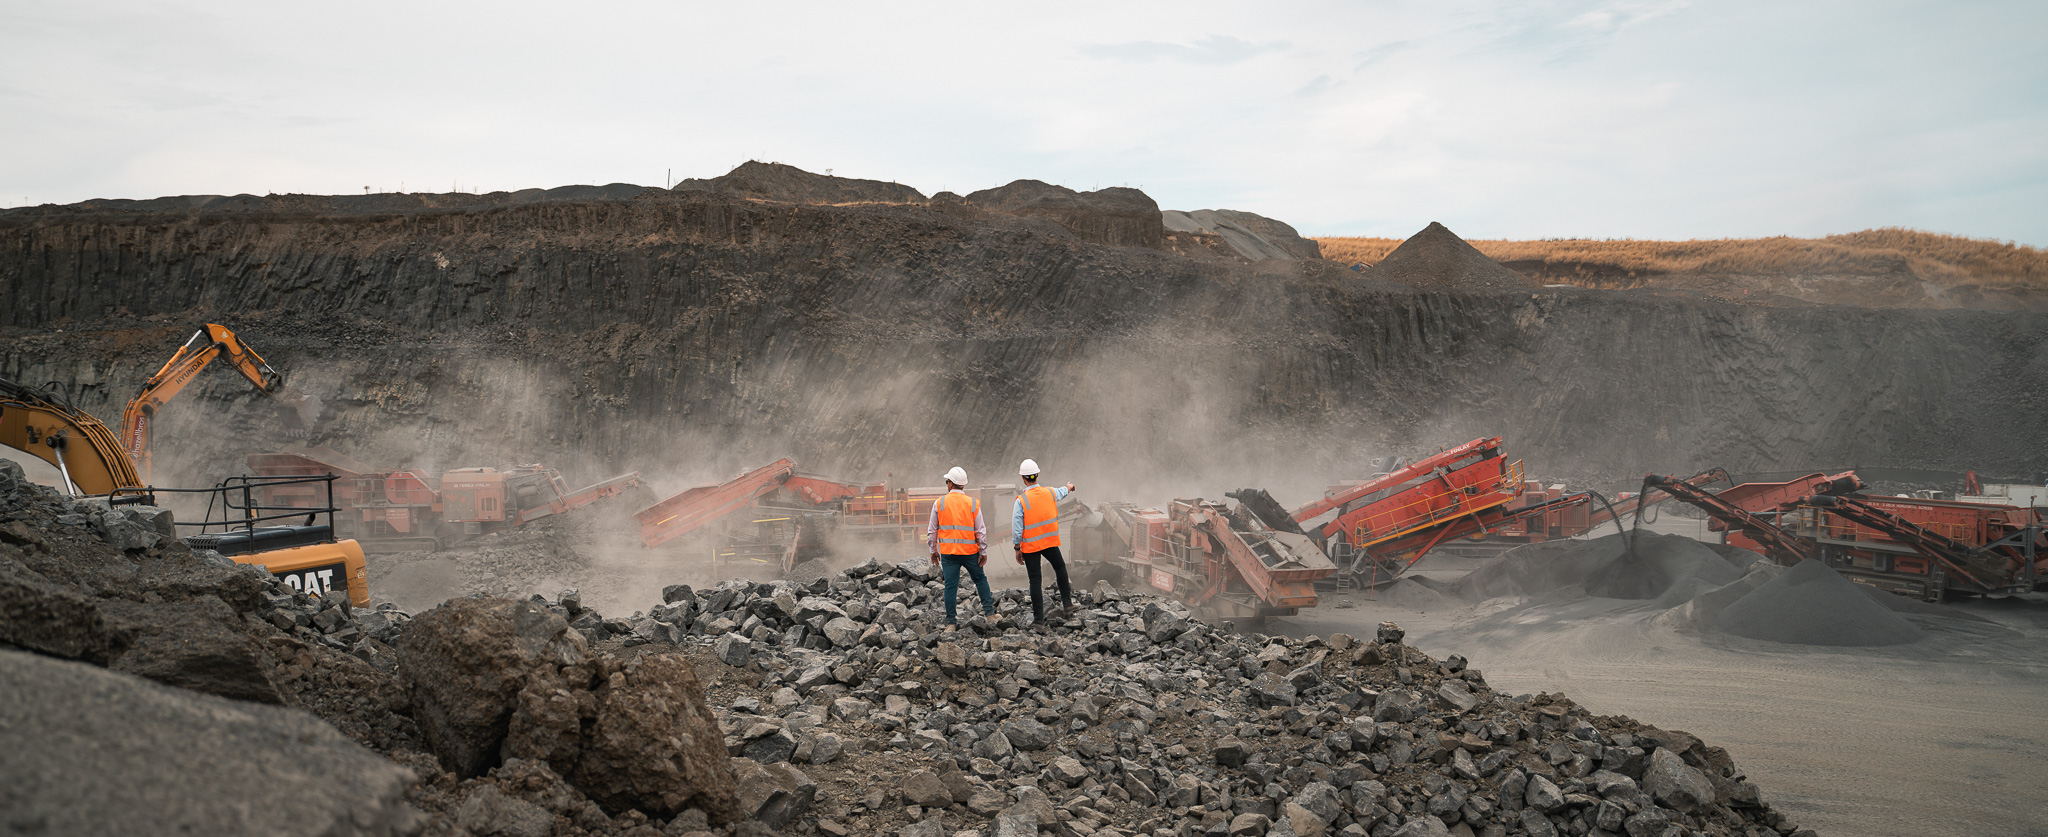
Crezzco crushing equipment at work
A new contract

Roughly $2 million of crusher and screener plant

At the same time, Jesse pursued a local quarry crusher and screener contract. Delivering the work required roughly $2 million in additional equipment, including a Terex crusher and a Finlay screener. The funding request had to account for an ownership transition and a new equipment program together.

MFG worked with Jesse and his accountant on three-way financial projections: forecast profit and loss, cash flow and balance sheet. Those forecasts helped lenders understand the proposed operation, mobilisation and repayments beyond a simple revenue estimate. We took the transaction to lenders with an appetite for equipment funding supported by credible forward projections.

Approval was secured for the equipment Jesse needed. The structure combined an initial cash contribution with accelerated repayments, preserving more cash than a larger upfront deposit would have.

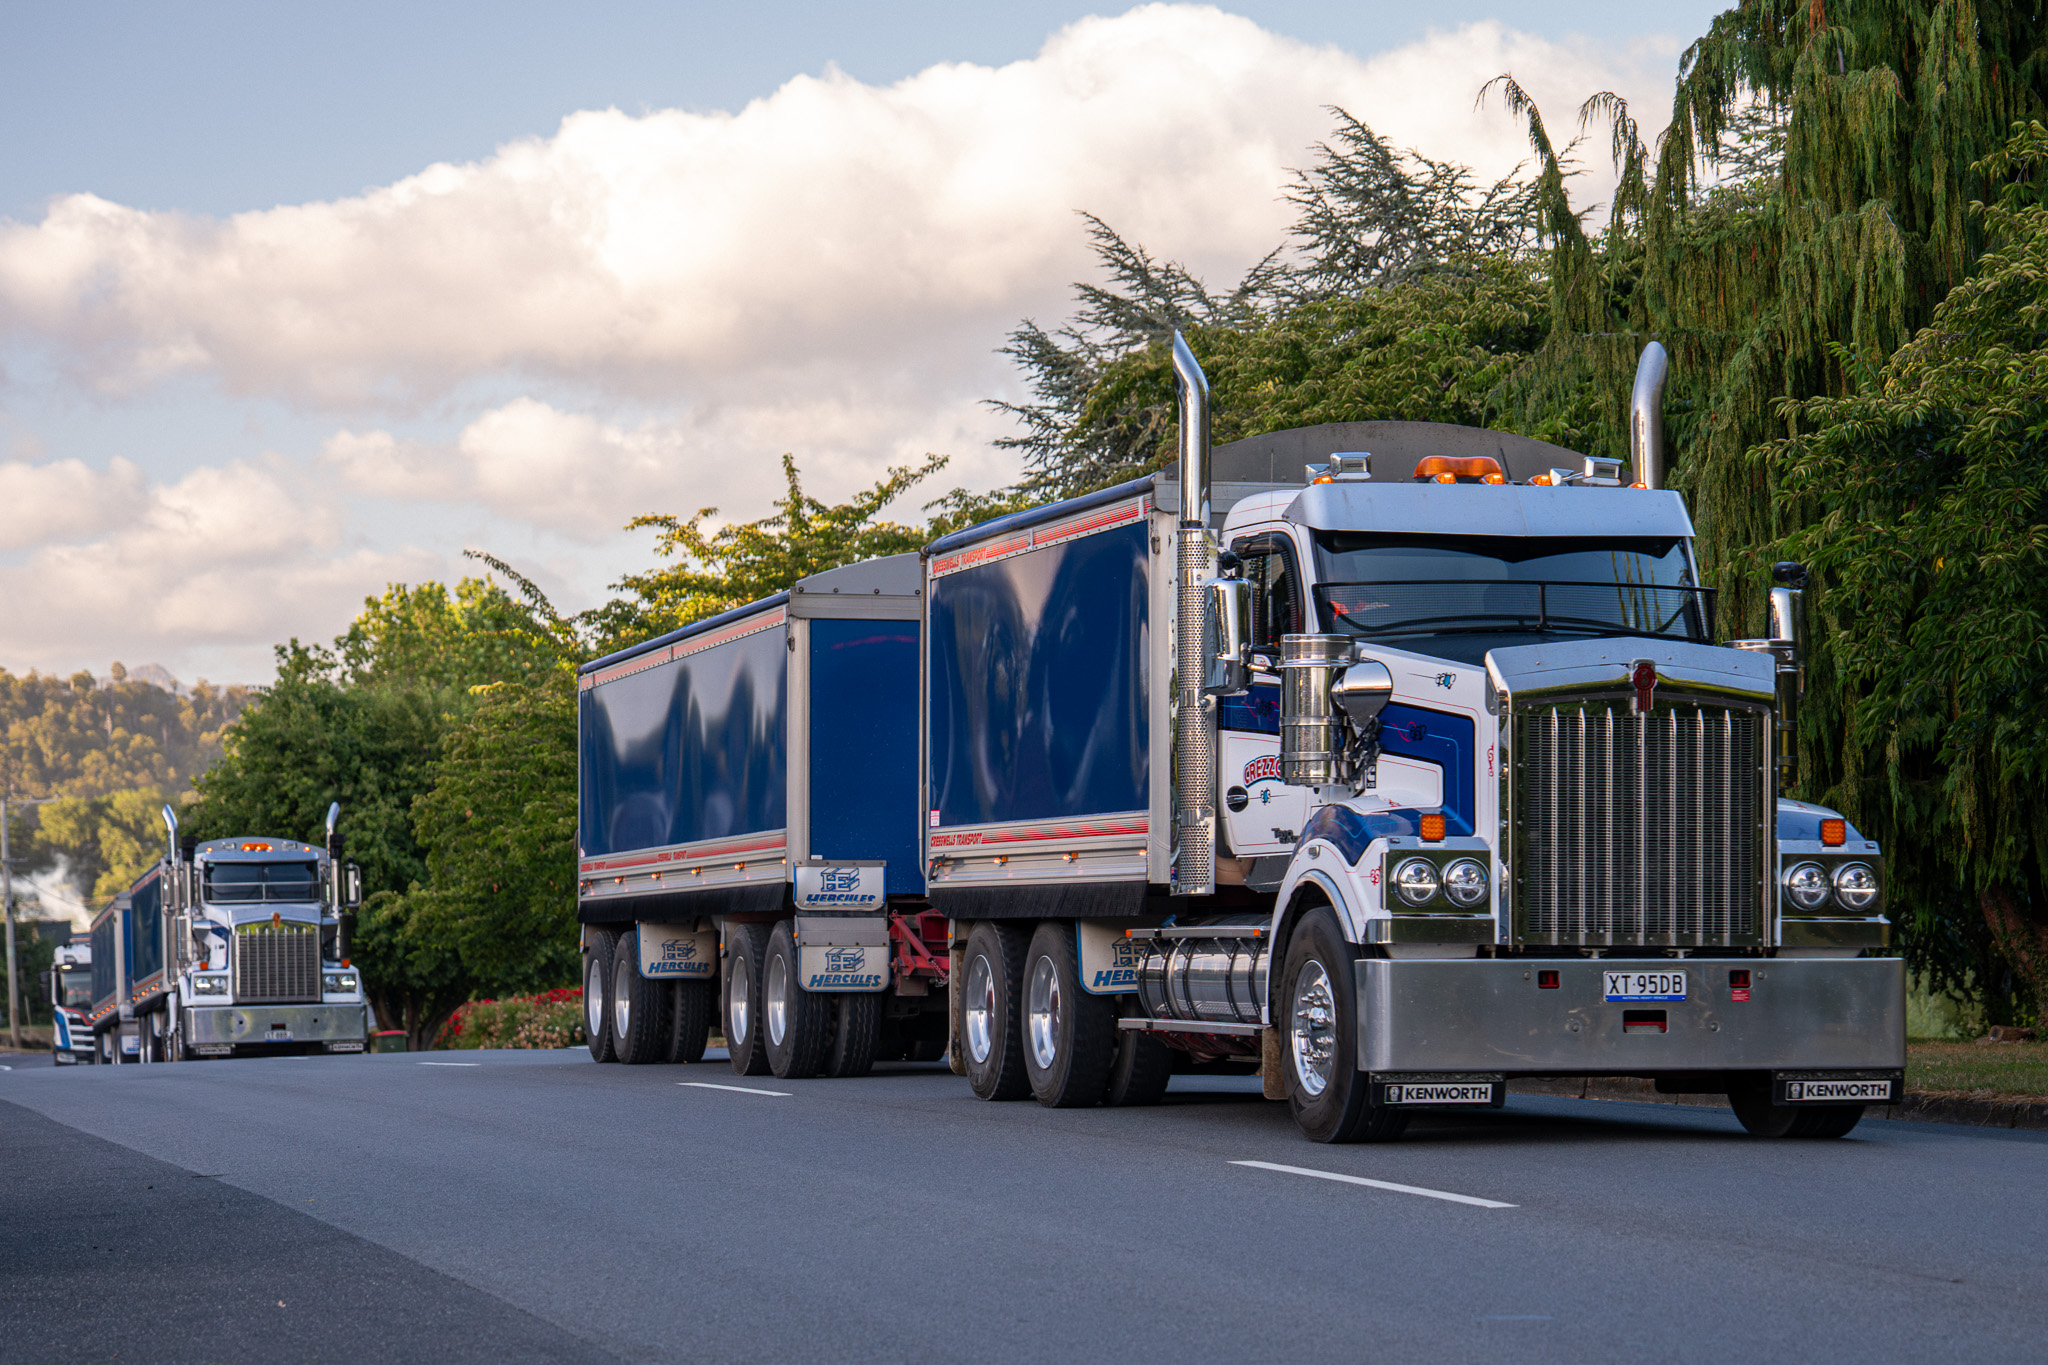
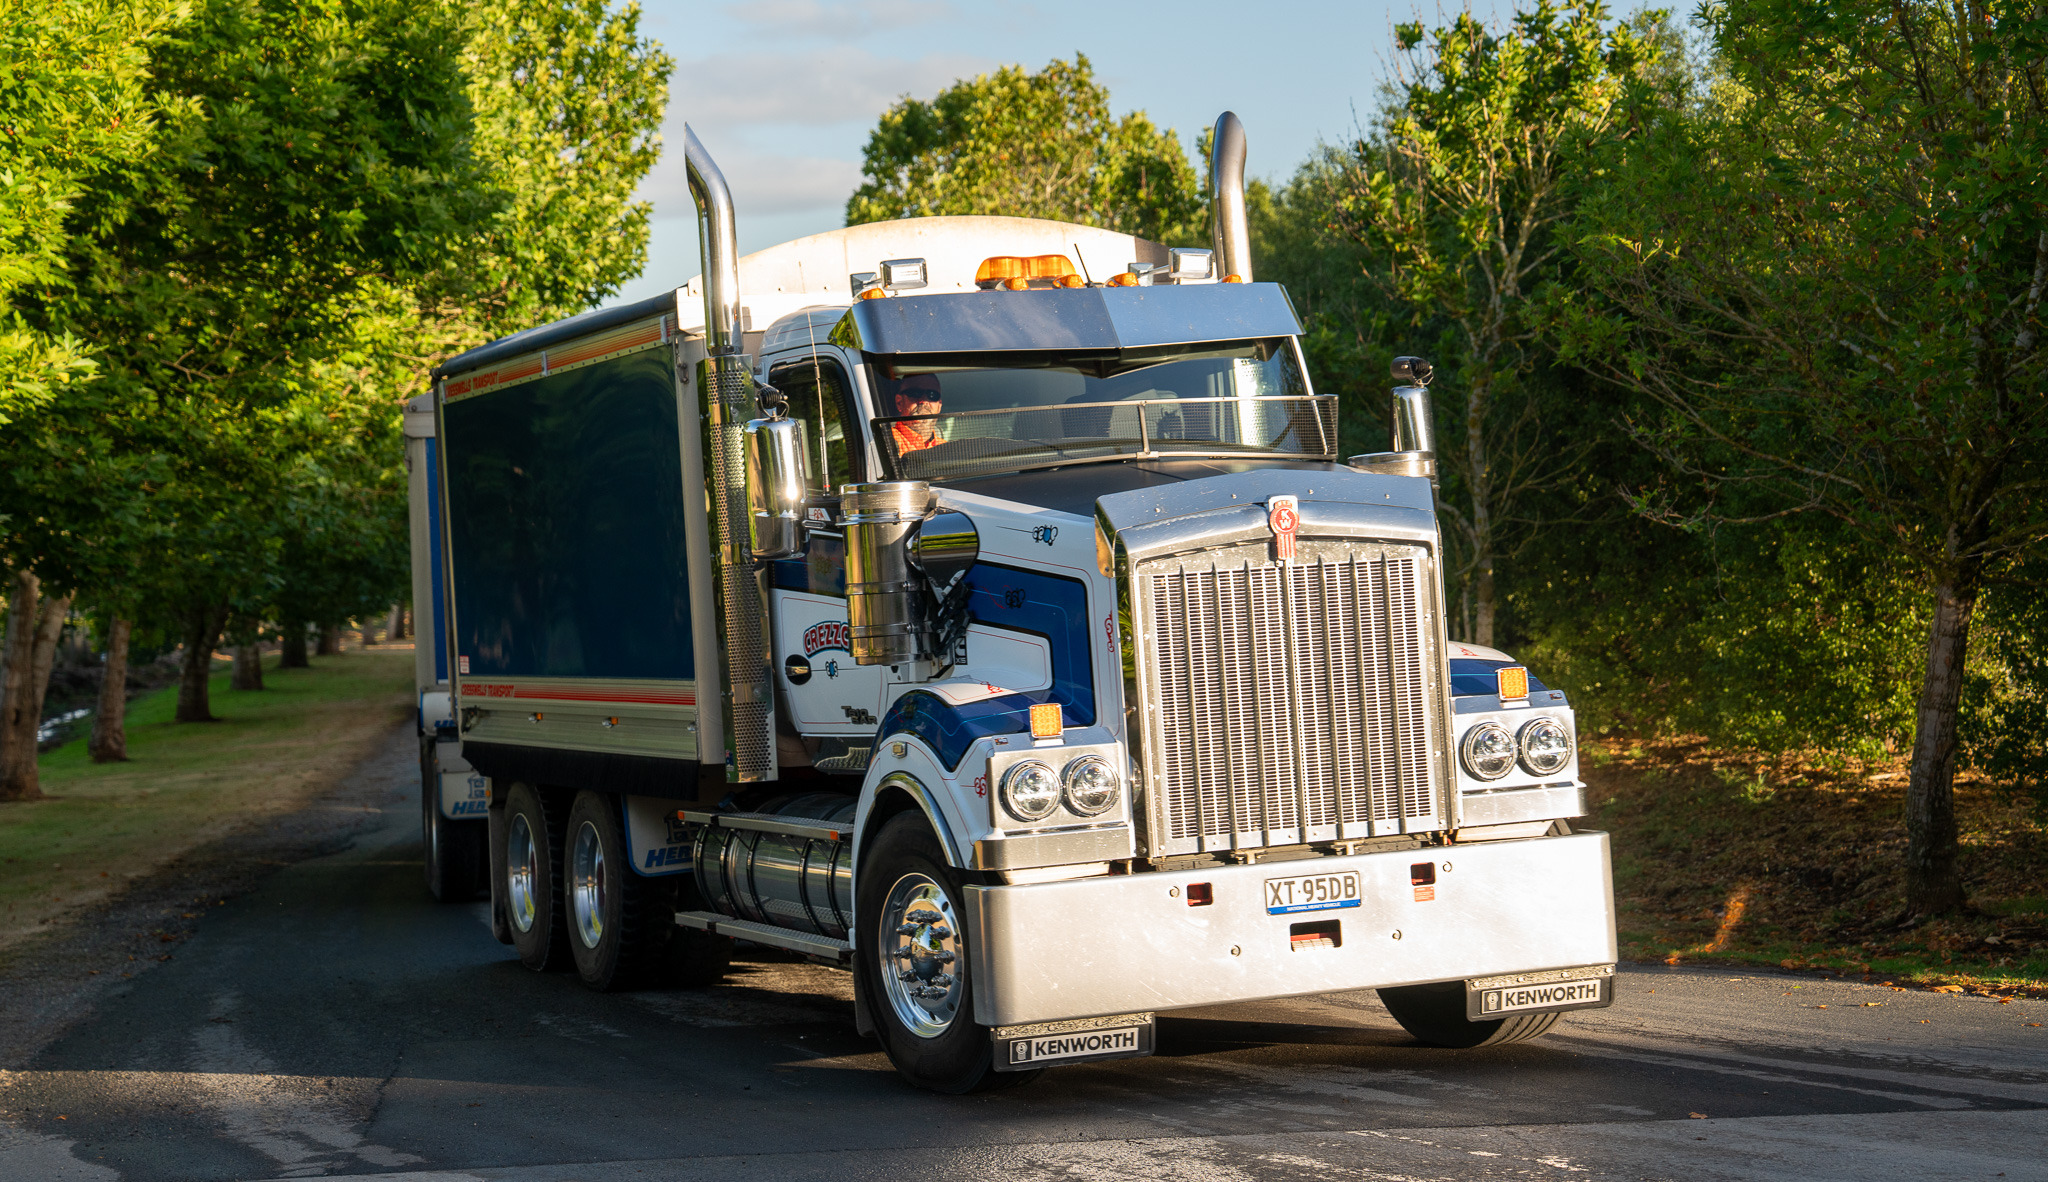
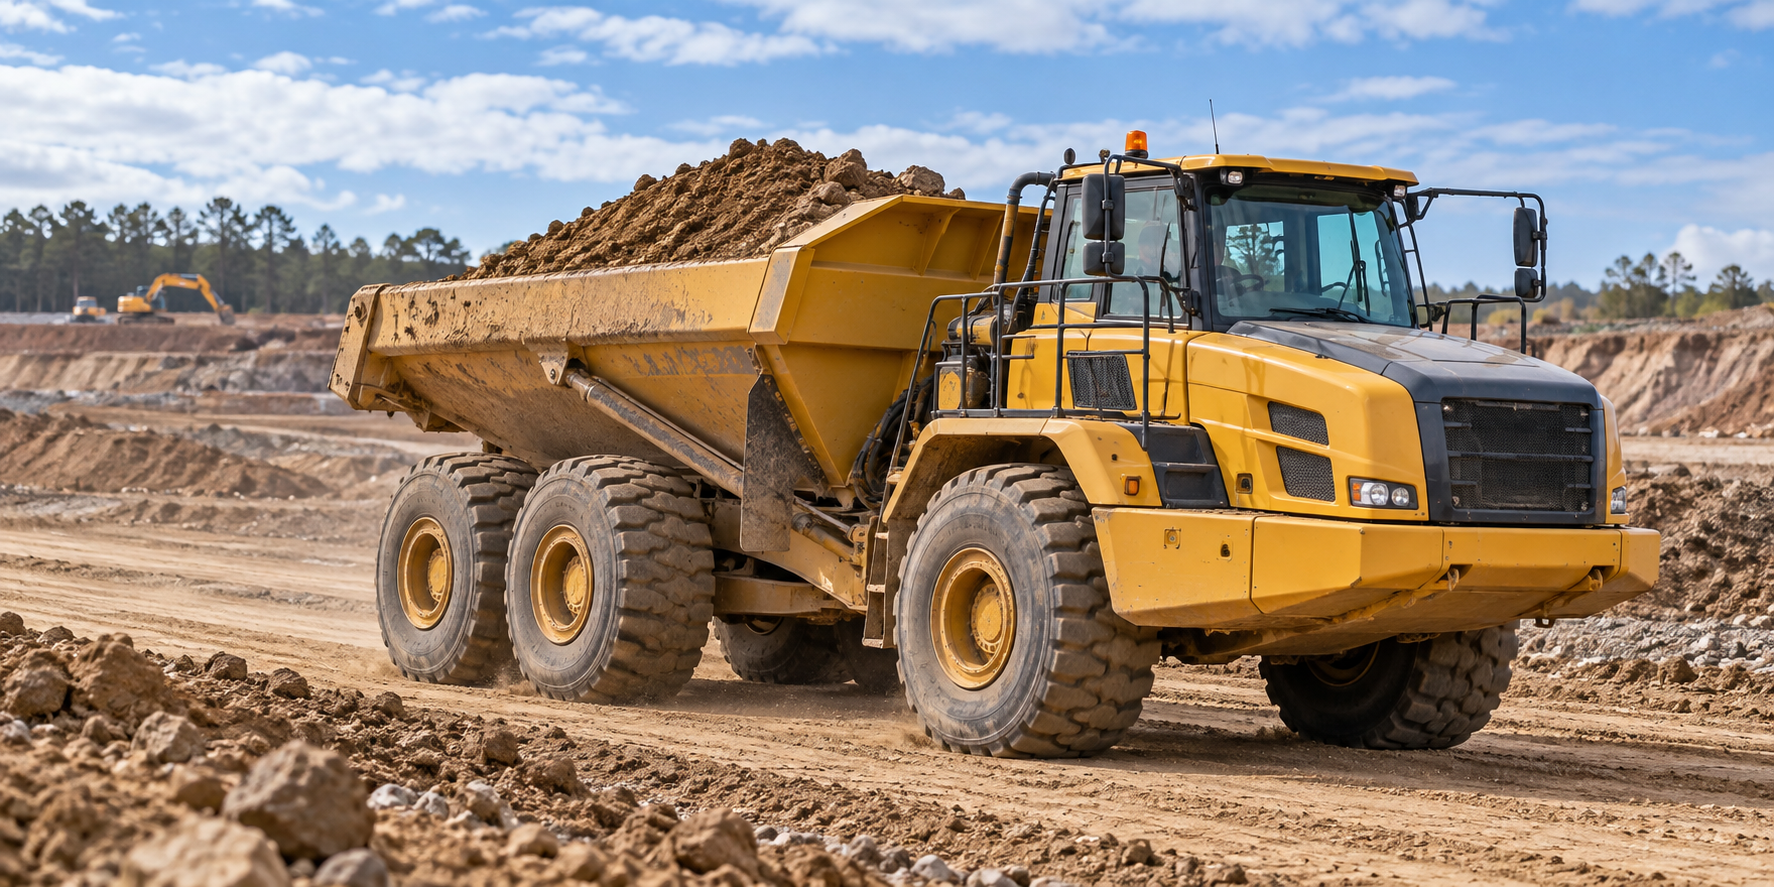
Crezzco bulk haulage trucks on the road
Now operating

From the projections to production

The crusher and screener contract is now operating, with the plant working towards its required production volumes. Crezzco’s bulk haulage operation is busy alongside it. Roughly six or seven truck and tipper-and-dog combinations have full-time drivers moving fertiliser, quarry products and other bulk loads around the region.

Crezzco’s fleet connects the work at the quarry to customers beyond the site. Trucks, trailers, loaders and work vehicles all make different demands on the funding position. MFG continues to help with suitable new and used purchases, including dealer and private-sale transactions, while keeping lender exposure and available lines in view.

Crezzco owns its own quarry. Jesse plans to move the crusher and screener equipment there when the current contract finishes, so the business can produce and supply material from its own site. That is the next plan, rather than an outcome already completed.

One purchase, several funding decisions.

MFG arranged finance for selected equipment alongside the principal acquisition funding, with a view of commitments across the wider business.

Forecast the whole operation.

Three-way projections gave lenders a view of profit and loss, cash flow and balance sheet as Jesse took over the business and mobilised roughly $2 million in new crusher and screener plant.

Keep the next move visible.

We maintain a view of lender exposure and discuss future purchases with Jesse. Possible overdraft and debtor funding remain conversations, not facilities already put in place.

Taking on a new contract or a bigger fleet?

Talk to us about it
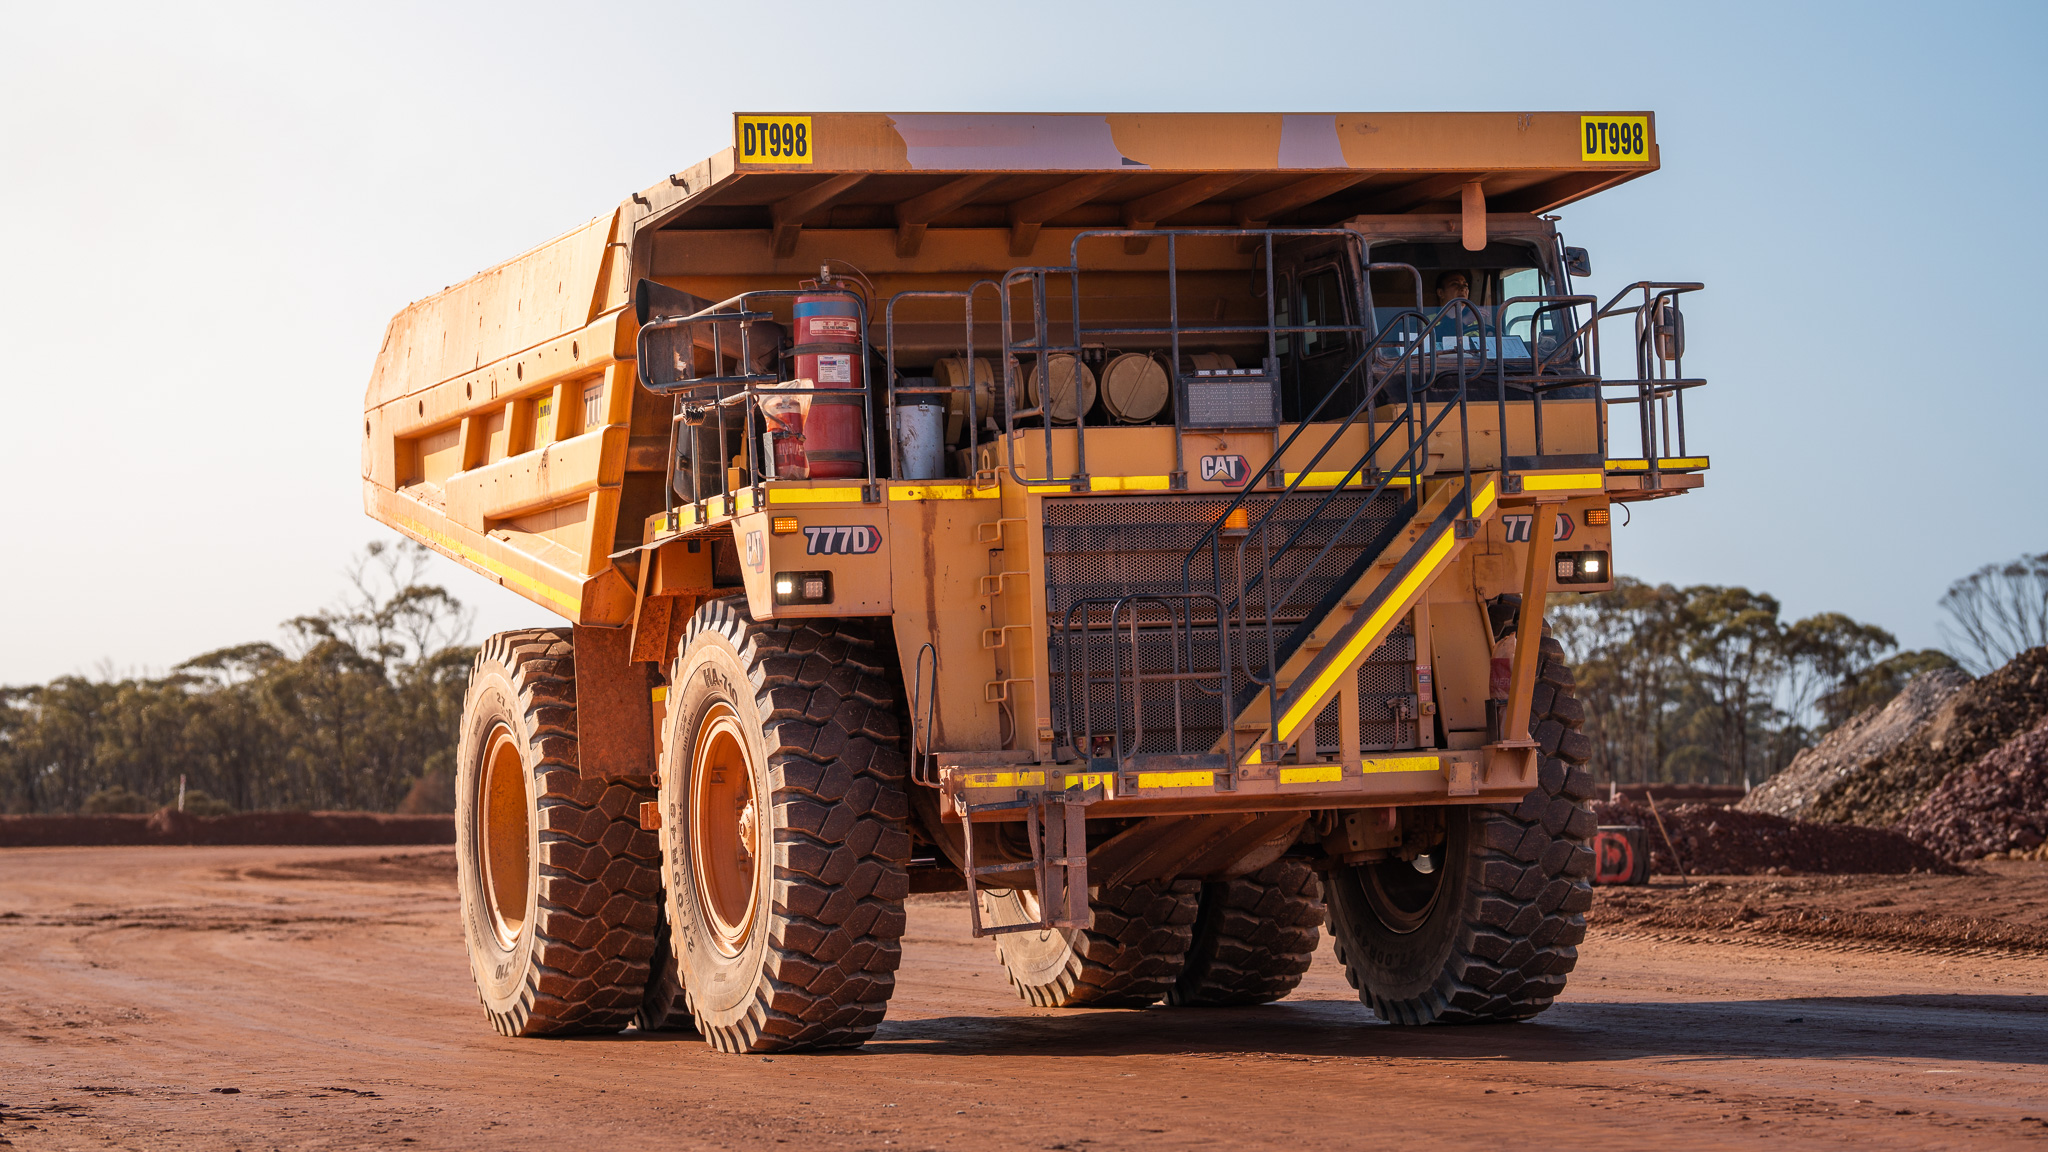
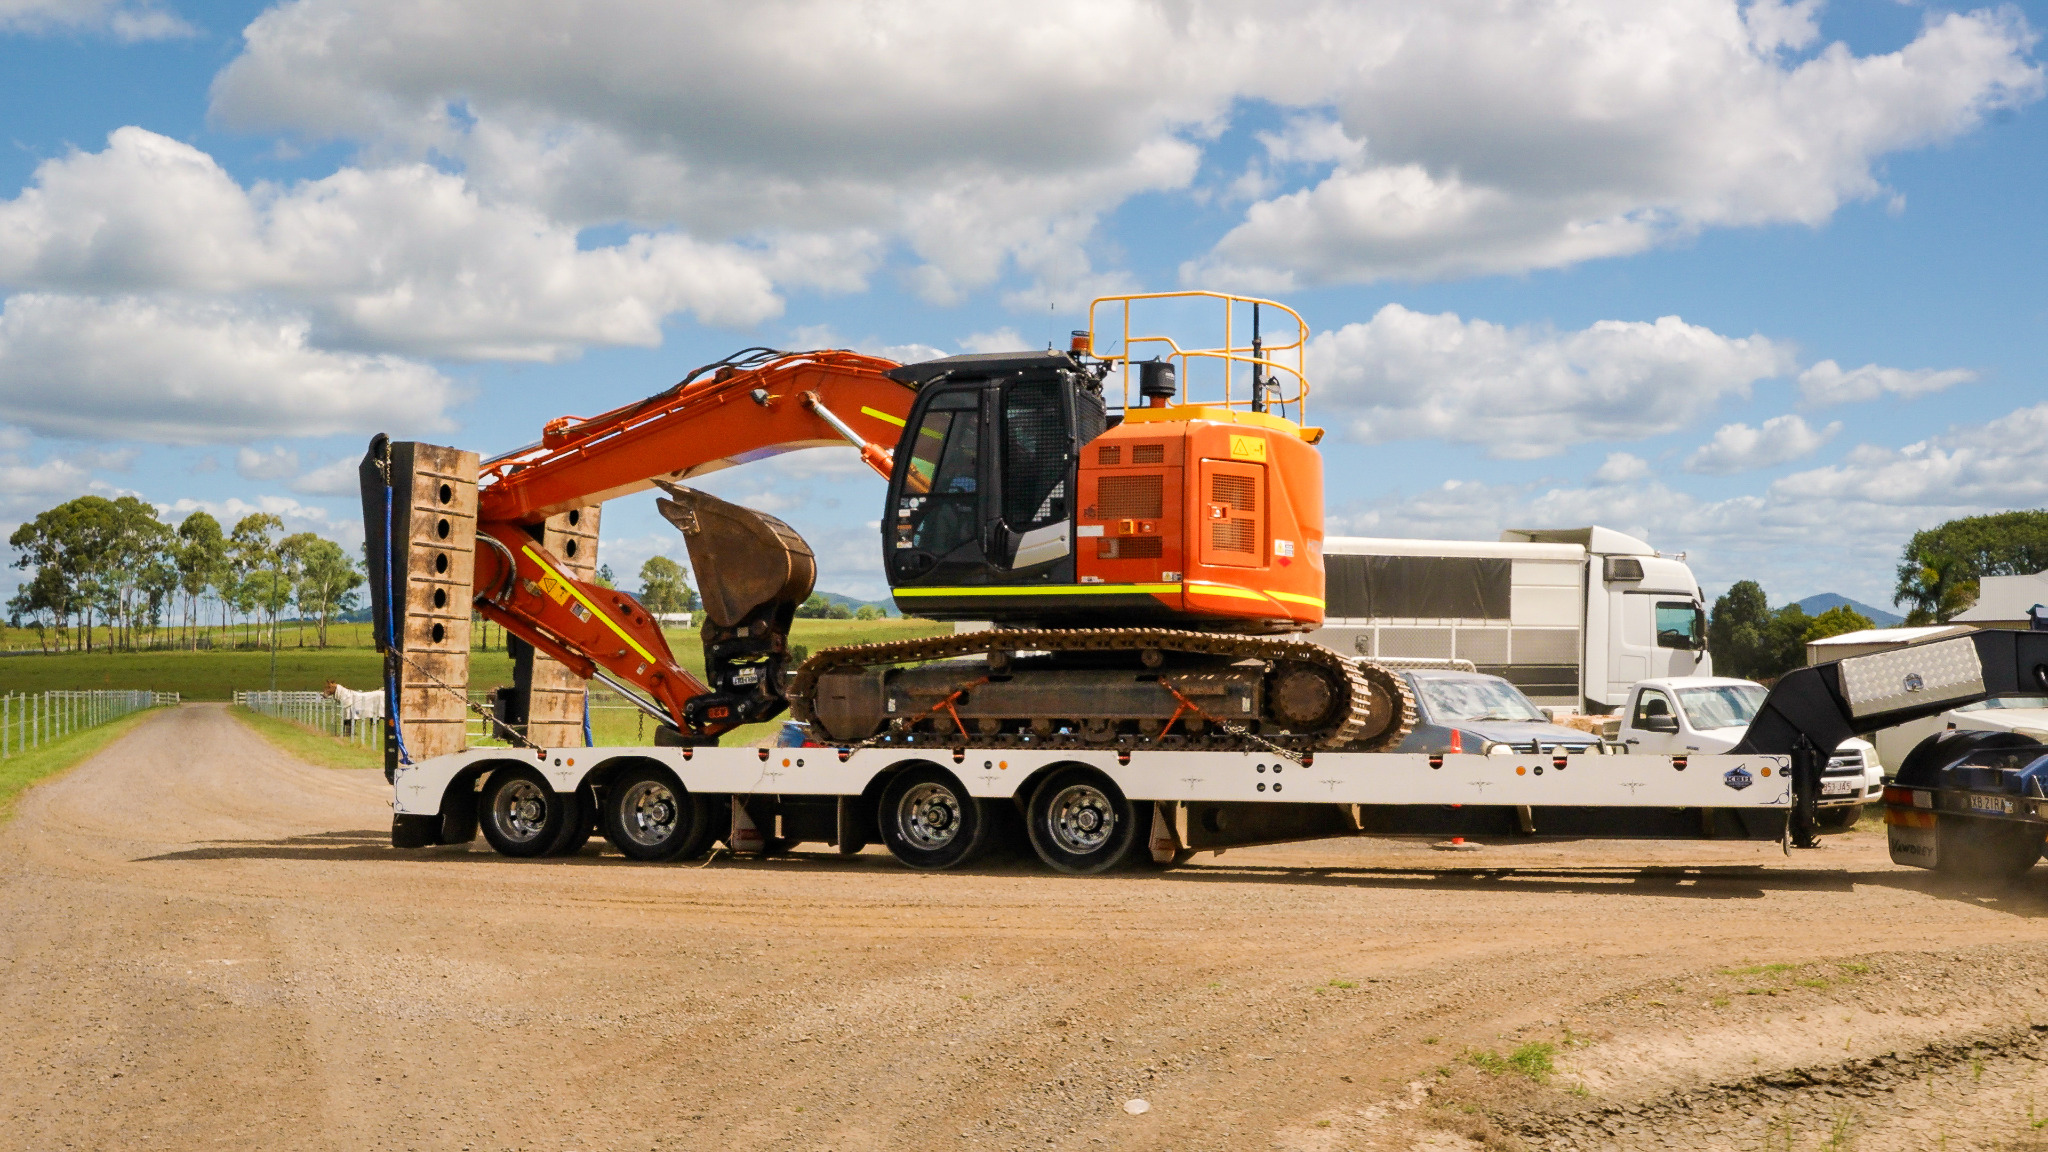
Crezzco haulage truck

Any make. Any model. Equipment for your fleet.

MFG can help finance any earthmoving or mining asset in your fleet, from small machines to large production equipment.

The machine and the attachments

GPS and machine control, blades, rippers, stick rakes, spears, hammers, tilt rotators, grabs, upgraded buckets and other aftermarket attachments.

Dealer, private sale or auction. New or used, any age or condition, run the purchase past us. We’ll assess the equipment and lender options with you.

Komatsu
John Deere
CASE
Volvo
Liebherr
Hitachi
Kobelco
Develon
SANY
XCMG
Any age
Any asset
Any model

Browse the full list of equipment we finance, even if it’s not listed here.

Browse the full asset list
Wheel Loader FinanceSkid Steer FinancePosi-Track FinanceBackhoe FinanceTrencher FinanceRoller FinanceCompactor FinanceEarthmoving Attachment FinanceArticulated Dump Truck FinanceRigid Dump Truck FinanceTipper Truck FinanceVacuum Truck FinancePipe Welder FinancePipe Layer FinanceScraper FinanceTrack Loader FinanceTelehandler FinanceCompact Track Loader FinanceMini Excavator FinanceWheeled Excavator FinanceLong-Reach Excavator FinanceRock Breaker FinanceAuger FinanceExcavator Bucket FinanceGrading Blade FinanceSoil Stabiliser FinanceAsphalt Paver FinanceConcrete Pump FinanceMobile Crushing Plant FinanceScreening Plant FinanceSite Service Truck FinanceLow Loader FinanceEquipment Float FinanceDrill Rig FinanceBlast Hole Drill FinanceExploration Drill FinanceRock Drill FinanceMining Haul Truck FinanceUnderground Loader FinanceConveyor FinanceStacker FinanceReclaimer FinanceMobile Crusher FinanceJaw Crusher FinanceCone Crusher FinanceImpact Crusher FinanceTrommel Screen FinanceWash Plant FinanceAggregate Plant FinanceFeeder FinanceExcavator Attachment FinanceMining Bucket FinanceWater Cart FinanceFuel Truck FinanceService Truck FinanceCrane Truck FinancePrime Mover FinanceSite Office FinancePortable Building FinanceLighting Tower FinanceGenerator FinanceCompressor FinanceMine-Spec Ute FinanceSite Vehicle FinanceCrew Bus FinancePersonnel Carrier FinanceWorkshop Hoist FinanceAerial Work Platform FinanceForklift FinancePump FinanceDewatering Pump FinanceDust Suppression Equipment FinanceWeighbridge Finance
James Allan and Daniel Salajan together on site

Get to know who you’re working with

Deal directly with James Allan and Daniel Salajan. With 35 years of combined experience across bank credit and broking, we help business owners finance the next purchase and plan for the fleet beyond it.

Talk to James and Dan ↗

See what a considered fleet plan can make possible.

When experience matters, see how we have worked with the people behind the equipment.

KBH Earthmoving team and equipment66+ equipment purchases to scale a family business.See more

KBH Earthmoving

The fleet plan in brief

  • Started with a used Cat grader in 2022 and grew into a whole-fleet finance relationship.
  • Mapped existing lender exposure and capacity before the next machine was needed.
  • Supported equipment purchases as the business expanded its civil fleet and concrete capability.
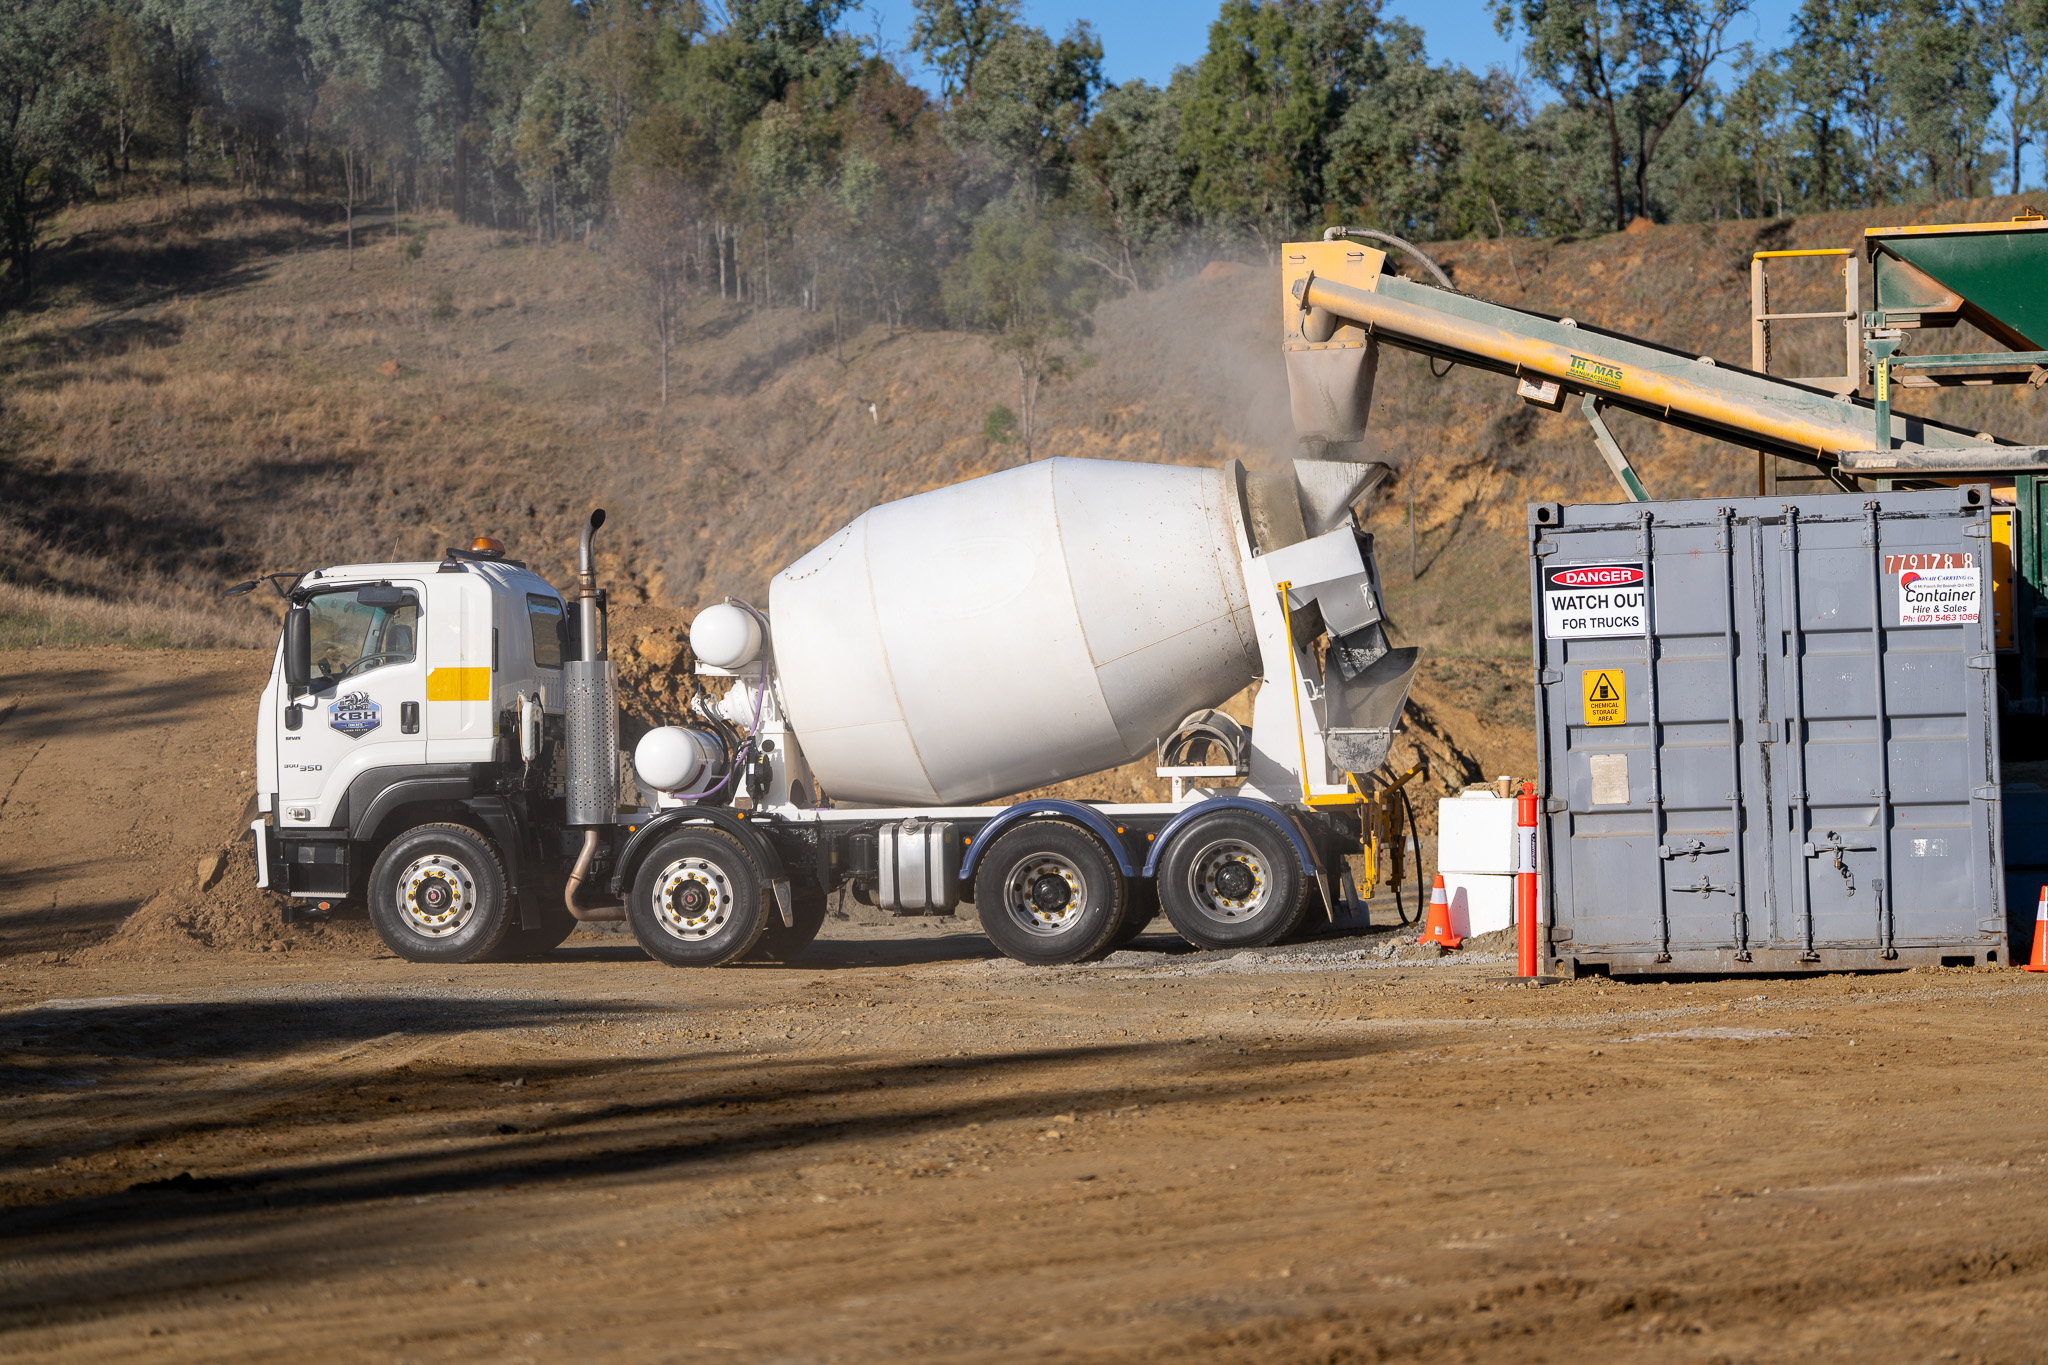
James Allan and Anthony Goetsch discussing KBH’s equipmentKBH mobile concrete batching plant and agitator truck
Crezzco team and equipmentFunding an acquisition and a new quarry contract.See more

Crezzco

The fleet plan in brief

  • Reviewed the equipment debt inside a business acquisition, rather than treating the fleet as one funding decision.
  • Arranged roughly $2 million for crusher and screener equipment to support new quarry work.
  • Considered lender spread and future capacity as the haulage and quarry operation developed.
James and Jesse reviewing the operationCrusher and screener plant processing quarry material
LEH Equipment team and equipmentFrom start-up to three dozers in three years.See more

LEH Equipment

The fleet plan in brief

  • Assessed the first D3 against Brock’s existing business and the hire work he expected it to win.
  • Considered specialist attachments and the next purchases as the business found new markets.
  • Built lender history while keeping other funding options available for future equipment.
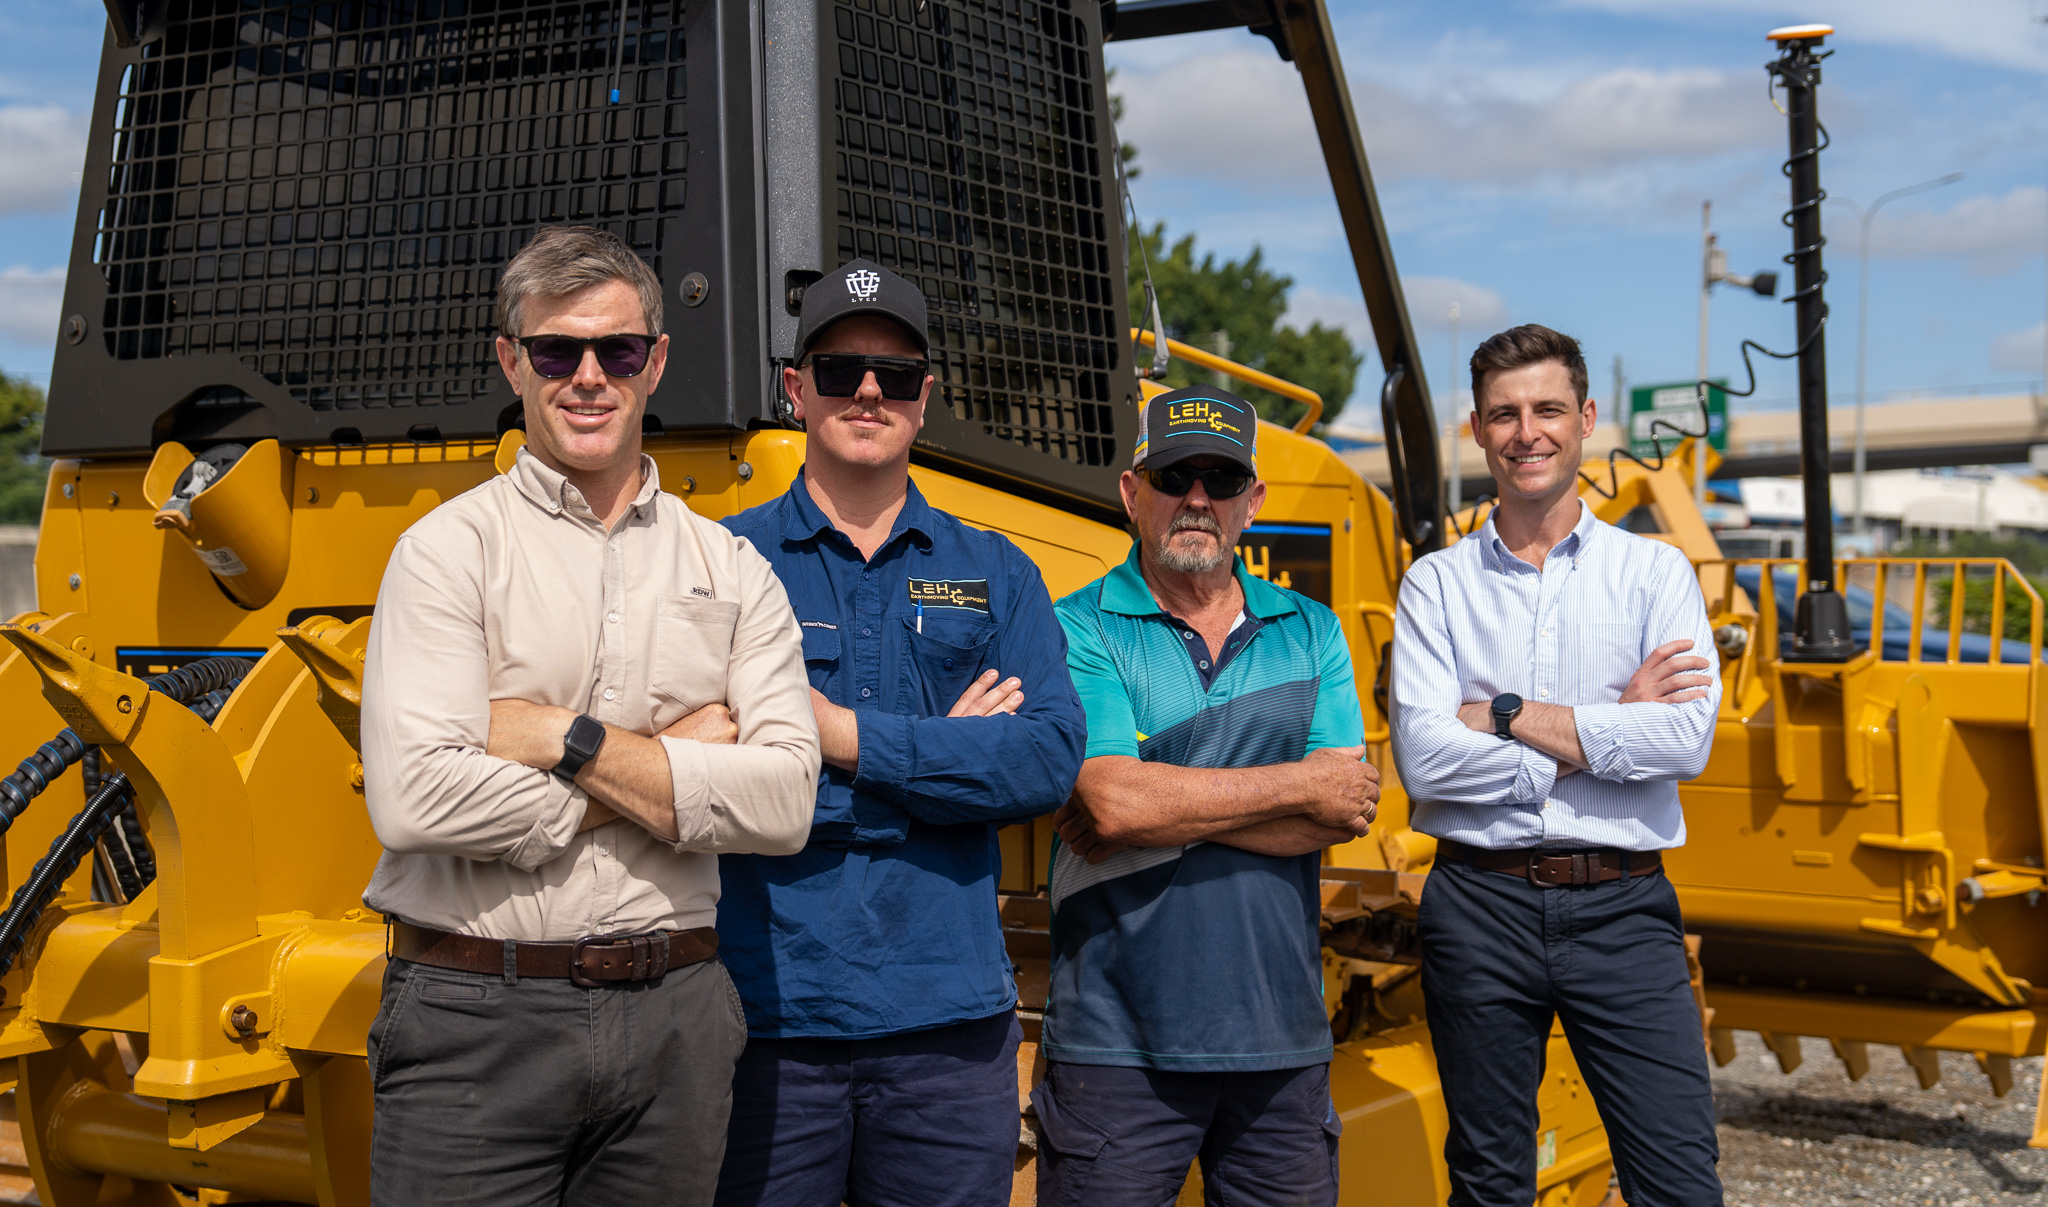
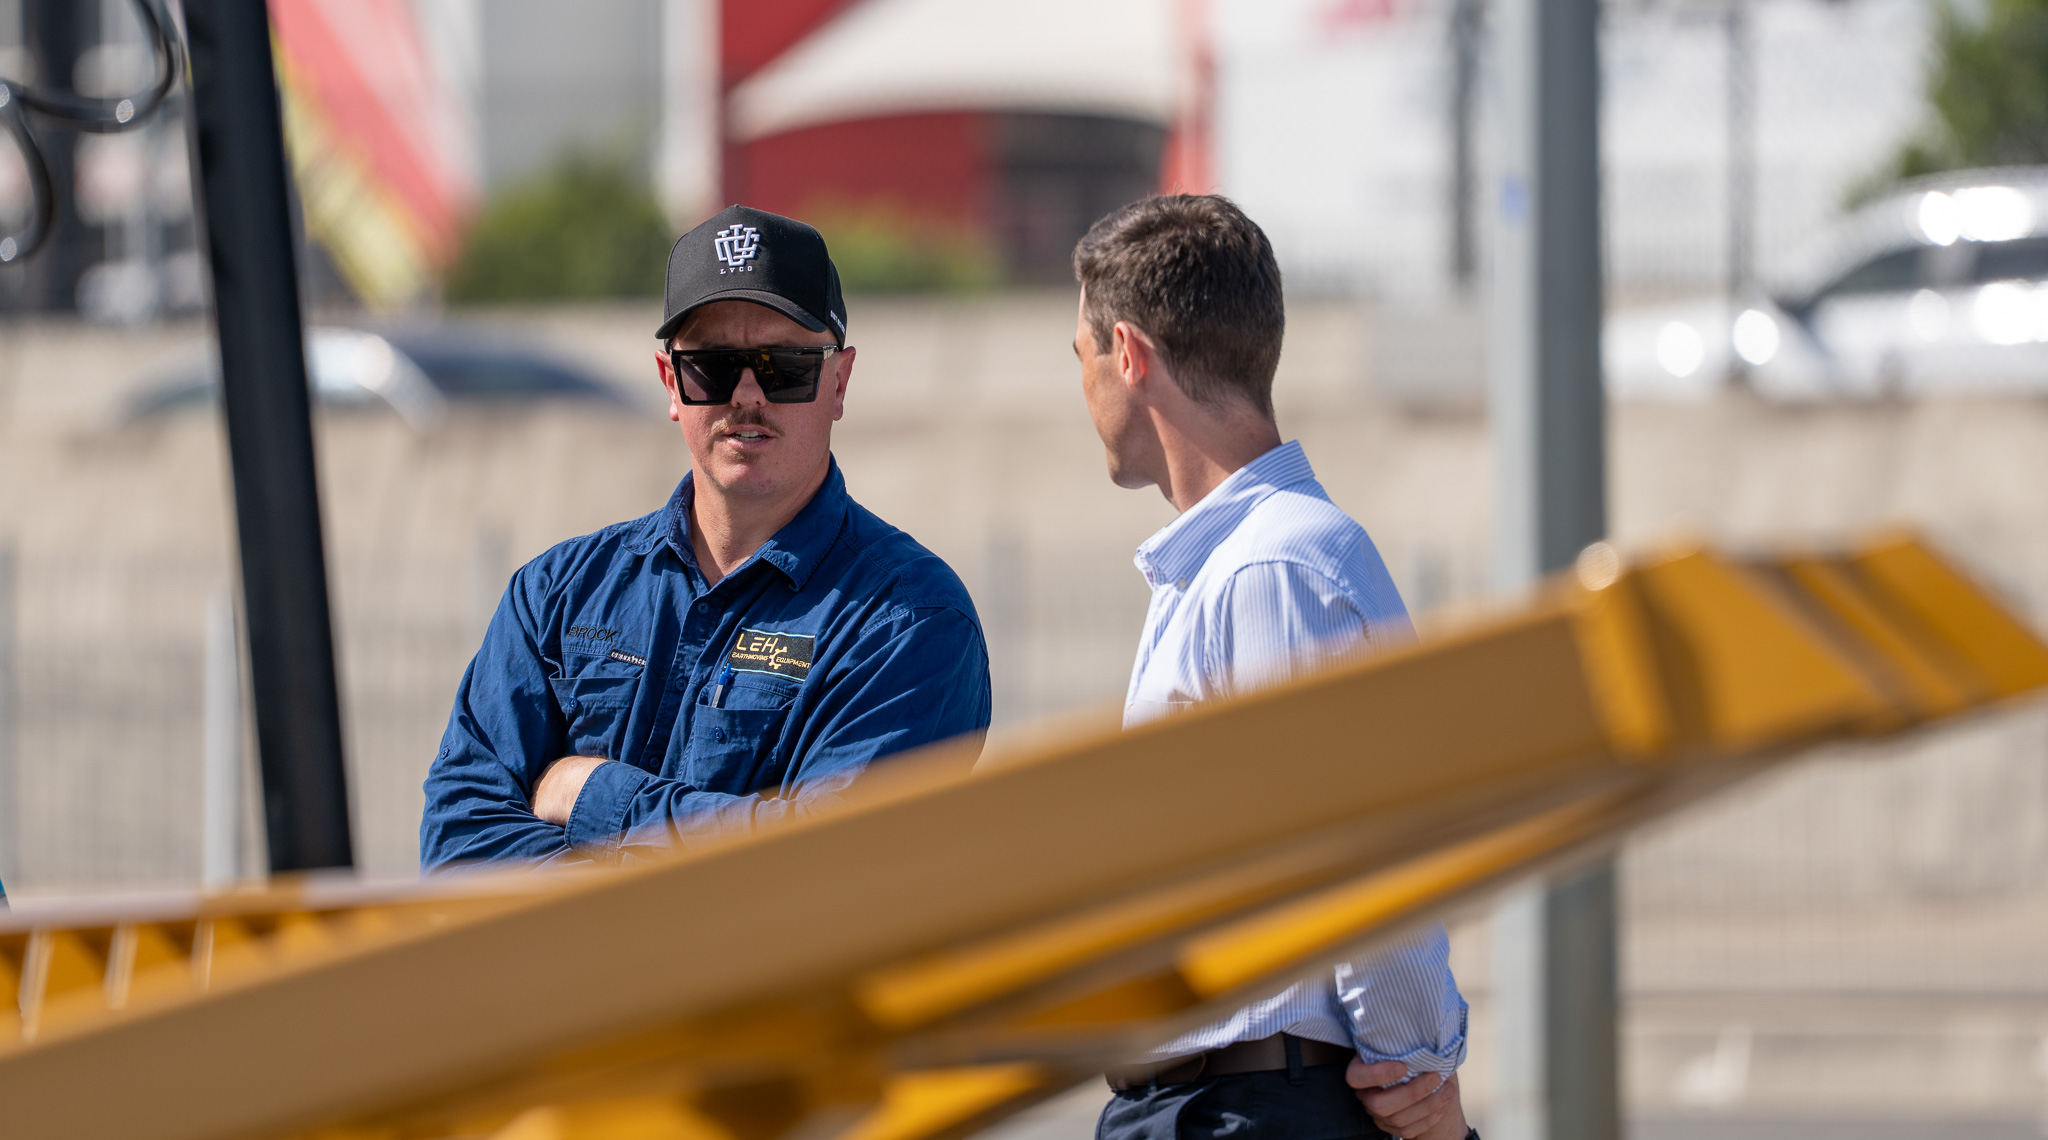
James Allan speaking with Brock HarveyBrock and James beside LEH equipment
Tumeke Civil team and equipmentSeven new Kobelcos to update an ageing fleet.See more

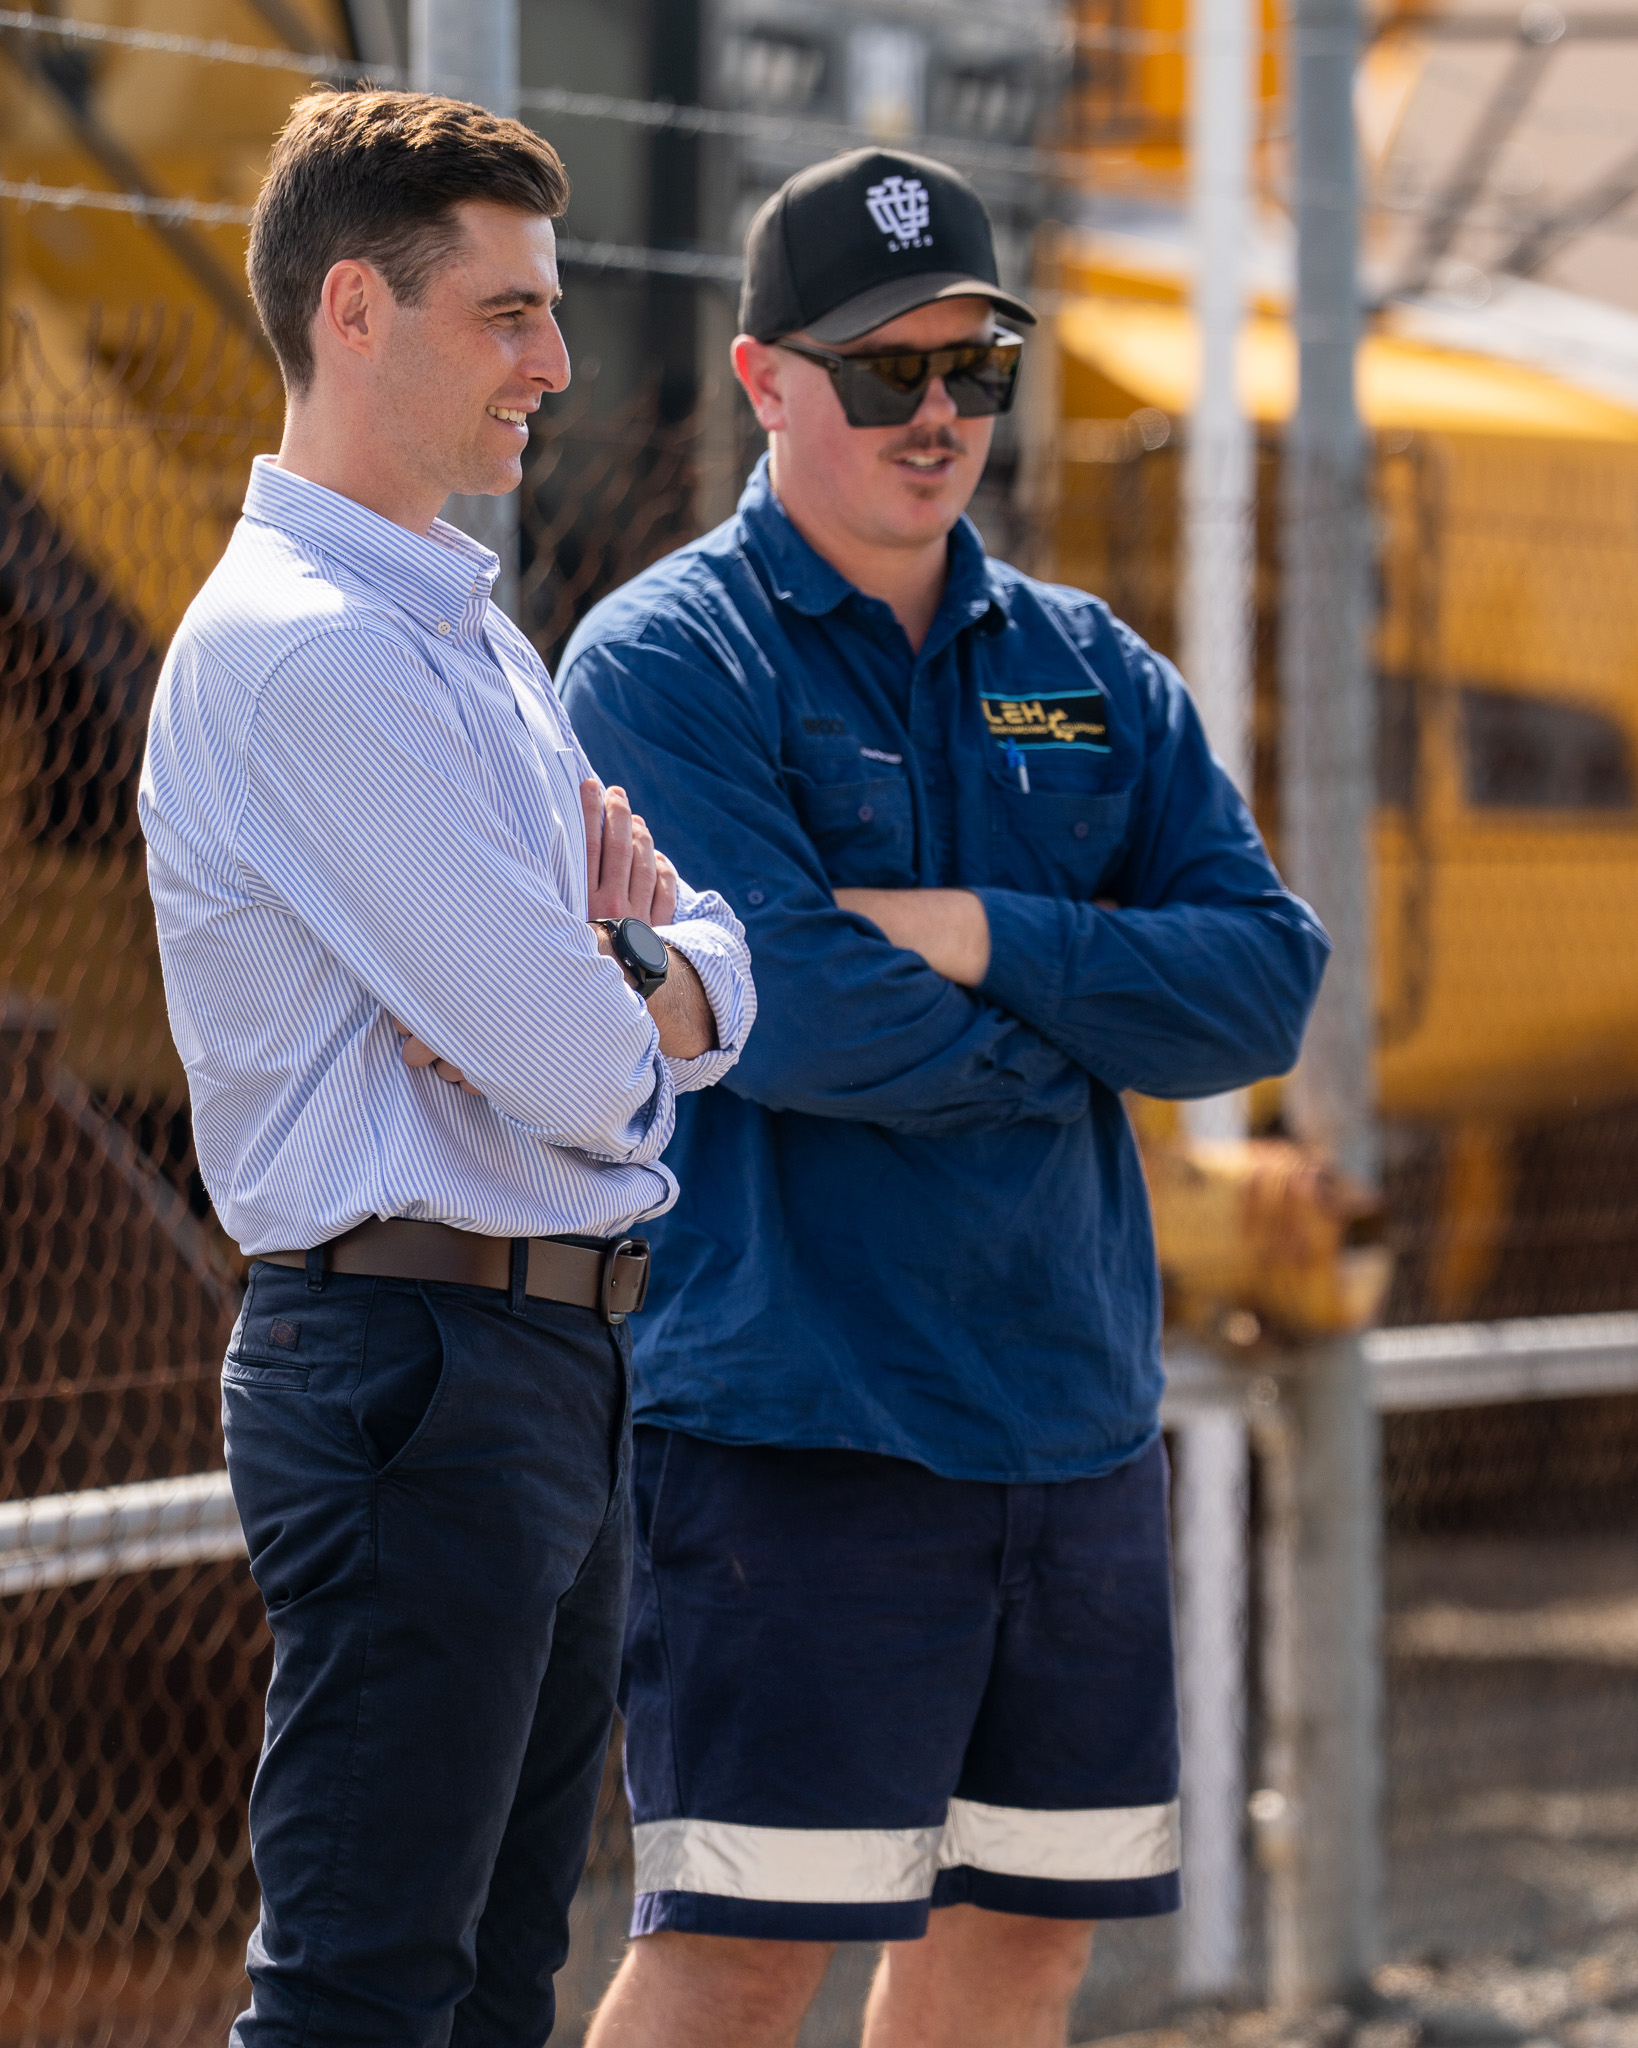
Tumeke Civil

The fleet plan in brief

  • Mapped the debt, payouts and trade values on the existing excavators before choosing replacements.
  • Coordinated a staged rollout with Brisvegas Machinery, including GPS and attachments where required.
  • Timed trades and new deliveries so the fleet could keep working while older machines were replaced.
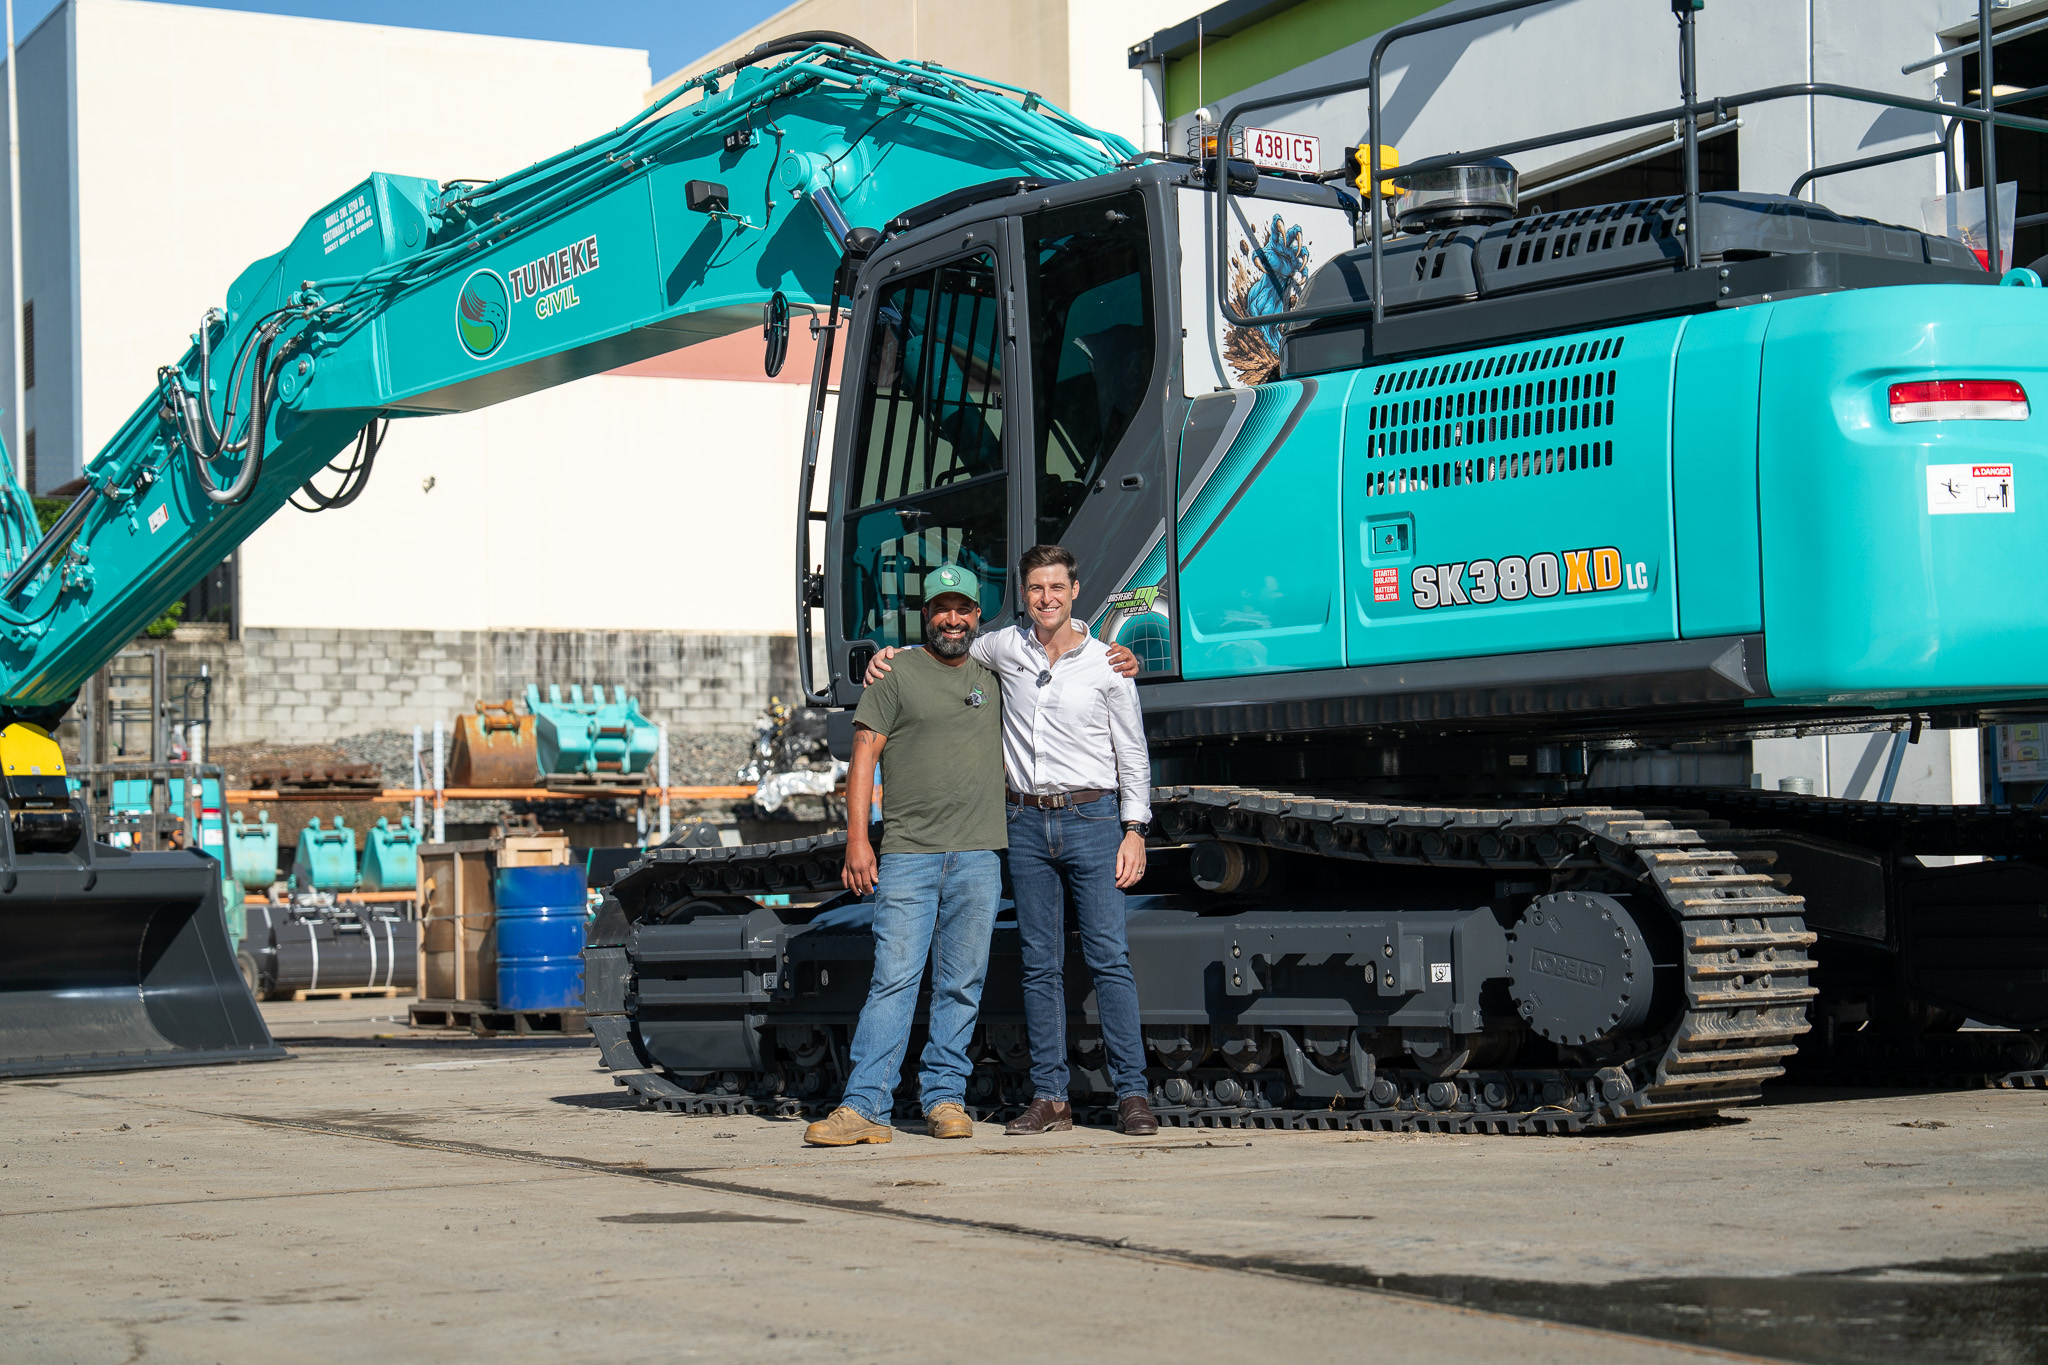
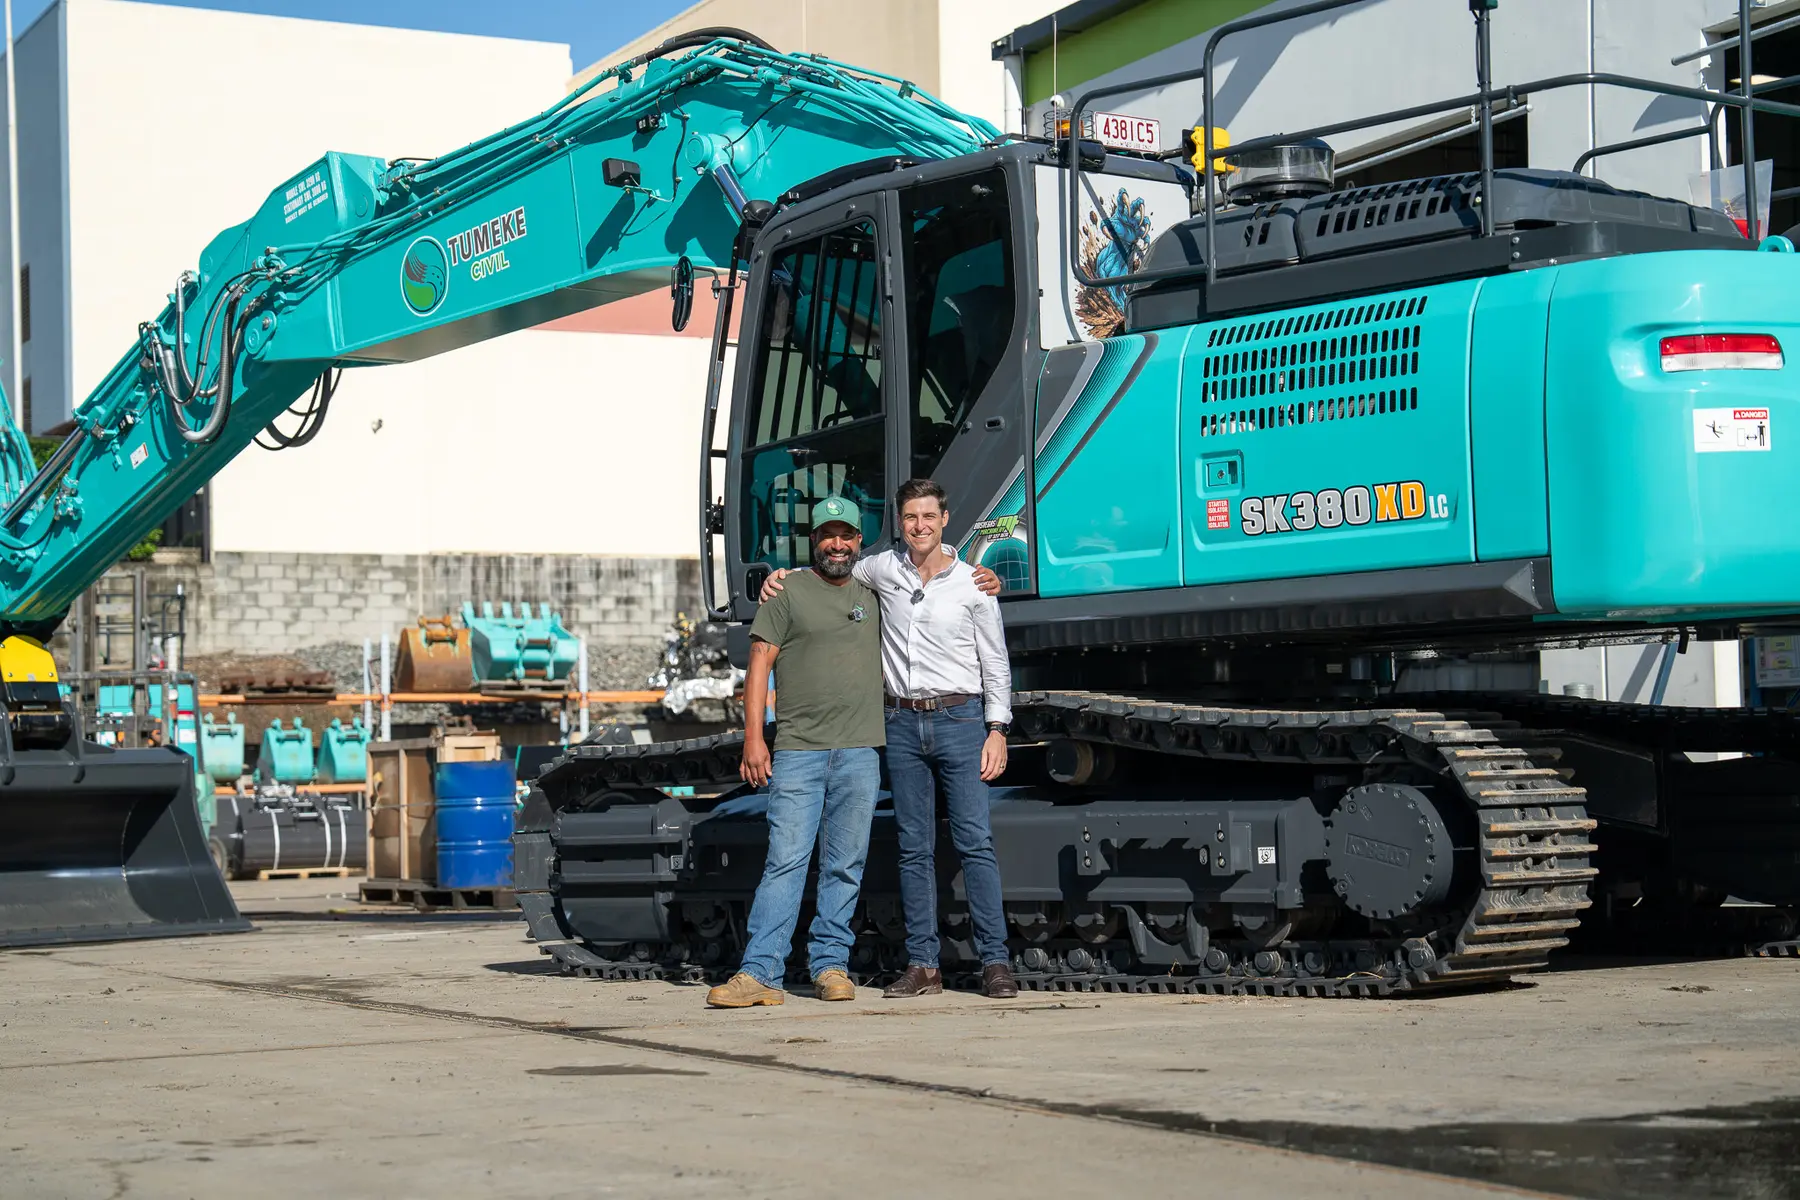
Tumeke Civil at workTony Rore and James Allan beside a new Tumeke Civil Kobelco
Mineral Mining Services team and equipmentMore than 200 civil and mining assets financed over 10 years.See more

Mineral Mining Services

The fleet plan in brief

  • Started with a water cart in 2016 and a clear schedule of the fleet and existing finance.
  • Established an initial $1.8 million master limit as the purchase program grew.
  • Now manages $50 million in master limits, with lender placement planned around larger purchases and future tenders.
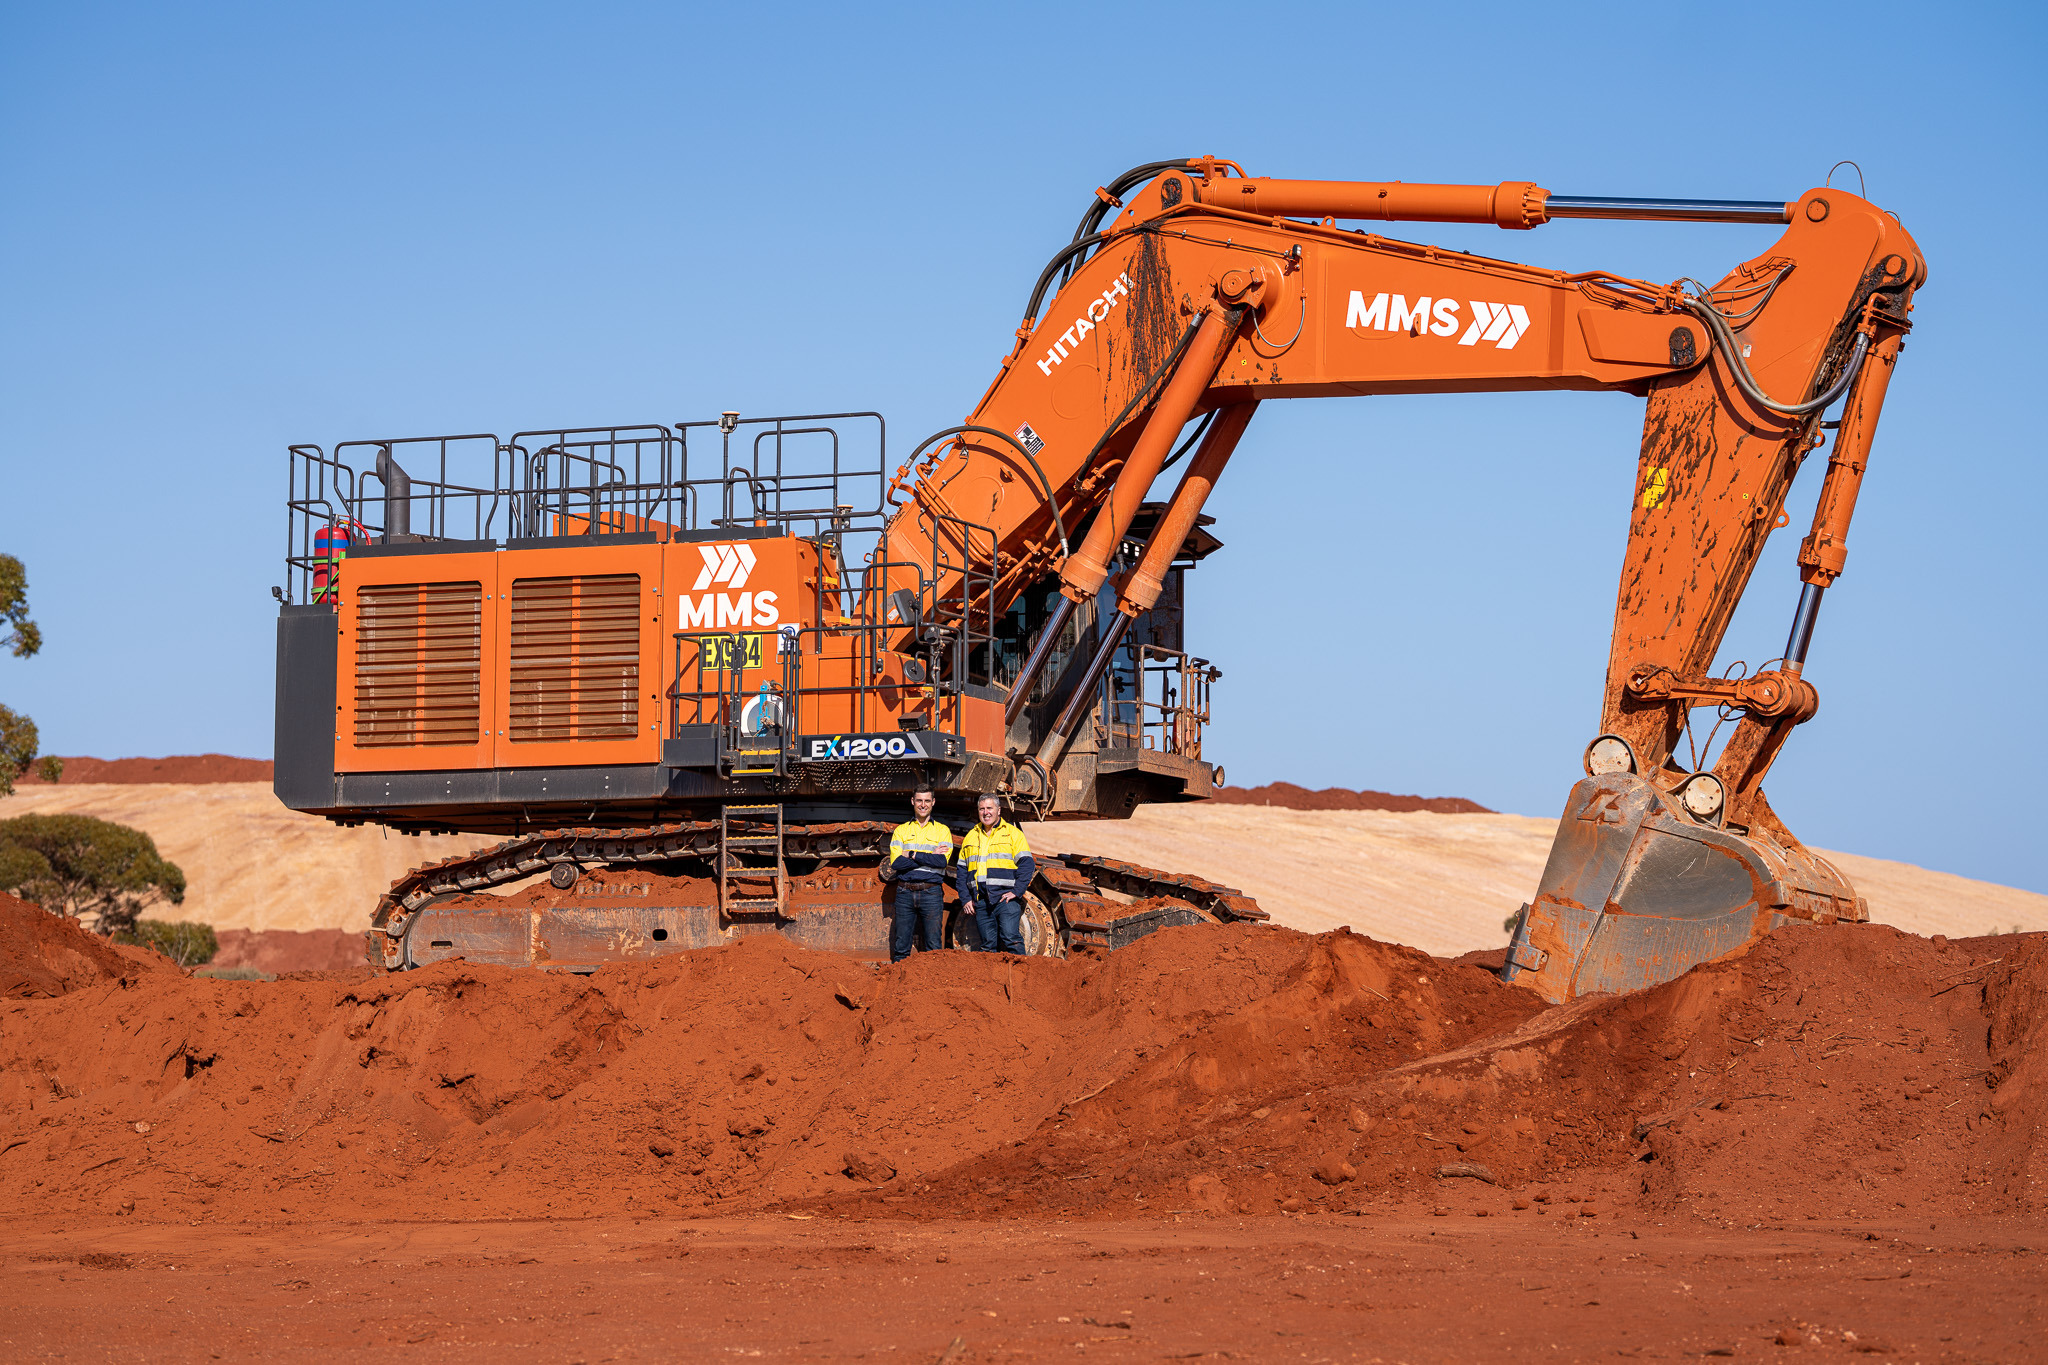
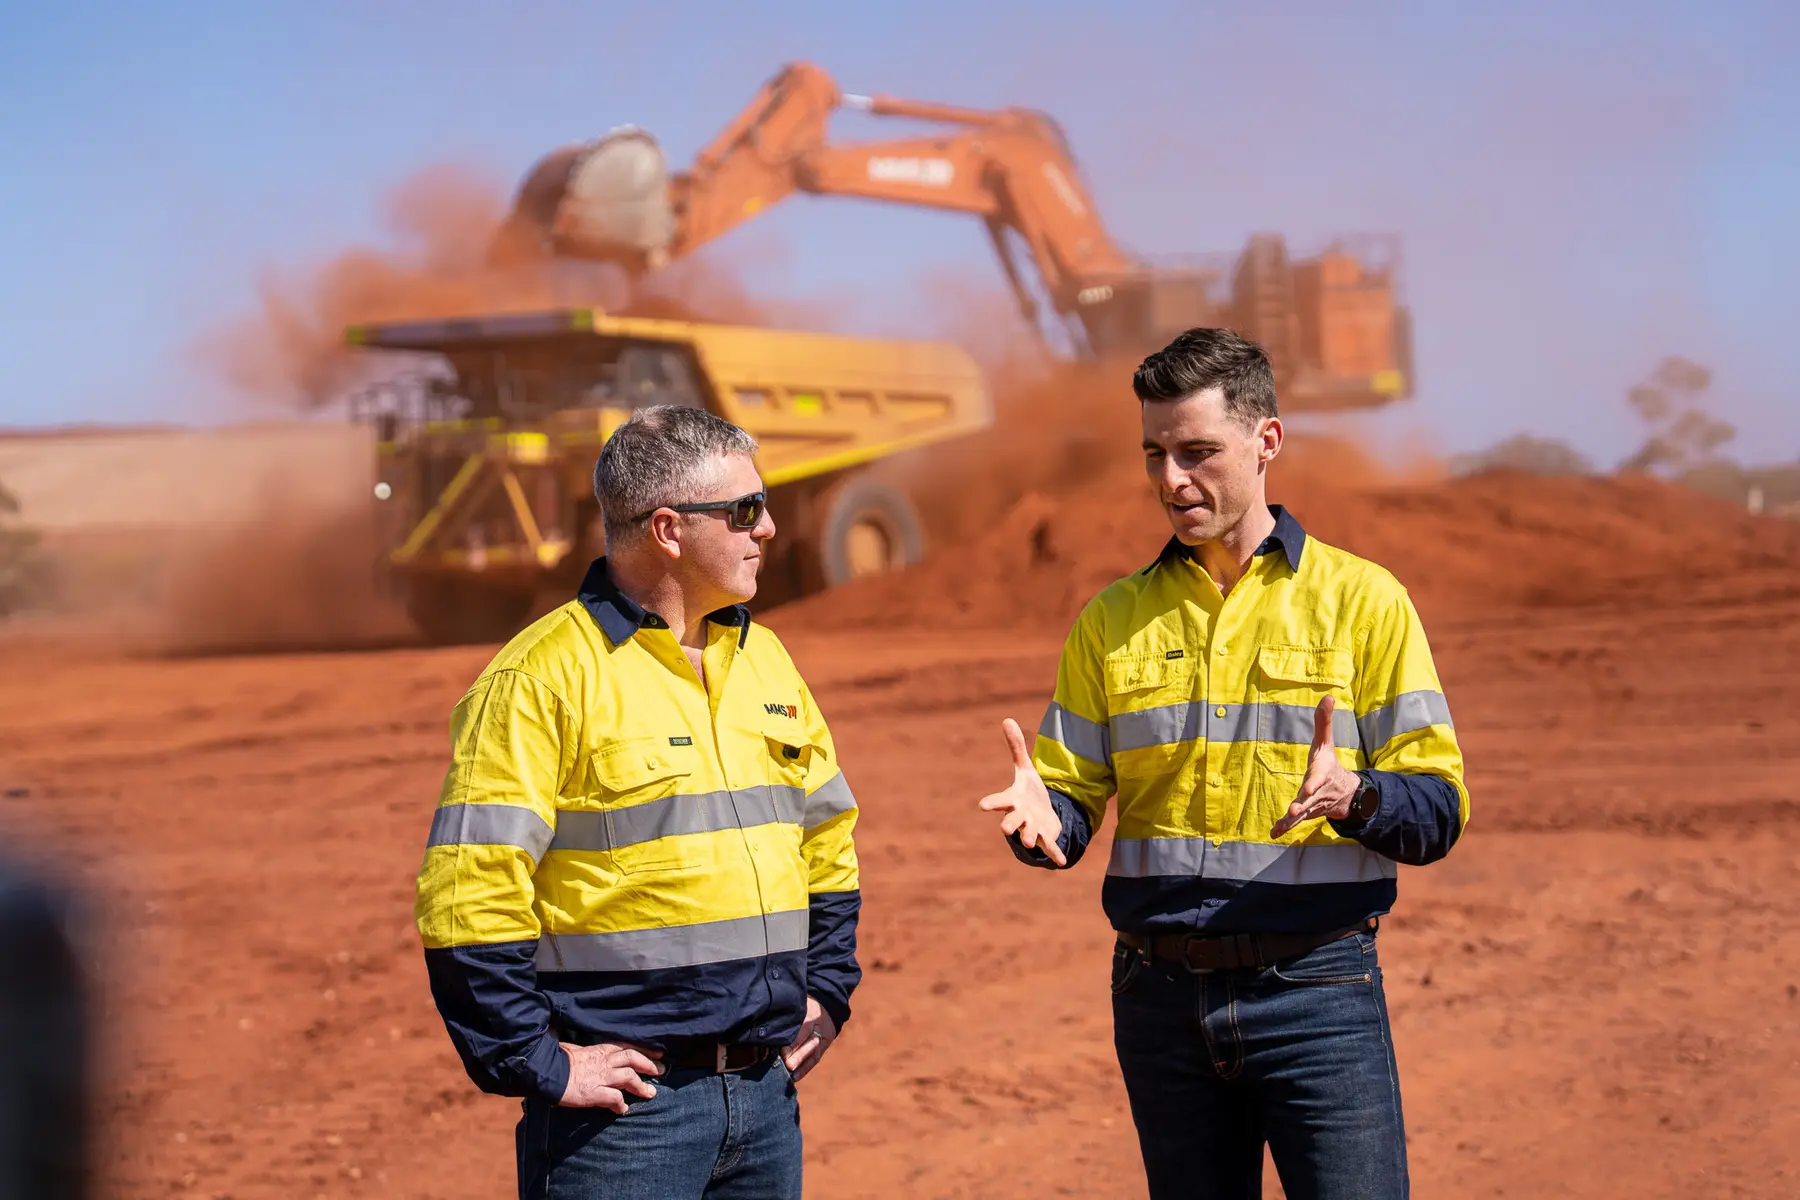
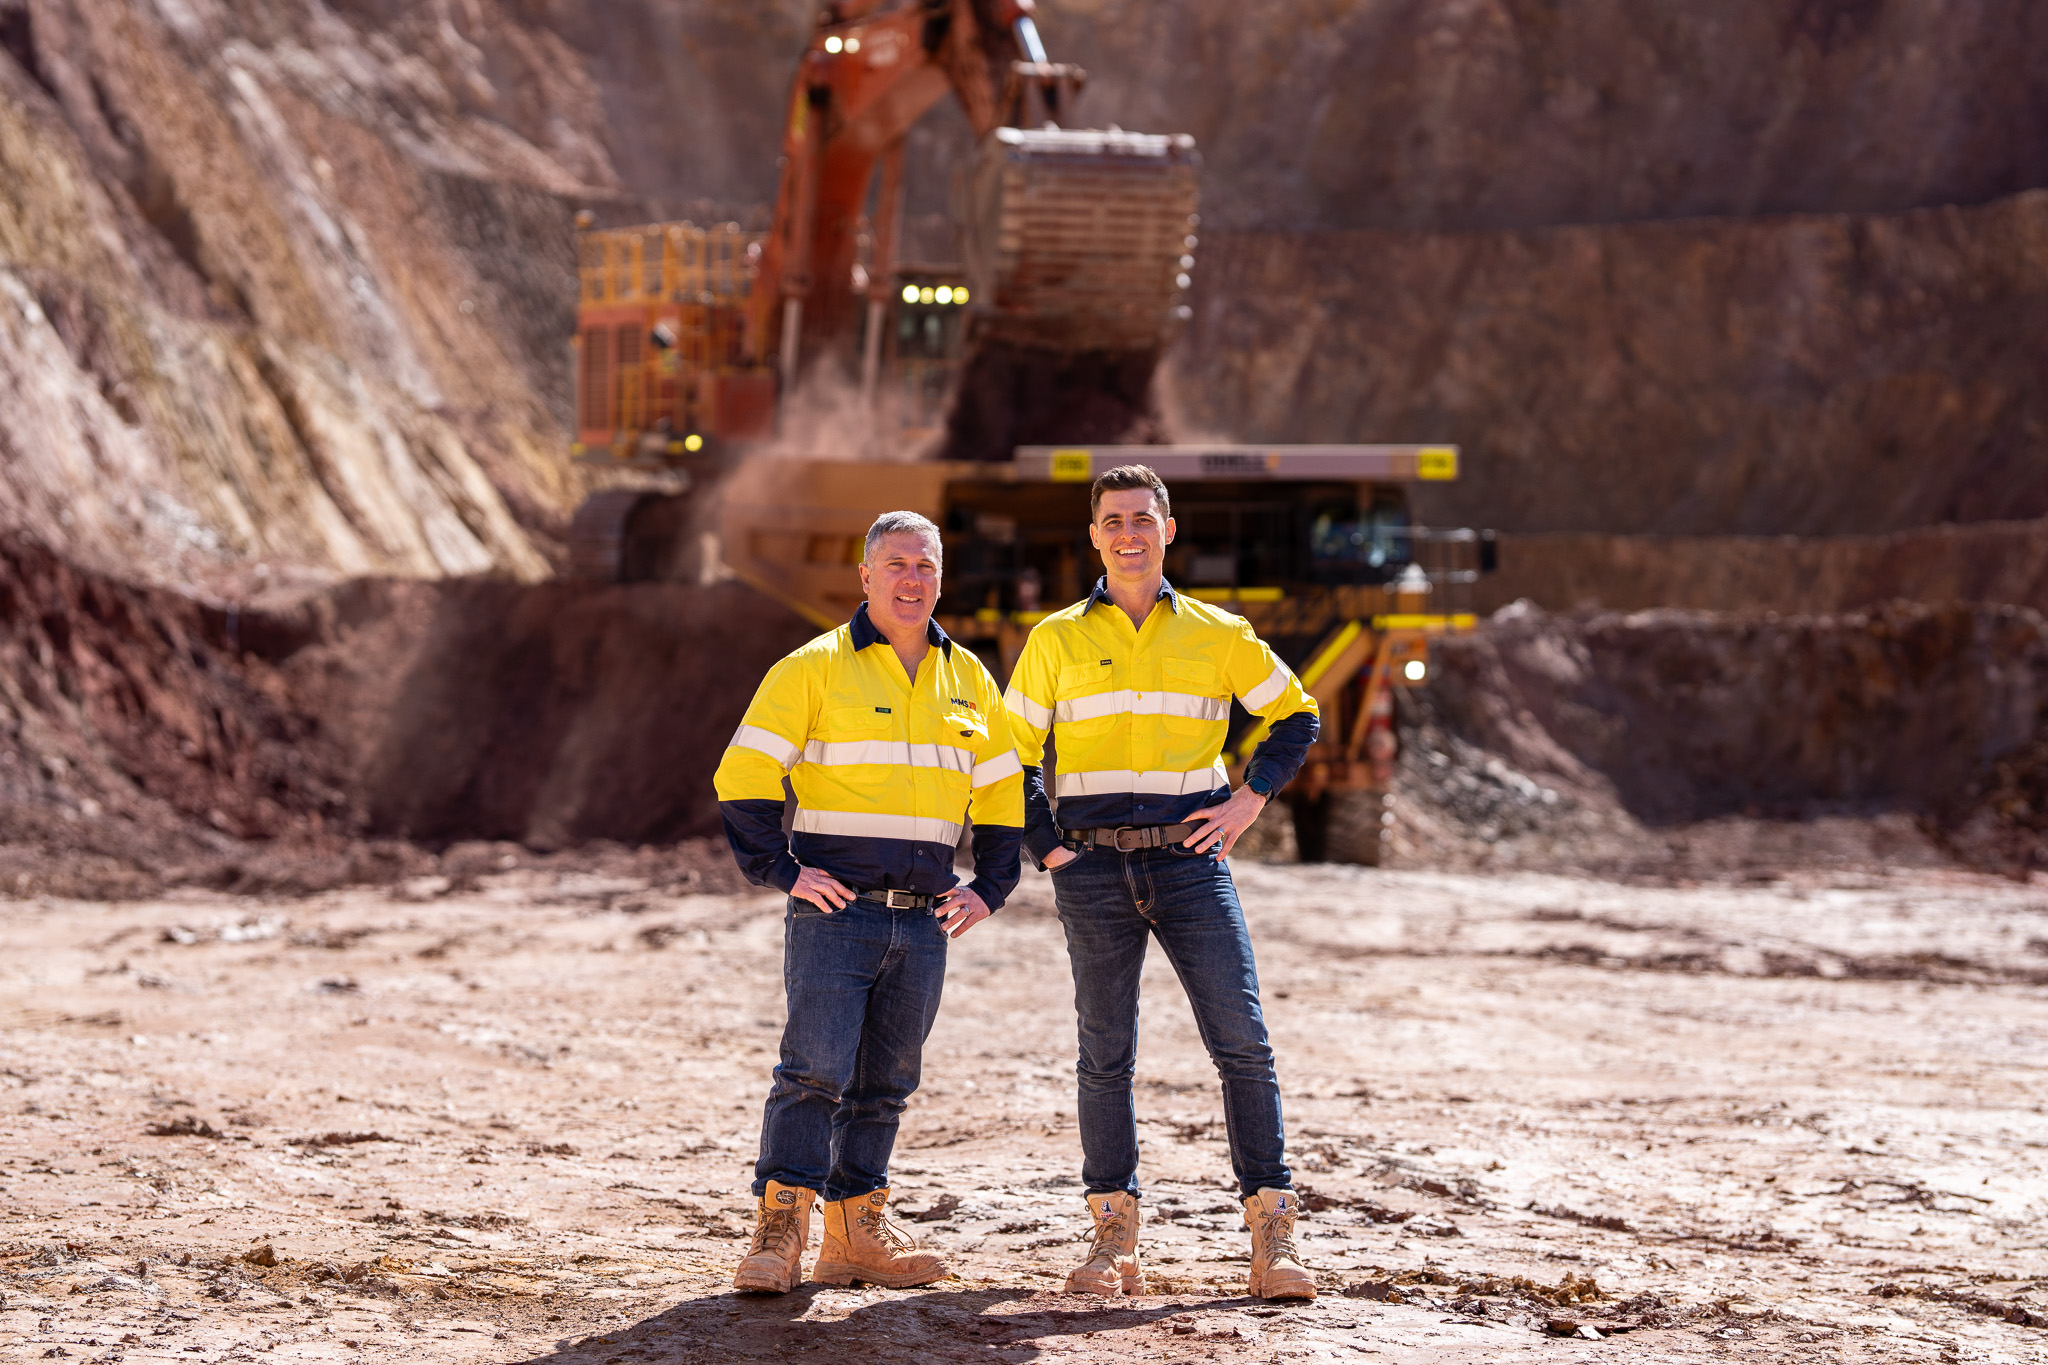
MMS and MFG representatives at the mining operationMMS mining dump truck on site
HRV Earthmoving team and equipmentGraders, dozers, utes and a float with major banks.See more

HRV Earthmoving

The fleet plan in brief

  • Reviewed the fleet, existing repayments and available lender capacity.
  • Coordinated older-machine sales with RDW and finance for newer Caterpillar equipment.
  • Planned the changeovers around working machines and contracts across Victoria and Western Australia.
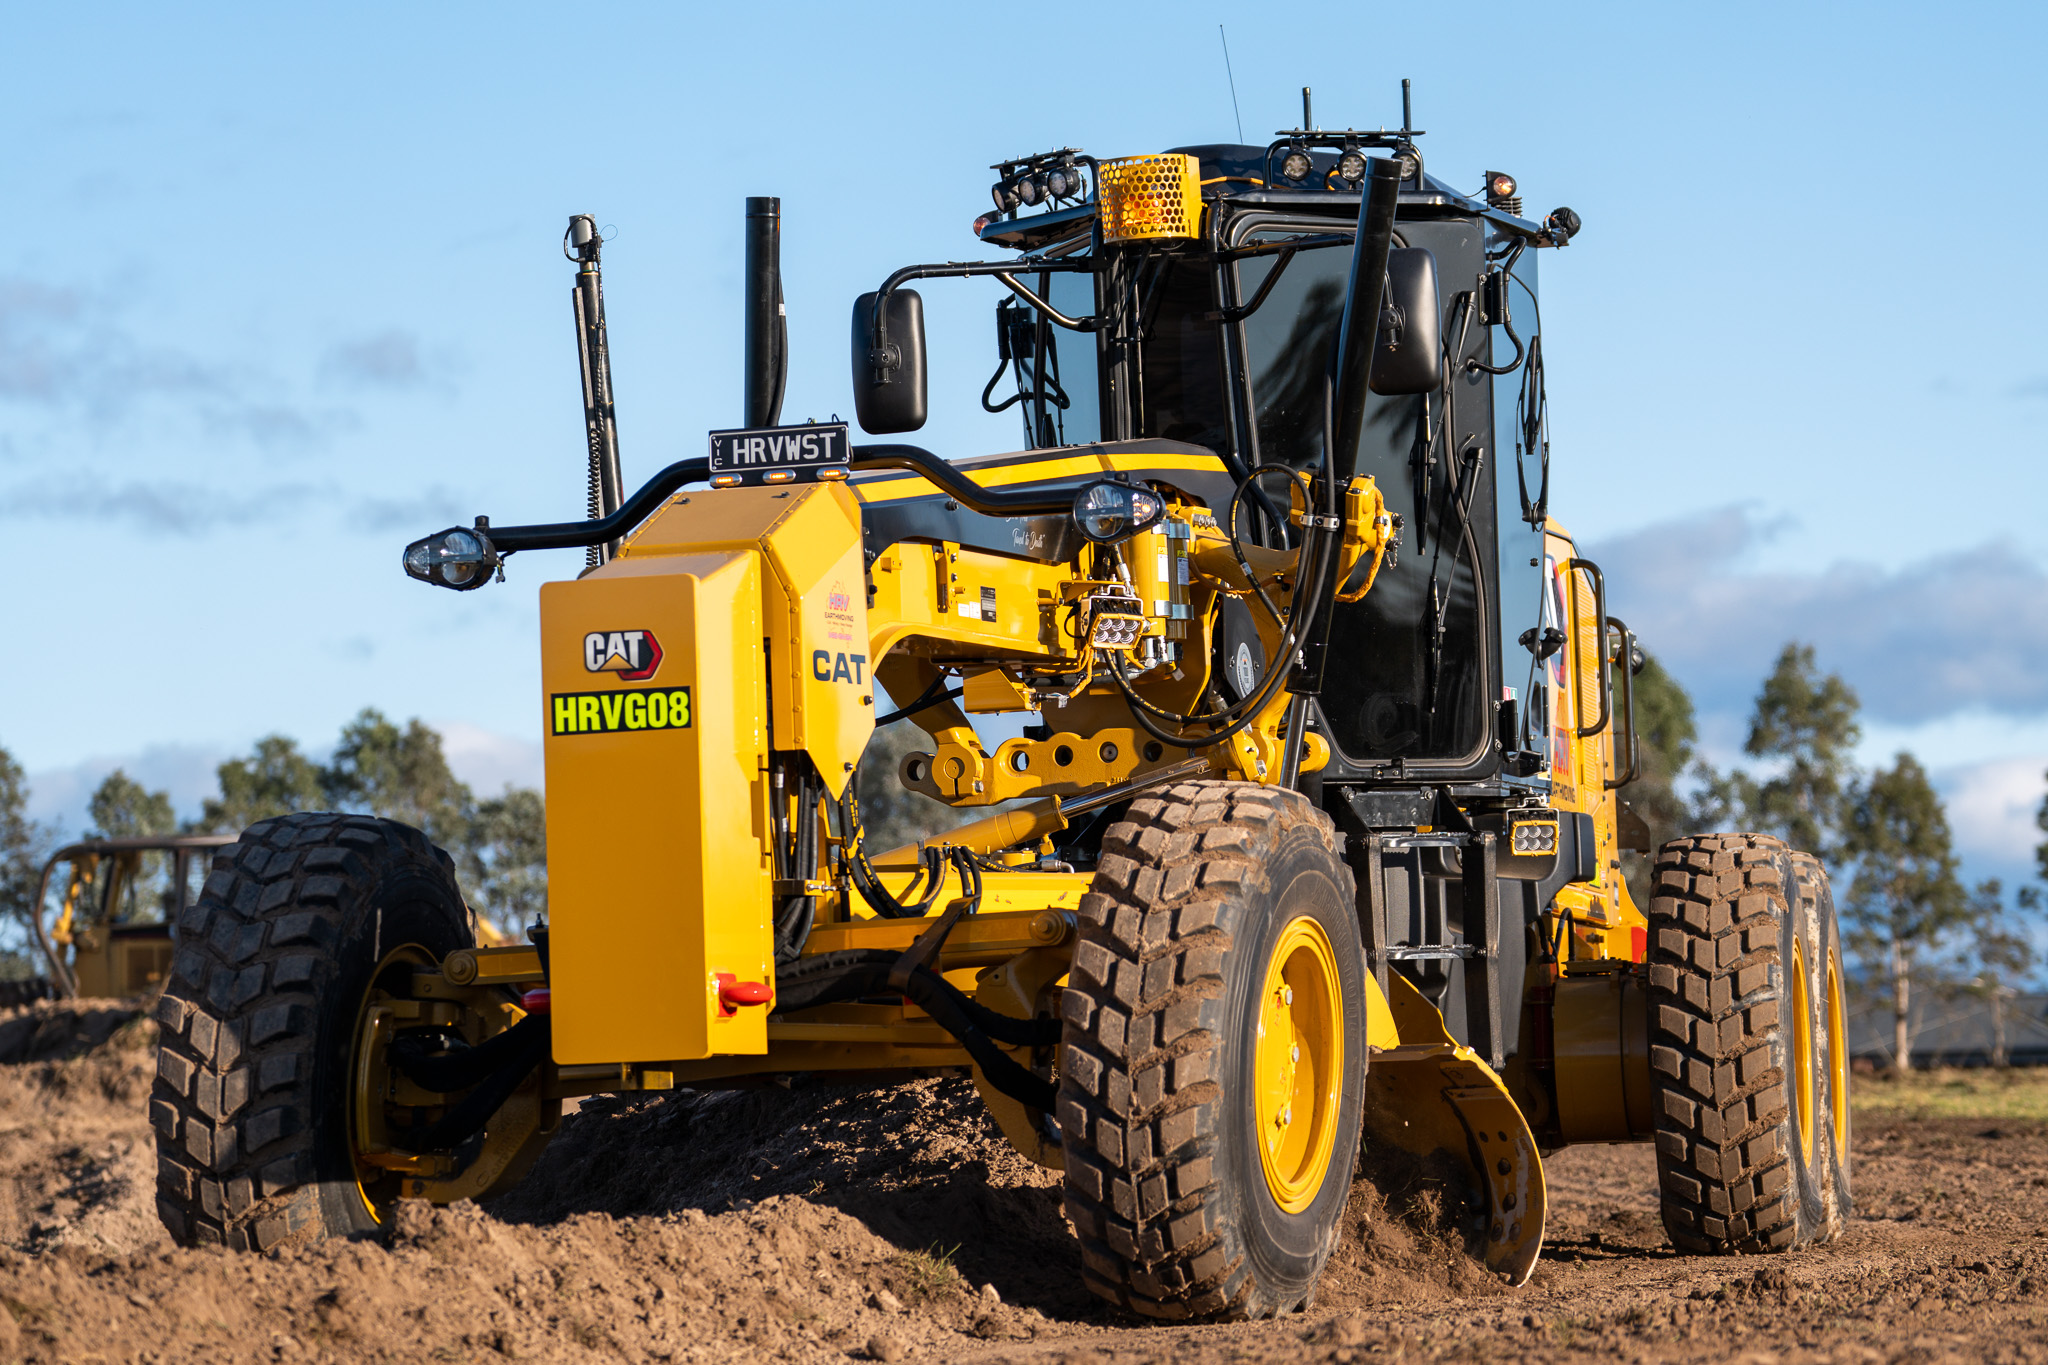
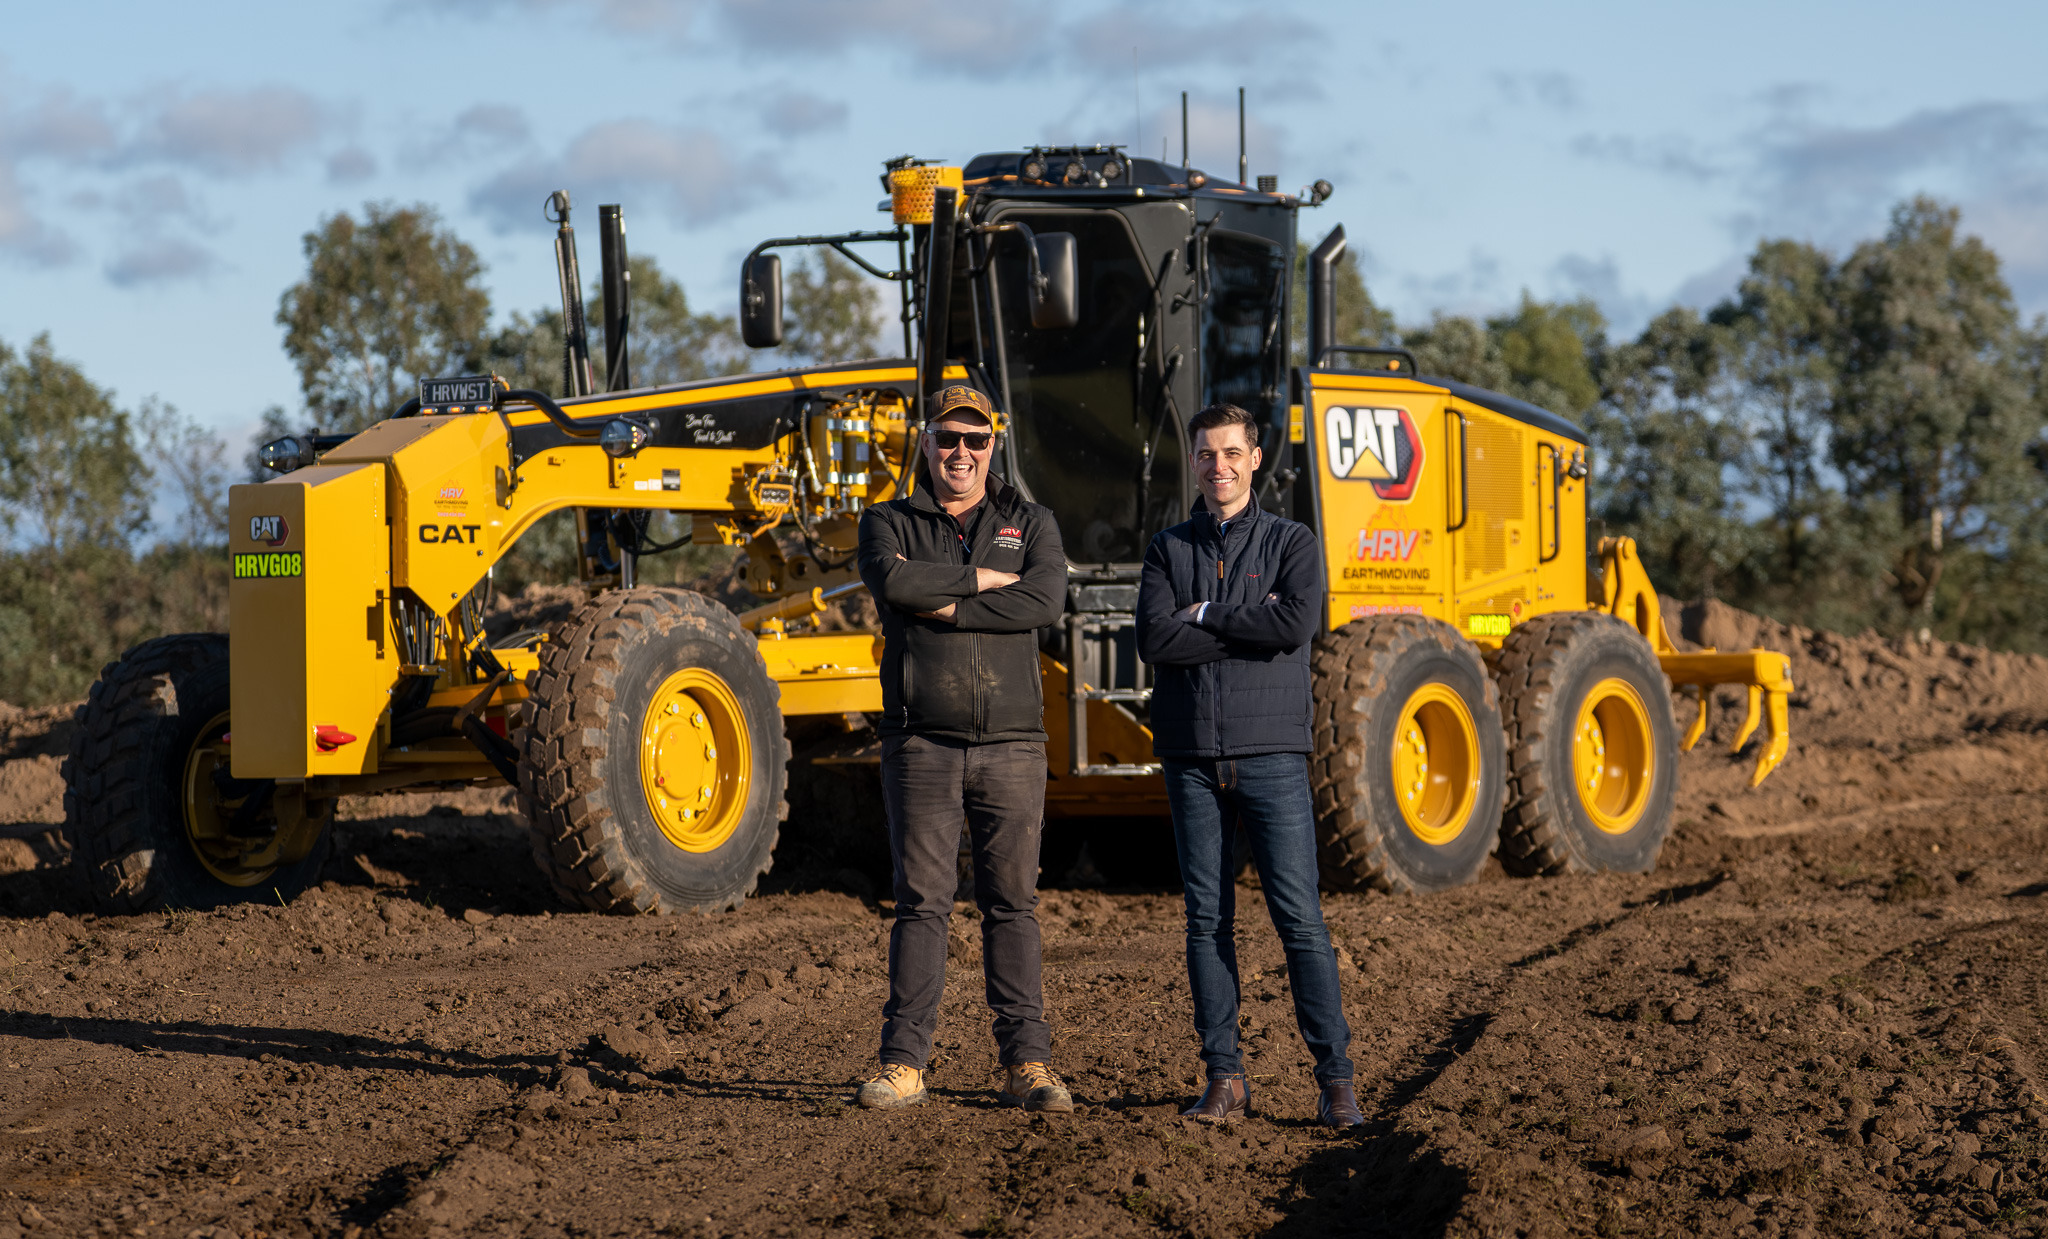
Rob and James talking at HRV’s propertyTwo members of the HRV team beside a Caterpillar grader

More about MFG Finance.

Crezzco’s acquisition and quarry mobilisation show how we plan equipment finance around the wider business and its next contract.

See how we work ↓

Buying through a dealer, privately or at auction?

We work with business operators Australia-wide. Bring us the machine, the seller and the purchase timing.

Crezzco bulk haulage trucks on the road

New or used through a dealer

Bring us the machine, supplier quote and delivery timing. We can assess the equipment and proposed fit-out together. Older machines are welcome for assessment too.

Buying from a private seller

We liaise with your vendor on the paperwork the lender needs and manage the finance through to settlement, including payment to the seller.

Buying at auction

Speak with us before bidding. We work through the machine, auction terms and funding approval so you understand your purchasing budget and settlement requirements.

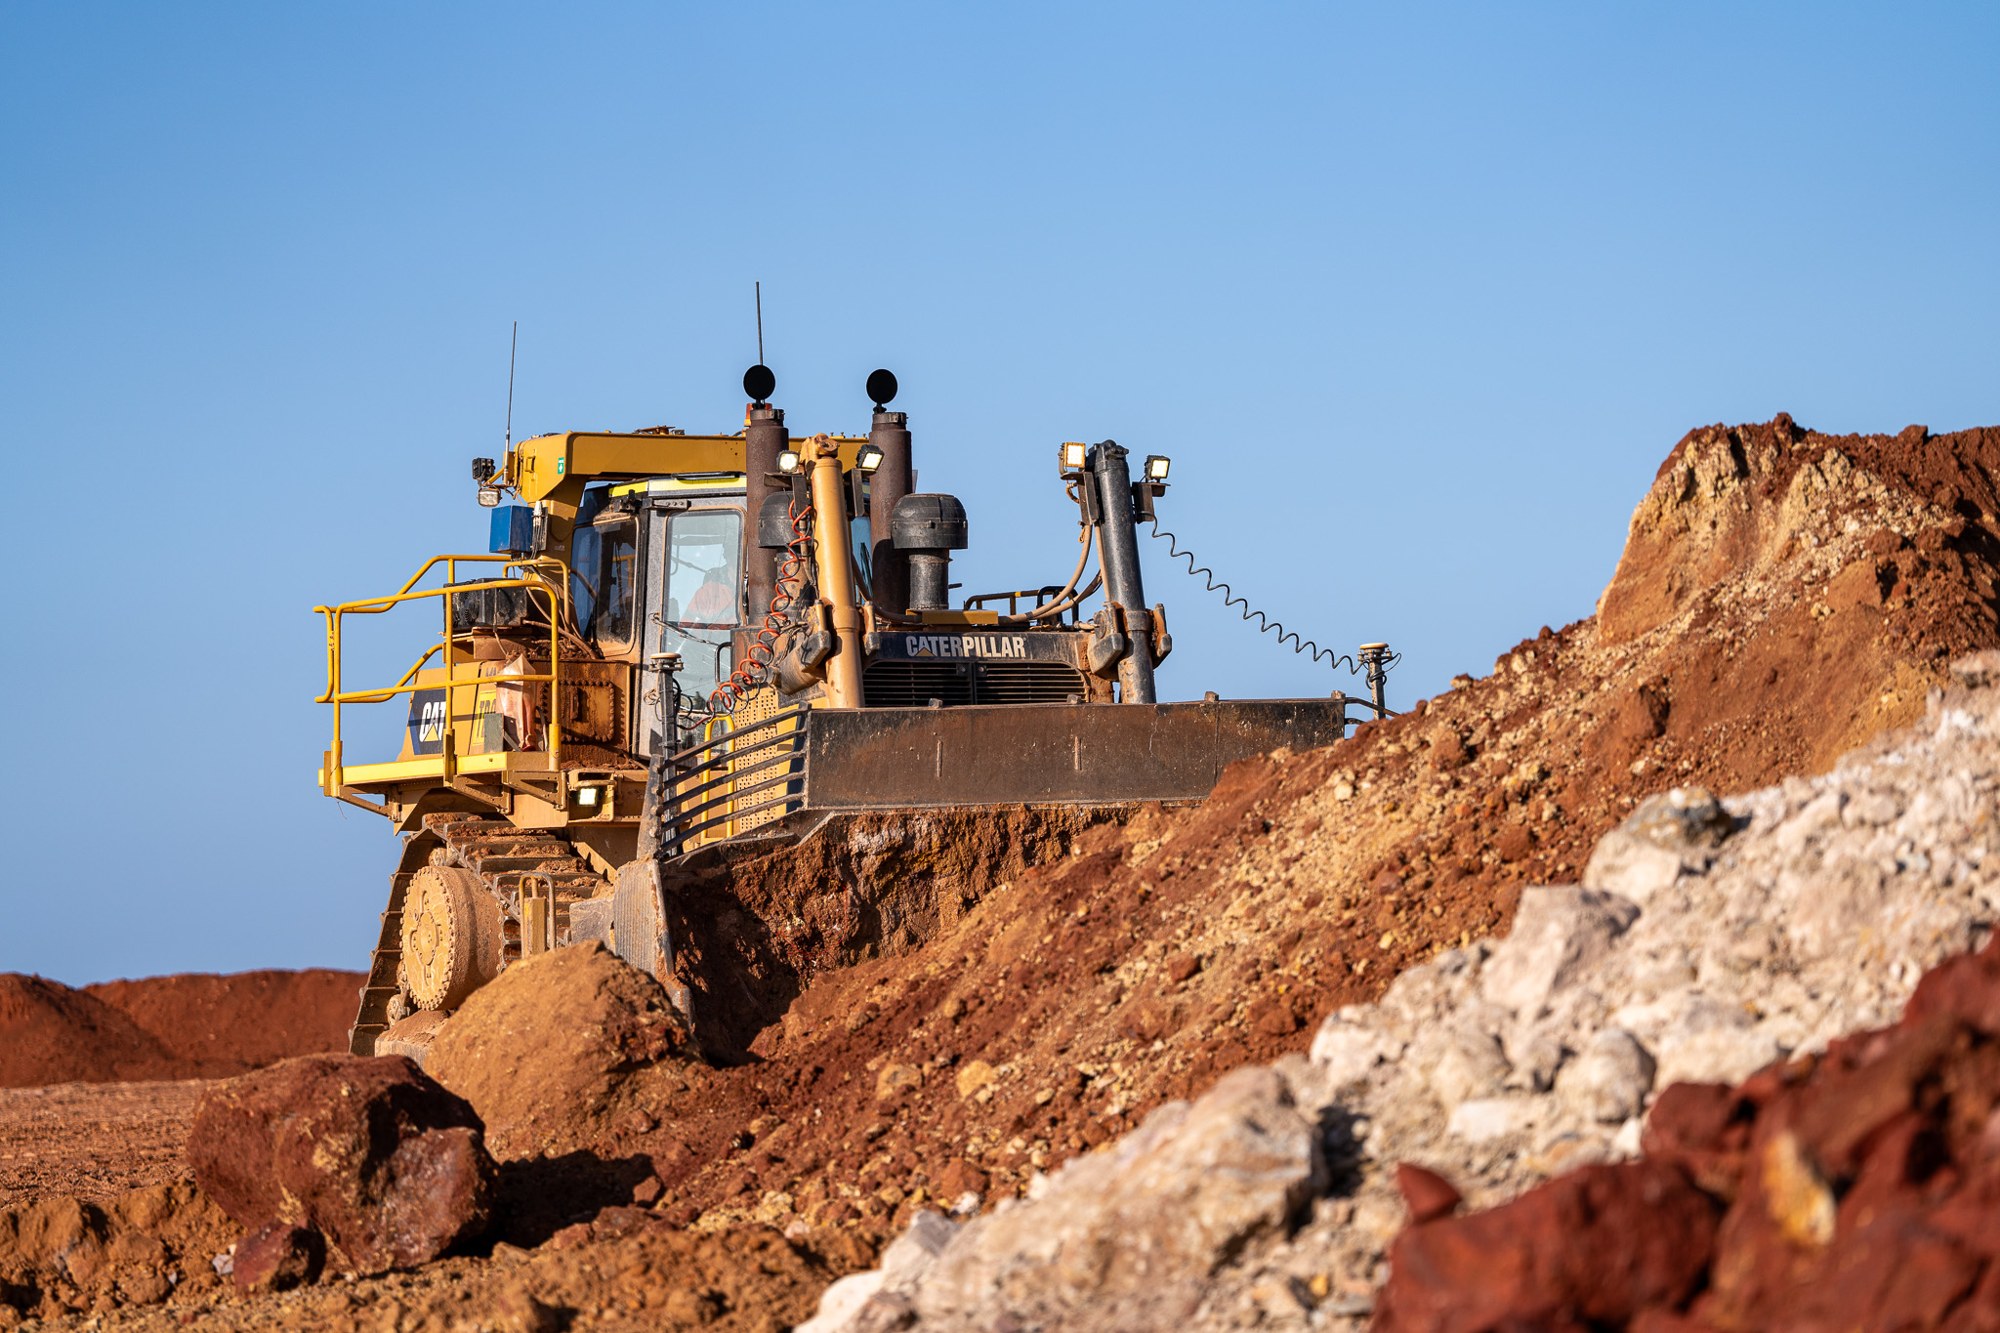
equipment working through earth at a mine site

Still shopping? Start with a pre-approval.

You can start the finance conversation before choosing the final machine. We can assess your position and establish a budget to shop within, subject to lender and asset conditions.

Buying at auction? Organise finance before bidding, so you understand the funding amount, conditions and settlement deadline.

Talk through a pre-approval ↗

Brokers who go beyond the approval

A well prepared credit case, a clear view of capacity and a plan for the equipment you’ll need next.

Business owner to business owner

We’re an owner-led boutique brokerage without a sales team, sales KPIs or targets. We consult directly with business owners, taking the time to understand the machinery, the business and what comes next.

We see opportunities others miss

James and Dan have worked in bank credit and broking. We review the financials, existing debt and supporting information before approaching lenders, and work with you and your advisers to explain material entries or changes clearly. A well prepared application gives lenders a fairer picture of the business.

Your approval today shapes your next move

We map fleet debt, lender exposures and available capacity between lenders. Deposits, repayments, balloons and replacement timing are considered together, so this equipment purchase keeps your future equipment needs in view.

James Allan with a Mineral Mining Services business owner on site
Mining and quarry team overlooking crusher and screener equipment

With you from the first asset to a major fleet.

The first working asset.

Funding the machine that gets the business moving, with the work and repayment capacity in view.

A fleet taking shape.

Planning equipment for new contracts, replacement purchases and the next stage of growth.

Multiple assets.

Coordinating lender exposure, fleet debt and annual funding capacity so the next move has room.

Finance for the purchase, the fleet and the business.

From an urgent acquisition to a planned fleet renewal, we match the funding approach to your timing and the wider debt position.

Working equipment fleet on site

Traditional full doc finance

Using your last two years of financials and recent reporting, we prepare a thorough application for major banks and specialist equipment finance lenders. We explain the business, the purchase and the numbers behind it.

Low doc finance

Available when an urgent approval or settlement leaves little time for a full financial submission. We use low doc options selectively and preserve that capacity for the moments you need it, subject to lender criteria.

Master limits

An annually reviewed ceiling for individual equipment acquisitions throughout the year, typically from $1 million to $50 million. For growing fleets, an agreed limit brings clearer visibility to funding capacity. Each purchase remains subject to the facility’s terms and lender requirements.

Business lending

Debtor finance, overdrafts, term loans and other commercial facilities can support the business around the fleet. We consider cash flow, existing security and equipment commitments together, then work with suitable business lenders and bankers.

Trade old fleet for new

Know what every machine owes and what can be traded towards new equipment. We map payouts, trade values and replacement plans, including assets with existing debt, and coordinate supplier timing so the funding and fleet rollout work together.

Refinancing and consolidation

Rapid growth can leave debt scattered across lenders or facilities that no longer suit. We assess restructuring with one or several lenders to release capacity where possible, improve the debt arrangement and reopen funding lines, accounting for payouts, costs and available security. Adjusting the term and repayment structure may also soften monthly repayments and ease cash flow pressure; a longer term can increase the total interest paid.

Talk through the right approach
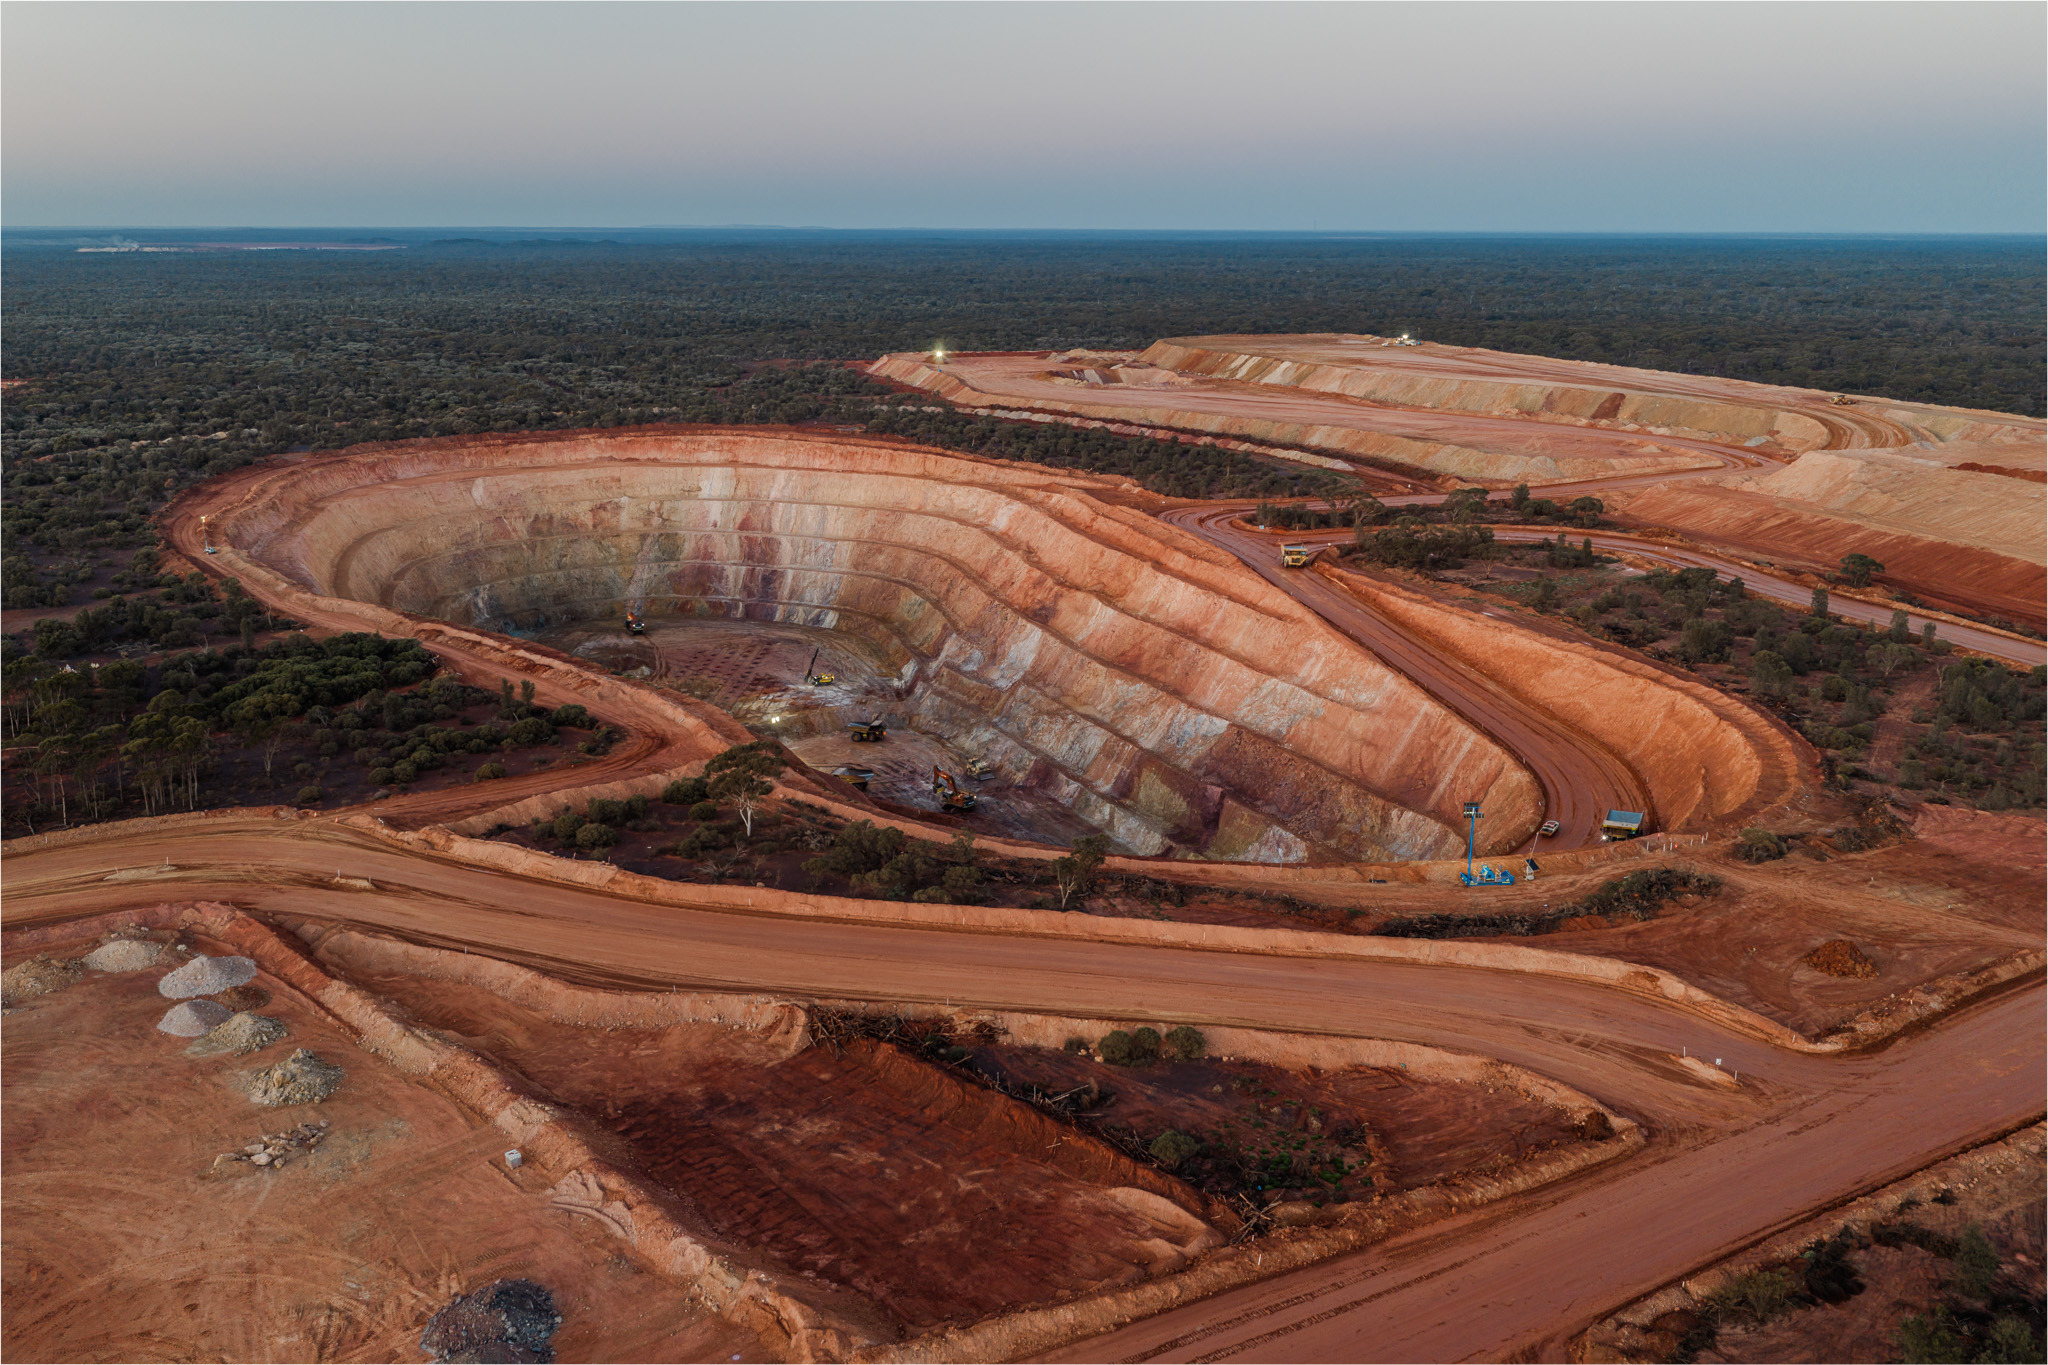
Aerial view of an open pit mine and haul roads

Run the numbers to plan your next move

See how term, rate, balloon and payment timing change the monthly commitment.

Equipment loan

Adjust the figures to explore a scenario.

Term 60 months
Balloon 0%
Payment timing
Estimated monthly repayment$7,011.62Payments in arrears
Total repaid, including balloon$420,697.14
Estimated interest$70,697.14
Balloon at end of term$0.00
Amount financedInterest

Illustration only. Assumes a fixed nominal annual rate divided into monthly periods, level monthly payments and a balloon due at the end. Excludes fees, taxes and insurance. In advance means the first repayment is made at the start. This is not a lender quote.

Talk through the purchase →

Fully accredited, ethical, insured and trustworthy.

MFG is directly accredited with all major banks, alongside an extensive panel of non-bank, specialist and private lenders.

CAFBACAFBA 101556
FBAAFBAA M-359967
Australian Financial Complaints AuthorityAFCA 89354
  • Never lost a lender accreditation
  • Not reliant on another firm’s accreditations
  • No shared commissions or kickbacks with referrers
  • No upfront establishment fees; we’re paid by lenders
  • Insured, accredited, independent and trustworthy
Our lender panelMajor banks · non-banks · specialist and private lenders
ANZ
Commonwealth Bank
NAB
Westpac
Macquarie
Bank of Queensland
Judo Bank
DLL Financial Solutions
ORIX
Pepper Money
Metro Finance
Capital Finance
FlexiCommercial
Grenke
Banjo
Shift
ScotPac
Moneytech
Finance One
Australian Finance Solutions
Angle Finance
Azora Finance
Commercial Equity Group
Yellowgate
COEX Capital
Iron Capital Group
Maple
Morris Finance
SELFCO
Westlawn Finance

Panel shown is indicative and subject to lender accreditation, credit policy and transaction requirements.

Frequently asked questions.

Why work with MFG for equipment finance?

You deal directly with James or Dan. We have worked inside credit, so we look at how a lender will assess the business as well as the equipment. The aim is to fund this purchase without losing sight of the next one.

Do you charge an upfront fee?

We do not charge an upfront brokerage establishment fee. We are paid by lenders when a transaction settles. If a lender has its own fees, we will show you those in the proposed terms before you commit.

What kinds of equipment can you finance?

We work with commercial equipment and business vehicles across earthmoving, mining, transport, agriculture, manufacturing, aviation and other heavy industries. New, used, single assets and whole fleets are all worth a conversation. We do not arrange personal car loans.

Can you finance used or older equipment?

Often, yes. Age alone does not decide it. The lender will also look at the equipment type, condition, hours or kilometres, value and how the business will use it. Tell us what you are considering before you lock in a short settlement date.

What if I am buying privately, at auction or interstate?

Those purchases can be financed, but the paperwork and timing matter. We may need to check ownership, identification, condition, value and how payment will be made. Auction deadlines in particular can be tight, so involve us early.

How quickly can finance be approved?

It depends on the business, the equipment, the lender and whether the information is ready. A straightforward repeat purchase may move quickly; a larger or more involved transaction needs more work. Give us the deadline and we will tell you what is realistic.

What interest rate will I get?

There is no one rate that fits every purchase. The lender, business profile, equipment, deposit, term and repayment structure all affect the offer. We compare the whole deal, including fees, balloon and future borrowing capacity, rather than quoting a headline rate in isolation.

Can I apply without full financial statements?

Possibly. Some lenders offer reduced-documentation options for eligible businesses. We will look at whether that route actually makes sense, because a full assessment can sometimes lead to a better structure or more room for the next purchase.

Can you help a newer business or one with a credit issue?

We can look at the position and tell you honestly where it stands. Trading history, contracts, cash flow, deposit and the reason for any credit issue all matter. There is no blanket yes or no, and we will not promise an approval we cannot support.

Do I need a deposit?

Not always. It depends on the business, equipment and lender. We will weigh up the benefit of keeping cash in the business against the cost and terms of borrowing more.

How much can I borrow and over what term?

That depends on the purchase, the business’s ability to repay, existing commitments and the lender’s policy. The useful question is what level of debt and repayment suits the work the equipment will do, not just the maximum someone will approve.

What is a balloon payment?

It is an agreed amount left to pay at the end of the term. It can reduce regular repayments, but the final amount still needs a plan. We look at likely resale value, replacement timing and the payout before recommending one.

Can we finance several purchases as part of one plan?

Yes. If you are building or replacing a fleet, we can map the purchases, allocate them across lenders and consider an equipment finance limit where the business qualifies. That can help preserve capacity for what comes next.

Can we arrange finance before we choose the exact equipment?

Sometimes. Depending on the lender and the business, we may be able to assess a funding limit or obtain an indication before the final asset is known. The lender will still need to approve the actual equipment and seller before settlement.

Can you refinance equipment we already own or have financed?

We can review it. The existing payout, current value, remaining term and reason for refinancing will determine whether there is a worthwhile option. We will also consider how it affects your broader lender capacity.

How does a trade-in affect the new finance?

We need the trade value and any payout on the existing loan. The equity or shortfall becomes part of the new purchase calculation, so it is best to work through both sides before you agree to the deal.

Can you finance imported equipment?

Potentially. Imported purchases need more planning around supplier terms, currency, shipping, identification and when the lender can take security. Bring us in before a deposit or payment milestone is due.

Can I make extra repayments or pay out early?

That depends on the lender and product. Some facilities allow flexibility; others may have early payout costs or a different interest calculation. If early repayment is likely, tell us at the start so we can factor it into the structure.

What finance options do you consider?

A chattel mortgage is common for business equipment, but it is not the only structure. Depending on the purchase, we may also consider a lease or another facility. We will explain who owns the equipment, the repayment and any final amount before you choose.

Can two related businesses be involved in the purchase?

Sometimes. We need to be clear about which entity is buying the equipment, which one will use it and where the income sits. We can map the group and approach lenders that are comfortable with that structure.

I already have a quote. Can you look at it?

Of course. Send the full terms, not just the rate. We will look at fees, balloon, security, flexibility and what the deal might mean for the next purchase. If your existing offer is the right one, we will tell you.

How do we get started?

Tell us what you are buying, the price, seller and timing, plus a little about the business and its existing finance. James or Dan will talk through the purchase with you and outline the information needed for the right lenders.

Can GPS, attachments and modifications be included?

We can assess the machine and its attachments together, including GPS, machine control, buckets, rippers and other work-specific equipment. Share the complete supplier quote and installation timing so the full purchase can be considered.

What is an equipment finance master limit?

It is an agreed funding ceiling for eligible purchases during a defined period, usually reviewed annually. It can help a qualifying business plan several acquisitions without starting a fresh full application for every machine. Each drawdown still has to meet the lender’s facility conditions.
Give your business the finance it deserves

Tell us about the equipment, the work it will do and what you’re planning next. James and Dan will work through the purchase in the context of your business.

Talk to James and Dan ↗

Tell us what you’re working towards.

Buying your first machine? Replacing a fleet? Start with the situation as it is. We’ll talk through the assets, the timing and what the next decision means for your business.

Let’s grow together.

Replacing equipment or planning the next purchase? Tell us what you have in mind.

"*" indicates required fields

This field is for validation purposes and should be left unchanged.
Name*